


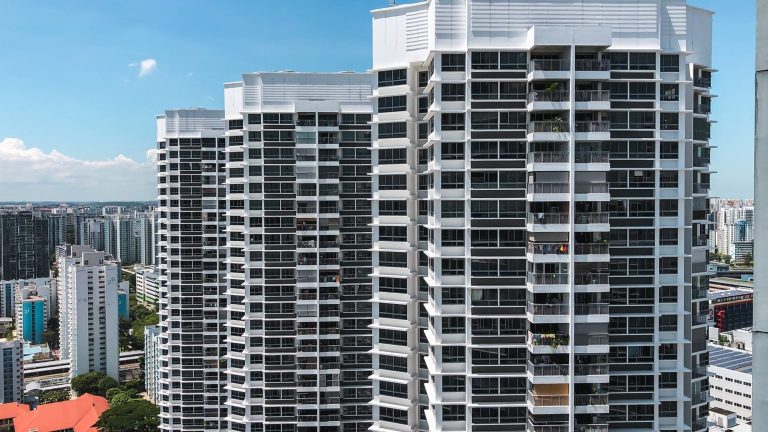
Steep price discounts offered by Hoi Hup Realty and Sunway Developments appear to have helped the developers sell at least 32 units at Terra Hill over the month of September this year, setting a median selling price of $2,209 psf.
Amid an absence of major new launch projects last month, this was enough to see the District 5 condominium climb to the top of the new private home sales last month.
We reported that Terra Hill was offering discounts of up to $1.63 million for some of its remaining unsold units, many of them ground floor or high-ceiling penthouses. The developer seemed to be offering these discounts to spur sales in the 270-unit development, ahead of the expected project completion in 1Q2027.
Likewise, another already-launched project was among the top selling new projects in September 2026. The Sen moved at least 25 units last month, and set a median selling price of $2,386 psf. The 99-year leasehold project on Jalan Jurong Kechil initially launched for sale in November 2025.
This year, a good portion of the month of September coincided with the month-long Hungry Ghost Festival, which ran from Aug 13 to Sept 10 this year. Traditionally, during this period, some buyers hold back on large purchases like property as it is deemed inauspicious.
Nevertheless, developers made up for the lull in buying activity by focusing their efforts on the second half of the month. In total, developers sold 296 new private residential units in September, a monthly increase of 93.5% and a 16.1% y-o-y increase over the same period in 2025.
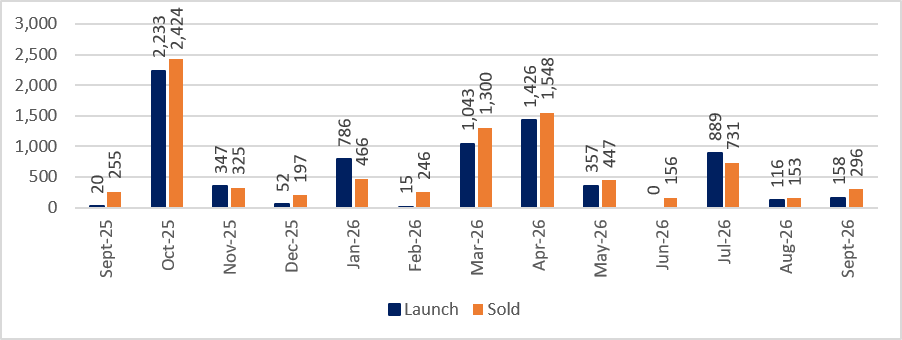
In all, developers launched 158 new private residential units for sale last month, a 36.2% m-o-m increase and 7.9 times more than a year ago.
This brings the total number of new private homes launched between January to September to 4,790 units. It is 41.9% lower than the 8,247 units that developers injected into the market over the same nine-month period in 2025.
The latest developer sales data also means that, for the first nine months of 2026, property developers have sold a total of 5,334 new private residential units (excluding ECs). This is less than the 7,875 units which were sold over the corresponding period in 2025.
Overall, the sales figures last month suggest a steady base of demand even when launches are thin, with buyers continuing to consider options at existing projects, says Wong Siew Ying, Head of Research and Content at PropNex Realty.
However, she adds that the pace of sales will be influenced by the availability of units, pricing and the appeal of each project. "To this end, developers will need to price their remaining inventory competitively and offer attractive value propositions to sustain sales momentum," she says.
Top Projects by Sales in September 2026
| Project Name | Region | Units Sold in the Month | Median Price ($psf) | Lowest Price ($psf) | Highest Price ($psf) |
| TERRA HILL | RCR | 32 | 2,209 | 1,934 | 2,544 |
| THE SEN | RCR | 25 | 2,386 | 2,273 | 2,625 |
| AMBERWOOD AT HOLLAND | CCR | 24 | 3,021 | 2,852 | 3,119 |
| LENTOR GARDENS RESIDENCES | OCR | 22 | 2,348 | 2,323 | 2,455 |
| UNION SQUARE RESIDENCES | RCR | 21 | 2,813 | 2,603 | 3,164 |
| LUXUS HILLS | OCR | 18 | 3,455 | 2,894 | 3,520 |
| THE CONTINUUM | RCR | 16 | 2,716 | 2,513 | 2,809 |
| CHUAN PARK | OCR | 10 | 2,708 | 2,325 | 2,733 |
| DUNEARN HOUSE | CCR | 10 | 3,105 | 2,872 | 3,356 |
| BELGRAVIA ACE | OCR | 9 | 1,281 | 1,210 | 1,400 |
With Terra Hill and The Sen taking up the top two positions in terms of developer sales last month, it's not unexpected that buying demand was largely supported by previously launched projects across the Rest of Central Region (RCR) at almost 44.3%, and the Outside Central Region (OCR) at 42.2%, says Mohan Sandrasegeran, Head of Research & Data Analytics at SRI.
Sales in the RCR and OCR accounted for 256 (86.5%) of the 296 new private residential units last month, excluding ECs. Other best-selling projects last month were Lentor Gardens Residences and The Continuum.
It is more than likely that OCR sales will pick up in October given that Lucerne Grand has sold 350 out of its 570 units over its Oct 3-4 weekend sales launch, says Wong. She adds that the RCR will likewise receive a big boost with the launch of the 1,268-unit Thomson Reserve later this month.
Meanwhile, sales in the Core Central Region (CCR) accounted for 13.5% of the primary market sales volume. However, the median selling price of CCR units sold rose to $3.1 million in September 2026, which is 56.8% higher compared to the previous month.
The attractive prices of previously launched projects, such as Terra Hill and The Sen, may have been a key factor in their sales rebound last month, says Marcus Chu, CEO of ERA Singapore.
“At $2,209 psf for Terra Hill and $2,386 psf for The Sen, the median new-sale prices for both projects were below the wider RCR equivalent of $2,522 psf for new non-landed private homes in September," he says.
At those price points, it would have appealed to value-conscious buyers as well as aspiring private home owners who want to secure a new home before rising land costs filter through to future new launches, says Chu.
Echoing those sentiments, Wong adds that the uptick in sales at Terra Hill and The Sen is project-specific price adjustments rather than a broad shift in pricing, but they show that buyers are still very much in the market and will act when a project stands out on value.
"With more new homes coming onto the market in the final quarter, pricing is likely to set the pace of sales at both fresh launches and those already in the market," she says.
Steady sales in the executive condominium segment
In the aftermath of major policy changes on the executive condominiums (EC) scheme in May this year, some market analysts expect that this would result in a short-term spike in demand for already-launched EC projects.
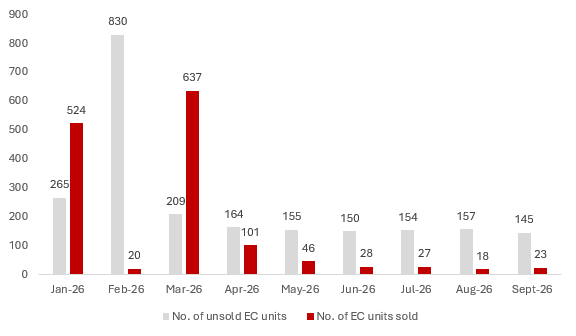
But overall, buying activity in the EC segment was largely stable, with 23 EC units sold at a median price of $1,833 psf. But this still reflects a monthly increase of 27.8% from the 18 units sold in August. On a yearly basis, EC sales rose by 53.3% compared to the 15 units sold in September 2025.
In terms of new EC transactions, Coastal Cabana continued to lead for the fourth consecutive month, with 19 units sold at a median price of $1,811 psf. Rivelle Tampines, which launched in March, accounted for two of the remaining new EC units sold, while Altura and Otto Place each recorded one transaction.
Thus, developer sales data indicates that only 142 EC units remained unsold at the end of September this year.
Number of unsold EC units and EC units sold
Upcoming supply in the EC market will likely come from the 430-unit Wynwood Grand, which could enter the market before the end of this year. In addition, we also expect to see the launch of Solano Grand and another EC at Sembawang Road next year.
Hopeful EC buyers will be on the lookout for the launch of Wynwood Grand, which is the first executive condominium (EC) project in Woodlands since 2014. It is thought that the project could open for e-applications in December, with bookings taking place in January 2027.
Larger quantum deals dominated developer sales in September
Close to 65% of developer sales in September 2026 were for units that fetched at least $2.5 million, driven largely by larger quantum deals at Amberwood at Holland, Belgravia Ace and Luxus Hills.
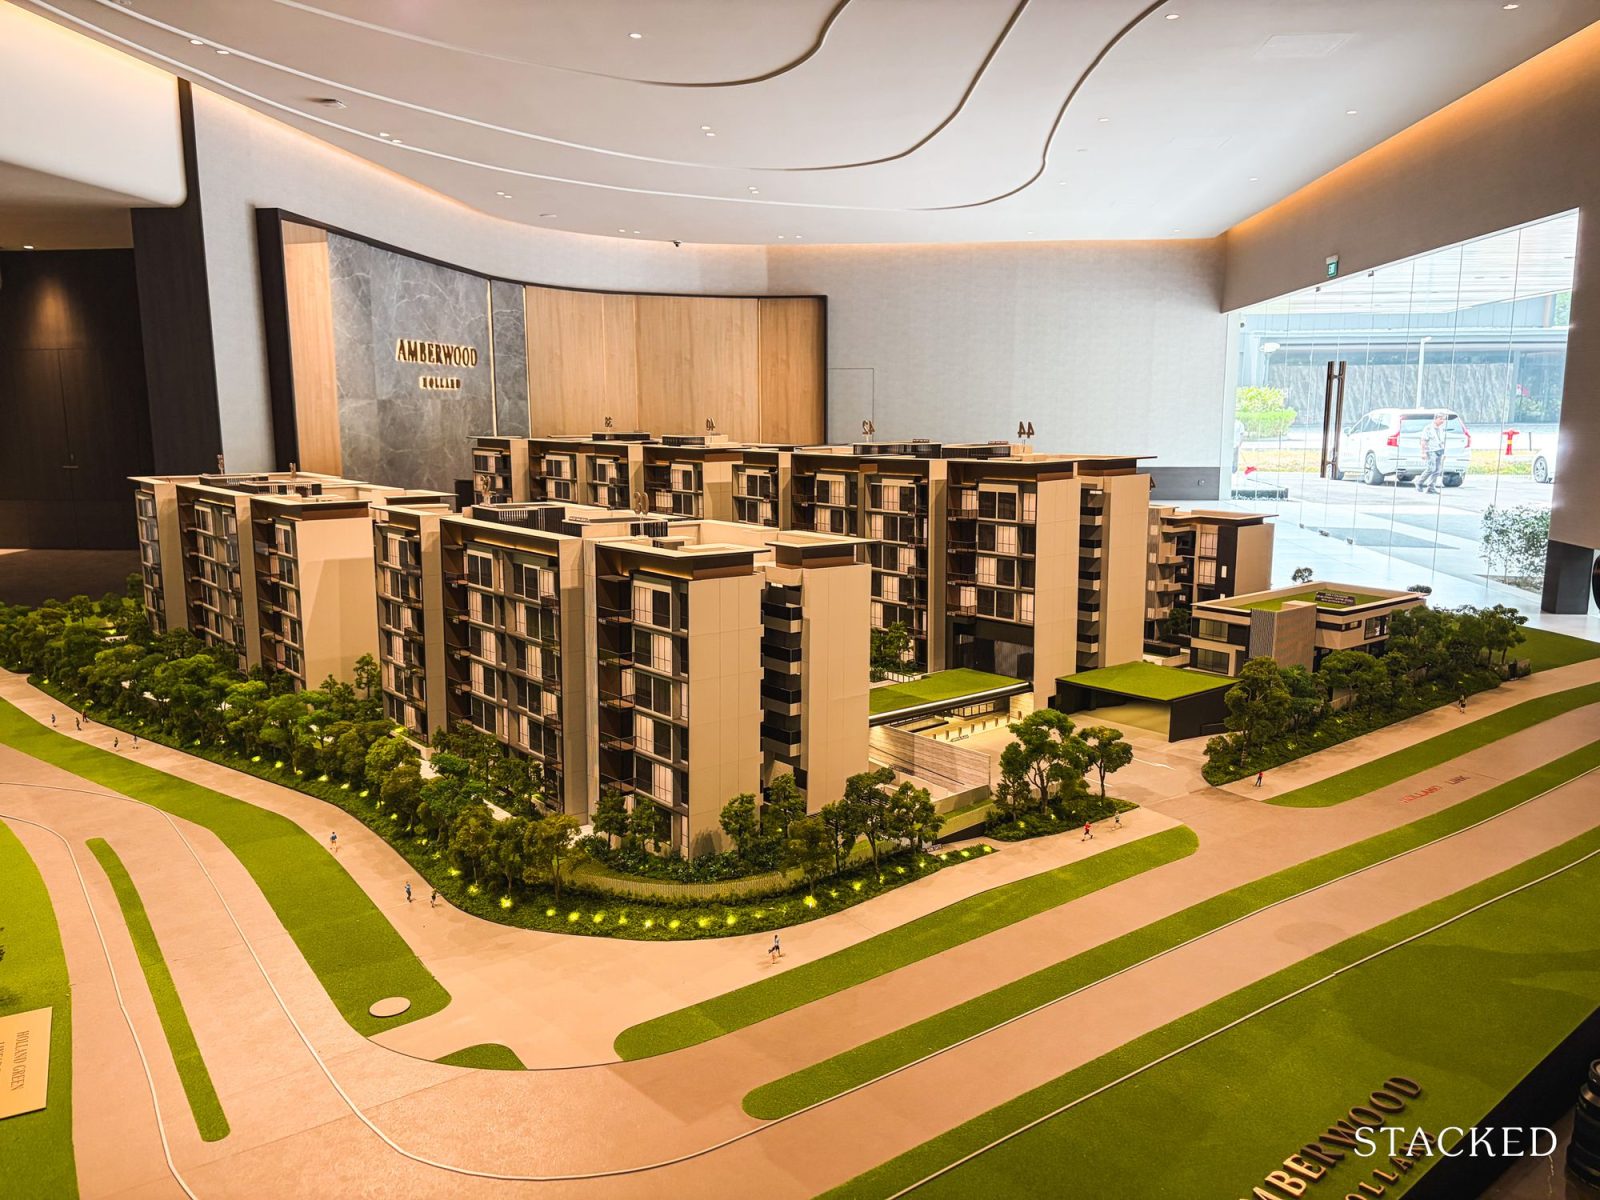
The only new private residential launch in September, Amberwood at Holland sold 24 units when it hit the market over the Sept 25-26 weekend. Only 70 units were reportedly released for sale.
The 212-unit project, which is located in Upper Bukit Timah, appealed to families, with more than 60% of the units sold being four- and five-bedroom units, says Mark Yip, CEO of Huttons Asia.
He adds that the relatively large absolute prices may have limited the pool of willing buyers, with two-thirds of the units sold at Amberwood at Holland transacted for over $3 million.
Landed home sales soared to their highest monthly sales in more than eight years
Of the 296 new homes sold in September, 19 were landed properties — the highest monthly sales volume that this segment has recorded since April 2018, according to market data compiled by Huttons.
With the price premium between a new terrace home and resale unit narrowing to 20.8% in 3Q2026, down from 27.7% in the previous quarter, savvy buyers appeared to lean towards a new terrace home, says Yip, adding: "Significant wealth accumulation over the years has enabled more Singaporeans, many already staying in private residential property, to purchase new landed homes."
The most prominent beneficiary was Luxus Hills, a 999-year leasehold project by Bukit Sembawang Estates (BSE) that is located in the Seletar Hills enclave. The landed project sold 18 terrace houses after a two-month preview period. This is also the 10th sales phase of the long running landed project by BSE.
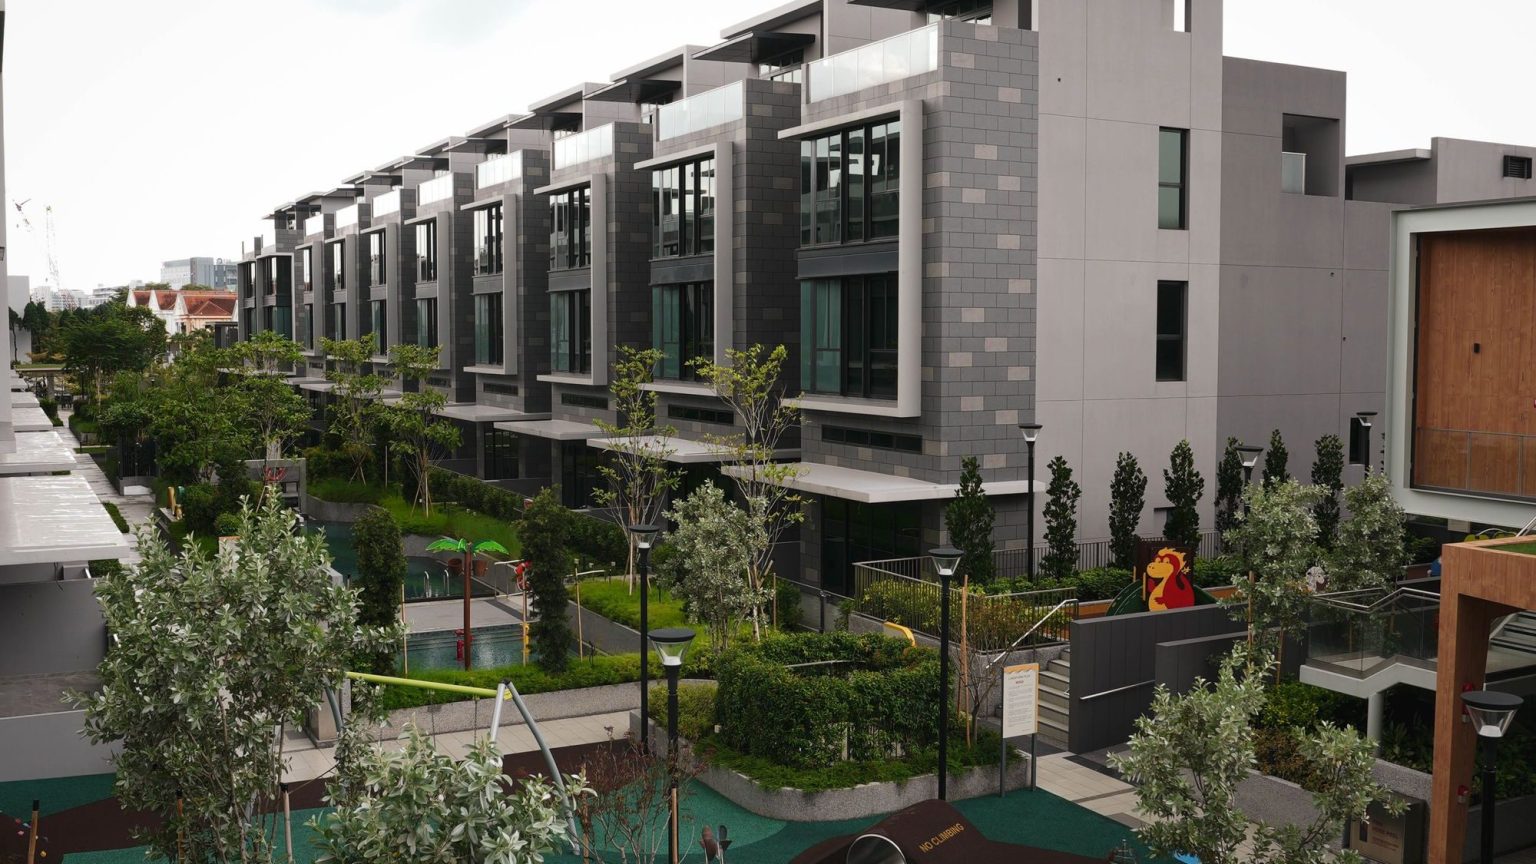
Over at Belgravia Ace, which obtained its temporary occupation permit in September this year, the cluster housing project by Tong Eng Group sold nine semi-detached strata landed units. That pushed up the median price of units sold in the OCR to $3.2 million.
Meanwhile, the most expensive new sale of the month was a 2,088 sq ft unit at Skywaters Residences. The 28th floor unit transacted for an eye-watering $11.48 million ($5,498 psf) when it was reportedly sold to a local on Sept 10.
Outlook
Based on Ministry of Trade and Industry (MTI) estimates, Singapore's economy is expected to record a quarterly growth of 5.4% in 3Q2026, with the growth forecast continuing through 2027.
Leonard Tay, head of research at Knight Frank Singapore, says that the latest interest rate hike by the US Federal Reserve has introduced concerns that borrowing costs will increase in the months and year ahead.
"Even though (local) unemployment levels remain low, retrenchments increased from 3,830 in 1Q2026 to 4,620 in 2Q2026, with layoffs concentrated in sectors such as manufacturing, information and communications, and financial services," he says.
Nevertheless, local buyers are still well supported by healthy household balance sheets, accumulated wealth and confidence in the city-state's long-term prospects. "However, the outlook has turned hazy in the third quarter of this year," says Tay.
Upcoming Projects in 4Q2026
| No. | Project | Developer | Location | District | Tenure | Est Units | Est Launch Period |
| 1 | The Serra Residences | Far East Organization | Bassein Road | 11 | FH | 133 | Oct 2026 |
| 2 | Thomson Reserve | UOL, SingLand and CapitaLand | Bright Hill Drive | 20 | 99 | 1,268 | Oct 2026 |
| 3 | The Park Residence | VONVIEW PTE LTD | Stevens Road | 10 | FH | 43 | Nov/Dec 2026 |
| 4 | Wynwood Grand (EC) | CDL | Woodlands Drive 17 | 25 | 99 | 430 | Dec 2026/Jan 2027 |
| Total | 1,874 |
The sales performance of three new launch projects will shed more light on prevailing sentiment among buyers. The Serra Residences will demonstrate the appetite for new freehold homes in Novena. Meanwhile, Thomson Reserve, where prices start from $1.544 million, will test the price appetite of first-time buyers, owner-occupiers, and investors in the Upper Thomson Road area.
In the ultra-luxury market, The Park Residence on Stevens Road will be a rare opportunity to pick up large-format freehold units above 4,000 sq ft in that prime area.
In light of all of these new launch projects this month, most market watchers expect that developer sales could exceed 1,500 units, reflecting strong underlying buyer interest.
Upcoming Projects in 1Q 2027
| No. | Project Name | Developer | Location | District | Tenure | Est Units | Est Launch Period |
| 1 | Chencharu Central Residences | Evia MCS Pte. Ltd., Gamuda (Singapore) Pte. Ltd. and H108 Pte. Ltd. | Chencharu Close | 27 | 99 | 876 | Jan 2027 |
| 2 | Solano Grand (EC) | CDL | Senja Close | 23 | 99 | 302 | Jan/Feb 2027 |
| 3 | Dorset Gardens | UOL, SingLand & Kheng Leong | Dorset Road | 8 | 99 | 425 | Feb 2027 |
| 4 | One Chuan Grove | Sing Holdings Residential Pte. Ltd. and Sunway Developments Pte. Ltd. | Chuan Grove | 19 | 999 | 1,056 | Feb 2027 |
| 5 | Sembawang Road (EC) | Oriental Pacific Development Pte. Ltd. | Sembawang Road | 27 | 99 | 265 | Feb 2027 |
| 6 | The River Opus | Frasers Property & Mitsubishi Estate | Former Valley Point | 9 | 999 | 407 | Feb 2027 |
| 7 | Bedok Rise Residences | Allgreen Properties | Bedok Rise | 16 | 99 | 374 | Mar 2027 |
| 8 | Former Chiku Mansions | Macly | Chiku Road | 15 | FH | 7 | Mar 2027 |
| 9 | Redevelopment of Yishun 10 | Frasers Property | Yishun Central | 27 | 99 | 110 | Mar 2027 |
| Total | 3,822 |
Tay also points out that developers have just one remaining window of time in the remainder of the year, from October until the third week of November when the year-end school holidays begin.
"Given the reduced launches in Q3 2026 and homebuyer sentiment turning more selective, new home sales are now more likely to end the year below the original projection of 8,000 to 10,000 units, possibly ranging between 6,500 to 7,500 units instead," he says.
He is also concerned that land rates at government land sales (GLS) tenders have been increasing as top bids become more bullish. Citing market data compiled by Knight Frank, the average land rate for non-landed residential GLS sites increased about 21% during the 12-month period from 4Q2025 to 3Q2026 when compared against the duration between 4Q2024 and 3Q2025.
"While this reflects continued confidence in Singapore's long-term housing demand vis-à-vis the scarcity of quality development opportunities, higher land costs translate into higher future launch prices," says Tay.
Despite firm demand amid tighter new-home supply, with new project prices projected to rise by 3% to 4% in the coming months, it may be prudent for most aspiring private home buyers to consider affordability and long-term needs before committing to a purchase.
0 Comments