


Hi Stacked,
We live in a four-room BTO flat at Bedok South Horizon, and we recently granted an option to purchase (OTP) to a buyer. But this leaves us unsure what to buy for our next family home.
We're a family of three with a helper and are planning for a second child. We'd like somewhere as convenient as our current home, with a primary school and an MRT station on our doorstep. It would be preferable if we could continue to stay in the East, since it is close to both of our parents.
One housing solution that we are considering is moving into a five-room flat at Bedok South Horizon, which would give us the same access to conveniences that we have enjoyed so far, as well as more financial freedom compared to buying a condo unit.
The condos we're considering are euHabitat (four-bedroom), Grandeur Park Residences (four-bedroom), the Waterfront series (four-bedroom), Tierra Vue (three-bedroom) and Cote D'Azur (three- or four-bedroom).
After repaying our outstanding loan, we expect to receive about $976,000 in sale proceeds. We're comfortable using another $100,000 from our CPF Ordinary Account and nearly $500,000 in cash to fund our next purchase.
Between my wife and me, our combined gross income is $32,000 a month. We'd like to keep our mortgage repayment to around $7,000 a month.
Thank you!
(This is part of an ongoing series where we answer reader questions about the property market. If you have one of your own, send it to stories@stackedhomes.com.)
(This is part of an ongoing series where we answer reader questions about the property market. If you have one of your own, send it to stories@stackedhomes.com.)
Hi, and thanks for writing in!
Once a BTO flat reaches its minimum occupation period (MOP), many owners who stand to gain healthy resale profits naturally consider a private property as their next purchase.
With about $976,000 expected from the sale of your four-room flat after clearing the loan, that upgrade is now well within reach. And we think that a five-room flat at Bedok South Horizon would give you more space in the same estate you already like living in.
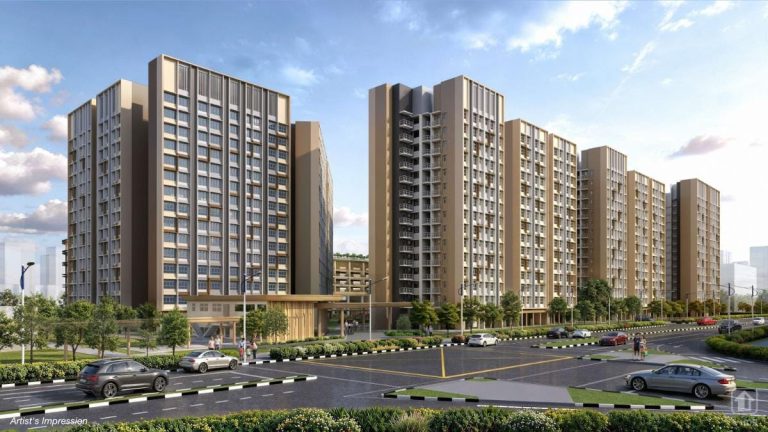
The advantages of that HDB development are apparent: Temasek Primary is about 200m from the estate, Bedok South MRT station on the Thomson-East Coast Line opens on 26 December 2026, and your parents stay nearby.
So we'll compare each condo on your shortlist with the five-room flat, looking at how much more you'd pay and what the extra money gets you in space, convenience and price growth.
How much can you comfortably spend on your next home?
With a gross household income of $32,000 a month, your preferred monthly mortgage repayment of around $7,000 each month works out to roughly 22% of your income. We'll use that as the starting point for comparing your options.
Based on what you've shared, these are the funds you have for your next home:
| Source of funds | Amount |
|---|---|
| Expected proceeds from your flat sale after repaying the outstanding loan | $976,000 |
| Additional CPF OA savings you're comfortable using | $100,000 |
| Additional cash you're comfortable using | $470,000 |
| Total before transaction costs | $1,546,000 |
We've treated the $976,000 sale proceeds as the combined cash and CPF proceeds from your sale. This assumes any CPF refunded from the sale is already in that sum, and that the $100,000 in OA savings is separate.
How far these funds stretch depends partly on your loan tenure. As we don't know your ages, we've shown three possible tenures below at an assumed interest rate of 4%, each keeping the repayment at $7,000 a month.
| Loan tenure | Loan at $7,000/month | Approx. purchase price | Est. Buyer's Stamp Duty (BSD) | Total cost including BSD |
|---|---|---|---|---|
| 20 years | $1,155,000 | $2,601,000 | $99,650 | $2,700,650 |
| 25 years | $1,326,000 | $2,764,000 | $107,800 | $2,871,800 |
| 30 years | $1,466,000 | $2,897,000 | $114,450 | $3,011,450 |
These estimates assume you put the full $1.546 million towards buying the property. Purchase prices are rounded to the nearest $1,000, and the totals leave out legal fees and renovation costs.
We'll use the 25-year loan when comparing the condos. On that basis, a condo priced at around $2.76 million would use up the funds you've set aside and bring your repayment to your $7,000 ceiling.
If you kept $100,000 of those funds aside for renovation costs or future family expenses, the purchase price would come down to about $2.67 million, with the same monthly repayment.
Your income could support much more than this. Without the $7,000 cap, and assuming no other debts, the 55% Total Debt Servicing Ratio (TDSR) would allow repayments of up to $17,600 a month at the 4% rate banks use to test affordability.
| Loan tenure | Approx. maximum loan | Approx. purchase price | Est. BSD | Total cost including BSD |
|---|---|---|---|---|
| 20 years | $2,904,000 | $4,255,000 | $194,900 | $4,449,900 |
| 25 years | $3,334,000 | $4,660,000 | $219,200 | $4,879,200 |
| 30 years | $3,686,000 | $4,992,000 | $239,120 | $5,231,120 |
Borrowing more can work in your favour. Say you buy a $2.76 million condo with about $1.44 million of your own money after factoring in buyer's stamp duty (BSD) and a $1.33 million loan, and its value later rises by 10%.
The home would be worth about $276,000 more, and that capital increase goes to you, while the amount you borrowed stays the same. The same works in reverse, though, as a fall in prices would also hit the value of the home.
A five-room flat in your estate costs about $1.45 million
Bedok South Horizon recorded its first resale transactions in April 2026, and from then until the end of October, there were 16 five-room flats that changed hands, with prices ranging from $1.265 million to $1.54 million. The average resale price was about $1.4 million.
We've highlighted the three most recent resale transactions in the table below, and they involved units of 1,216 sq ft, yet their prices differed by as much as $288,000.
| Selected 5-room resale transactions | Floor band | Resale price | BSD | Total including BSD | Balance from your $1.546m |
|---|---|---|---|---|---|
| Blk 153B, Oct 2026 | 4 to 6 | $1,300,000 | $36,600 | $1,336,600 | $209,400 left |
| Blk 152C, Nov 2026 | 7 to 9 | $1,410,000 | $41,000 | $1,451,000 | $95,000 left |
| Blk 152B, Nov 2026 | 16 to 18 | $1,588,000 | $49,000 | $1,637,000 | $91,000 shortfall |
The balance combines cash and CPF, before selling expenses, legal fees and renovation. The $1.588 million transaction was a record for Bedok at the time, coming a month after the town's earlier price high of $1.54 million, which also involved a resale flat at Bedok South Horizon.
Take the $1.41 million flat as an example. If you used all $976,000 in sale proceeds and the extra $100,000 in your CPF OA, you'd need another $375,000 to cover the price and BSD, which you could pay from the $470,000 in cash you've set aside and still have $95,000 left, with no mortgage at all.
Alternatively, you could borrow that $375,000 and keep your cash. At the same 4% rate over 25 years, the repayment would be about $1,980 a month, well below your $7,000 ceiling.
Price growth is harder to judge here. With resale transactions only starting in April 2026, the estate's short transaction record tells us what buyers are willing to pay today, but not what someone buying at $1.41 million might earn over time.
The five-room layout can stretch to a small fourth room
Besides the three bedrooms, the 1,216 sq ft floor plan shows a suggested study in a windowed corner of the living room. You could leave this corner open while your children are young, then wall it off as a study or small bedroom when someone needs more privacy, though doing so would narrow the living area.
[Insert both five-room floor plans: "Open Kitchen Concept (Default)" and "With Kitchen Partition Wall"]
For two children and a helper, that flexibility could matter greatly. If the children share a room, your helper could take the other common bedroom and the living room could stay open, and if each child eventually wants their own room, you could check whether the study corner would fit a bed and storage.
This gives you a simple way to judge the four-bedroom condos on your shortlist: how much more you'd pay for a proper fourth bedroom, and how much more usable space it gives you than this arrangement.
How much more would you pay for the condos on your shortlist?
In the tables below, the price premium that we have indicated is how much more you'd pay compared to the $1.41 million flat, which comes to about $1.45 million with BSD.
For the three-bedders at Tierra Vue and Cote D'Azur, the question we would ask ourselves is what the layout offers over the five-room flat. A bigger bedroom, a separate utility area or a better room for your helper could matter more to you than the overall floor area.
Cote D'Azur is especially useful for the four-bedders, because you're considering both bedroom types there, so we can see what the step from three to four bedrooms costs in the same location.
| Development | Tenure | Completion year | No. of residential units |
|---|---|---|---|
| Cote D'Azur | 99-year | 2004 | 612 |
| euHabitat | 99-year | 2015 | 748 |
| Grandeur Park Residences | 99-year | 2020 | 720 |
| Tierra Vue | Freehold | 2009 | 129 |
| Waterfront Gold | 99-year | 2014 | 362 |
| Waterfront Isle | 99-year | 2015 | 561 |
| Waterfront Key | 99-year | 2012 | 437 |
| Waterfront Waves | 99-year | 2011 | 405 |
Three-bedroom units
| Project | No. of transactions | Average size (sq ft) | Average resale price | Price incl. BSD | Premium over the 5-room flat |
|---|---|---|---|---|---|
| Cote D'Azur | 11 | 1,440 | $2,795,818 | $2,905,209 | $1,454,209 |
| Tierra Vue* | 2 | 1,243 | $2,802,944 | $2,912,691 | $1,461,691 |
The three-bedders at Cote D'Azur and Tierra Vue both fetched average prices of around $2.8 million, roughly $1.46 million more than the average price of a five-room flat after accounting for BSD. Both price averages are slightly above your budget of $2.872 million, including BSD, by about $33,000 at Cote D'Azur and $41,000 at Tierra Vue.
On average, Cote D'Azur's three-bedders were 224 sq ft larger than the subject flat and 197 sq ft larger than the units sold at Tierra Vue. However, its average resale price includes the sale of two much bigger units of 1,862 and 2,207 sq ft.
The other nine three-bedders that were sold at Cote D'Azur ranged from 1,281 to 1,367 sq ft and fetched an average price of about $2.74 million, which comes to about $2.85 million, just within your budget. In a typical layout, then, the units at Cote D'Azur give you about 65 sq ft more than the units at Tierra Vue for a slightly lower price.
Tierra Vue's main appeal is its freehold tenure, while Cote D'Azur's 99-year lease started in 2001. That may matter if you plan to stay for many years.
But at 1,243 sq ft, Tierra Vue's three-bedders are only about 27 sq ft bigger than the five-room flat, which also has a study corner that can become a small fourth room. So the $1.46 million premium would mostly pay for the freehold tenure and the location, instead of more space for your family.
At Tierra Vue, you'd also have fewer recent resale transactions to check an asking price against. At the 612-unit Cote D'Azur, eleven three-bedders sold in 2026, while at the 129-unit Tierra Vue we only have two resale transactions from 2025.
This is fairly typical of a small freehold development, where owners tend to hold on for longer. From 2022 to October 2026, about 2.4% of Tierra Vue's units changed hands each year, a little lower than the 3.1% at Cote D'Azur.
Four-bedroom units
| Project | No. of transactions | Average size (sq ft) | Average resale price | Price incl. BSD | Premium over the 5-room flat |
|---|---|---|---|---|---|
| euHabitat | 2 | 1,302 | $2,127,500 | $2,203,475 | $752,475 |
| Grandeur Park Residences | 1 | 1,130 | $2,380,000 | $2,468,600 | $1,017,600 |
| Waterfront Key* | 5 | 1,488 | $2,645,600 | $2,747,480 | $1,296,480 |
| Waterfront Isle | 1 | 1,378 | $2,710,000 | $2,815,100 | $1,364,100 |
| Cote D'Azur | 6 | 1,545 | $2,885,633 | $2,999,515 | $1,548,515 |
| Tierra Vue | 2 | 2,061 | $3,779,000 | $3,945,340 | $2,494,340 |
| Waterfront Waves | 1 | 2,992 | $5,000,000 | $5,239,600 | $3,788,600 |
Four of the four-bedroom transactions sold for less than the cost of the three-bedders at Cote D'Azur and Tierra Vue. Specifically, euHabitat had the smallest price premium of about $752,000 over the HDB flat, for a home that had an average of 86 sq ft more space.
At Grandeur Park Residences, the only four-bedder sold this year was a 1,130 sq ft unit - it's 86 sq ft smaller than the flat. So you'd pay about $1.02 million more than for the flat to get a fourth bedroom, but with less space overall, which means smaller rooms or a smaller living area.
Waterfront Key stands out if you want both a fourth bedroom and more space overall. Its four-bedders have an average size of 1,488 sq ft, which is 272 sq ft more than the flat. Based on five resale transactions in 2025, they cost about $158,000 less, including BSD, than the average three-bedder at Cote D'Azur in 2026.
But resale prices at Waterfront Key have since increased. A 1,518 sq ft unit - the same size as three of the units sold in 2025 - transacted for $2.85 million in August 2026, or about $2.96 million with BSD, around $90,000 above your 25-year budget but within the 30-year one.
Waterfront Isle's only resale transaction this year also falls within your budget, though one transaction isn't much to go on.
At Cote D'Azur, the four-bedders command about $94,000 more, including BSD, compared to the resale price its three-bedders can fetch. This gets you about 105 sq ft more space on average. If we use the nine typical three-bedders, the step up in price is closer to $148,000.
The total comes to just under $3 million, around $128,000 above your 25-year budget, though a 30-year loan would cover it at the same $7,000 a month.
The four-bedroom resale transactions at Tierra Vue and Waterfront Waves were much larger homes. The only one at Waterfront Waves was a 2,992 sq ft penthouse, which tells us little about what a regular four-bedder there would cost.
Which condos come closest to your desire for convenience?
We've looked at the school and MRT journeys separately, since a development can put you minutes from the train but leave you with a much longer school run.
| Development | Walk to MRT | Walk to a nearby primary school |
|---|---|---|
| Cote D'Azur | Marine Parade, 8 mins | Tanjong Katong Primary, 11 mins |
| euHabitat | Eunos, 13 mins | Telok Kurau Primary, 9 mins |
| Grandeur Park Residences | Tanah Merah, 4 mins | Bedok Green Primary, 15 mins |
| Tierra Vue | Marine Terrace, 2 mins | Tao Nan School, 4 mins, or Ngee Ann Primary, 7 mins |
| Waterfront Gold | Bedok Reservoir, 9 mins | Yu Neng Primary, 8 mins, or Red Swastika School, 11 mins |
| Waterfront Isle | Bedok Reservoir, 13 mins | Yu Neng Primary, 10 mins |
| Waterfront Key | Bedok Reservoir, 6 mins | Red Swastika School, 10 mins, or Yu Neng Primary, 12 mins |
| Waterfront Waves | Bedok Reservoir, 8 mins | Yu Neng Primary, 6 mins, or Red Swastika School, 9 mins |
Walking times are estimates based on OneMap routes and can vary with the block and gate you use.
Tierra Vue comes closest to having both an MRT station and a primary school on the doorstep. At Cote D'Azur, where three-bedders cost about the same, the walks stretch to eight minutes to the MRT and 11 minutes to school.
Among the four-bedroom options, Waterfront Key offers the best mix of space and convenience, with an estimated six-minute walk to Bedok Reservoir MRT and 10 minutes to Red Swastika School. Waterfront Isle uses the same station and has a similar school walk, but its MRT walk is about seven minutes longer each way.
Of the two cheapest four-bedroom options, euHabitat is closer to a primary school, while Grandeur Park Residences is closer to an MRT station.
Based on four-bedroom prices in 2026, choosing Grandeur Park over euHabitat would cost you about $265,000 more including BSD. Your walk to the MRT would drop from 13 minutes to four, but your walk to school would go up from nine minutes to 15.
If a closer school distance matters most to you, paying more for Grandeur Park's shorter MRT walk may do less for your daily routine.
How have the condos on your shortlist performed?
Part of the appeal of upgrading after MOP is putting your BTO gains into a home that could grow in value. The table below tracks the average $PSF across sub-sale and resale transactions at each development from 2016 to November 2026, alongside the islandwide average for non-landed private resale homes.
| Year | Cote D'Azur | euHabitat | Grandeur Park Residences* | Tierra Vue | Waterfront Gold | Waterfront Isle | Waterfront Key | Waterfront Waves | All non-landed private property (resale only) |
|---|---|---|---|---|---|---|---|---|---|
| 2016 | $1,221 | $1,154 | - | $1,333 | $1,125 | $1,128 | $1,078 | $1,044 | $1,248 |
| 2017 | $1,235 | $1,175 | - | $1,360 | $1,159 | $1,145 | $1,048 | $1,045 | $1,292 |
| 2018 | $1,253 | $1,203 | - | - | $1,188 | $1,175 | $1,166 | $1,136 | $1,322 |
| 2019 | $1,207 | $1,132 | $1,561 | $1,569 | $1,207 | $1,185 | $1,181 | $1,060 | $1,345 |
| 2020 | $1,385 | $1,158 | $1,422 | $1,795 | $1,192 | $1,212 | $1,152 | $1,110 | $1,279 |
| 2021 | $1,445 | $1,189 | $1,588 | $1,561 | $1,237 | $1,228 | $1,185 | $1,140 | $1,354 |
| 2022 | $1,595 | $1,284 | $1,688 | $1,884 | $1,373 | $1,304 | $1,359 | $1,260 | $1,473 |
| 2023 | $1,761 | $1,358 | $1,847 | $1,863 | $1,501 | $1,502 | $1,515 | $1,445 | $1,595 |
| 2024 | $1,838 | $1,391 | $1,909 | $1,894 | $1,571 | $1,572 | $1,659 | $1,532 | $1,681 |
| 2025 | $1,869 | $1,405 | $1,987 | $2,000 | $1,639 | $1,609 | $1,745 | $1,630 | $1,755 |
| 2026 (Up to Nov) | $1,901 | $1,408 | $2,016 | $1,919 | $1,694 | $1,701 | $1,796 | $1,644 | $1,797 |
| Annualised | 4.53% | 2.01% | 3.72% | 3.71% | 4.18% | 4.19% | 5.24% | 4.65% | 3.71% |
Annualised growth is from 2016 to 2026 to date, except for Grandeur Park Residences (*), where it runs from 2019.
The mix of units sold can shift the average price in any year, especially at Tierra Vue, which recorded only two to five transactions a year from 2022.
Among the four-bedders, euHabitat has the lowest average price and the slowest resale growth rate at 2.01% a year, while resale prices at Waterfront Key grew the fastest of the projects with a full ten-year record, at 5.24% a year.
Waterfront Gold, Waterfront Isle, Waterfront Key, and Waterfront Waves saw their resale prices grow faster than the islandwide average. Waterfront Key also has more recent resale transactions of the unit size that you're looking for.
Among the three-bedders, Cote D'Azur recorded the fastest growth at 4.53% a year, even though it's the older, leasehold development. Meanwhile, Tierra Vue's price growth of 3.71% matched the islandwide average.
Grandeur Park only launched for sale in 2017, so its first sub-sales were recorded in 2019, and we compared it with the islandwide average from that year. It grew at a yearly rate of 3.72%, a little behind the wider market's increase of 4.22%.
Across the shortlist, Waterfront Key is where past growth, space and location line up most closely with your priorities, provided you can buy near its 2025 prices.
These are past figures, and part of the growth came from the price surge during the COVID years, with no guarantee it continues at the same pace. If prices grow more slowly from here, you'd be paying for a condo more for the extra bedroom and shorter walks than for capital gains.
So, which home suits your family?
The five-room flat lets you stay near the school, the new MRT station and your parents, and at about $1.45 million with BSD, it leaves you the choice of buying without a mortgage or keeping your $470,000 in cash. Its study corner can become a small fourth room when you need one.
A suitable condo four-bedder gives each child and your helper their own room with the living area intact, but on your shortlist it costs about $750,000 to $1.55 million more than the flat, and the pricier options take your repayment up to your $7,000 ceiling.
The bigger loan has its own upside. Even if both homes stayed at their purchase prices, you'd own a more valuable property once the condo loan was paid off, and if you later moved to a cheaper home, the difference could go towards retirement, after the loan, transaction costs and CPF refunds.
The HDB flat can grow your wealth too. If you regularly invest your spare cash and the money you save each month, you could build a retirement fund you can use without selling your home.
The main difference is timing. The flat gives you more financial freedom while your children are young, and a condo asks for a bigger commitment during your working years in return for more money tied up in your home by retirement.
0 Comments