


A growing number of young Singaporeans are keen to move out of their family homes and into their own place, but also don't want to feel rushed into a marriage.
But as our latest case study illustrates, these singles on a budget looking to buy their own homes need to be a little more patient compared to those purchasing homes as a couple.
Prevailing HDB regulations mean that single adult Singaporeans can only buy a resale flat when they turn 35. Anecdotally, it's become a significant milestone for these singles since it means that they're finally able to apply for their HDB Flat Eligibility (HFE) to start the process of owning their first home.
This was the case faced by a recent client of Royston Choy, one of the property agents under the Stacked Consultancy Team. This buyer applied for his HFE the moment the clock struck 00:00 on his 35th birthday last November.
Choy recalls how he received an enthusiastic message shortly after: "In his message, (this buyer) wrote to me saying, 'Royston, I'm ready to buy my own house'."
The eager client works in the fitness industry and had been living with his parents in their Yew Tee flat all his life. He first got in touch with Choy about his home buying plans when he was 33 years old, in order to lay the financial groundwork needed to buy his first home.
But when the buyer received his HFE - which detailed the types of flats that he was eligible to purchase, the grants he would receive and his final HDB loan amount - Choy knew it was going to be a tough search.
"I quickly realised that it would be an uphill battle for us to find the right property that matched his budget. I didn't want to dash his hopes and did my best to lay it out realistically," he says, adding that it would be tough but not impossible.
Working back from the financing
Since the buyer had a monthly income of about $3,000, it was clear that they'd have to work within his Mortgage Servicing Ratio (MSR) as a starting point. This is a different approach compared to couples or families, who tend to consider their home size requirements and lifestyle needs before exploring what prices are like on the market.
In this case, the buyer's income would be the starting point. Based on prevailing MSR regulations, he would also likely only be eligible for a Loan-To-Value (LTV) rate of less than 75%.
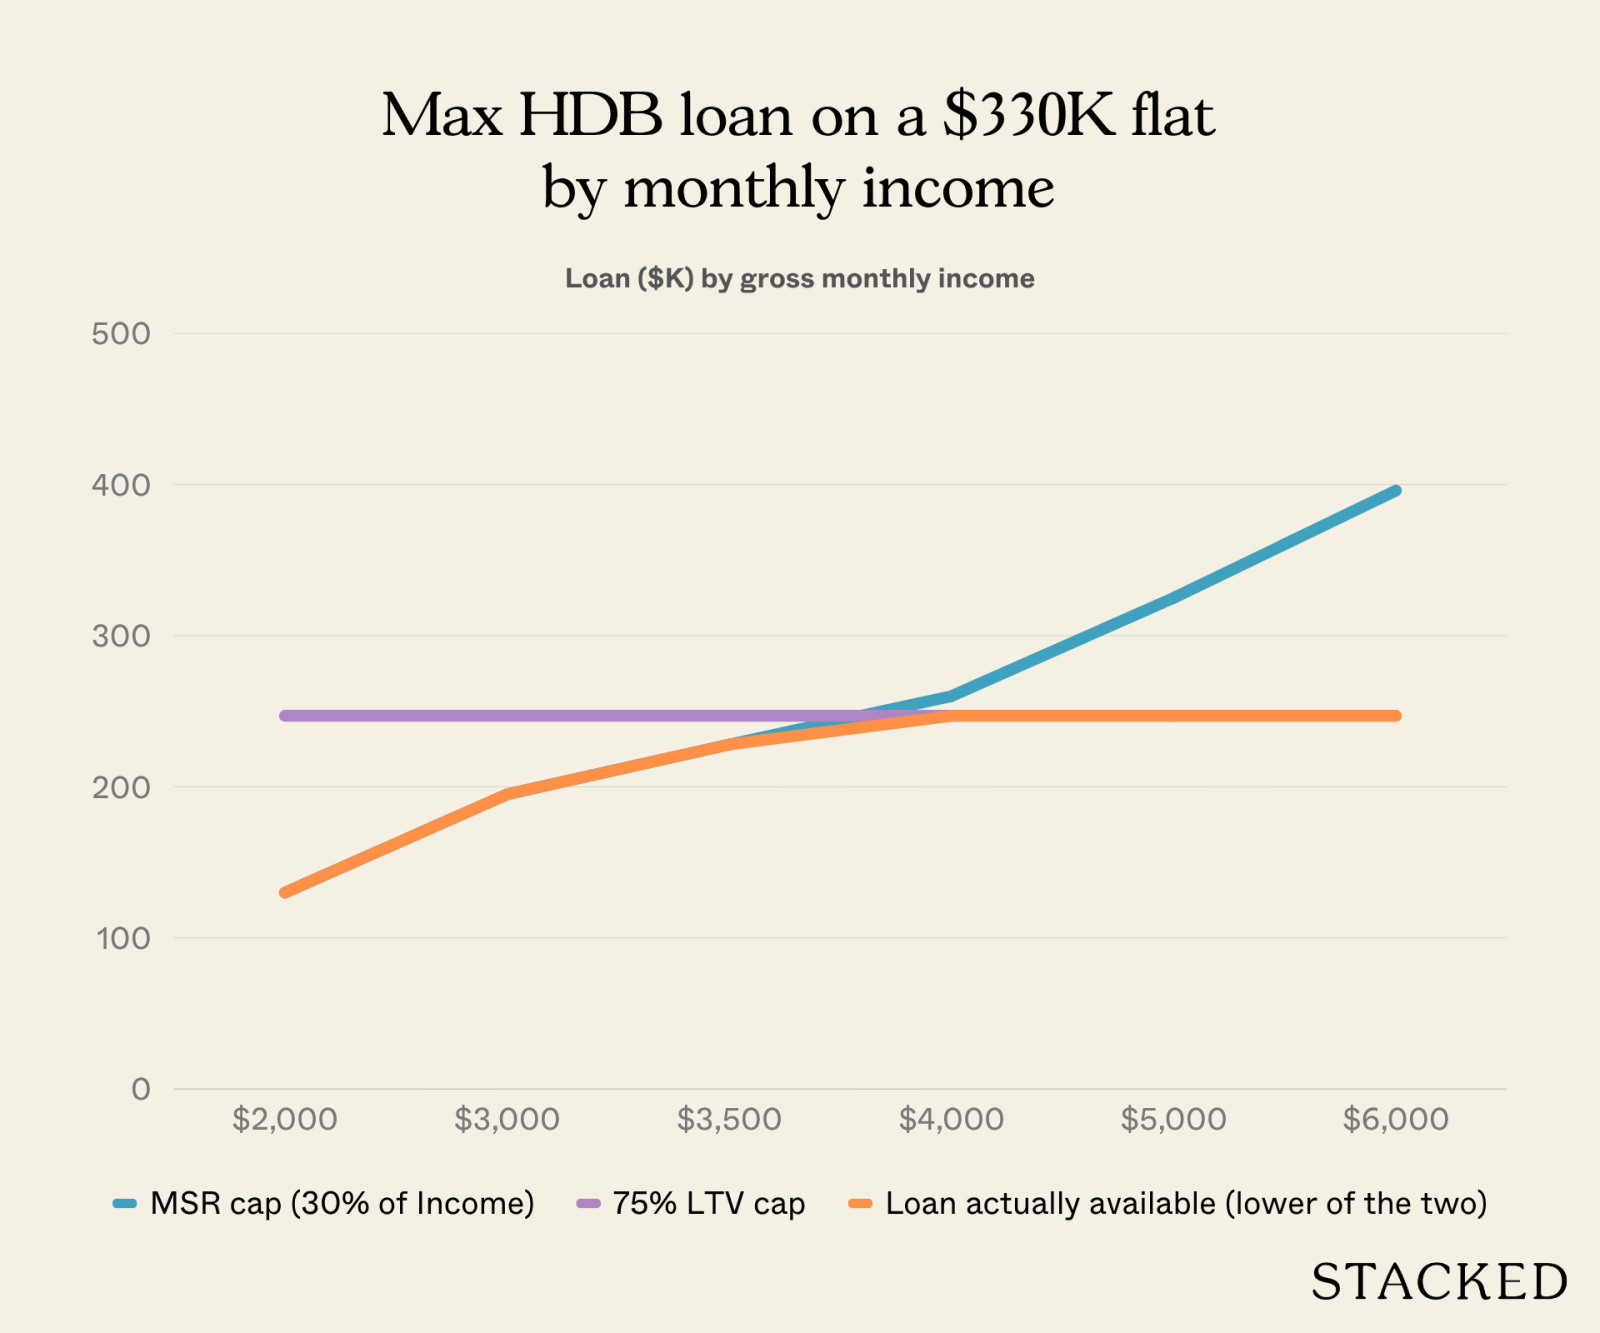
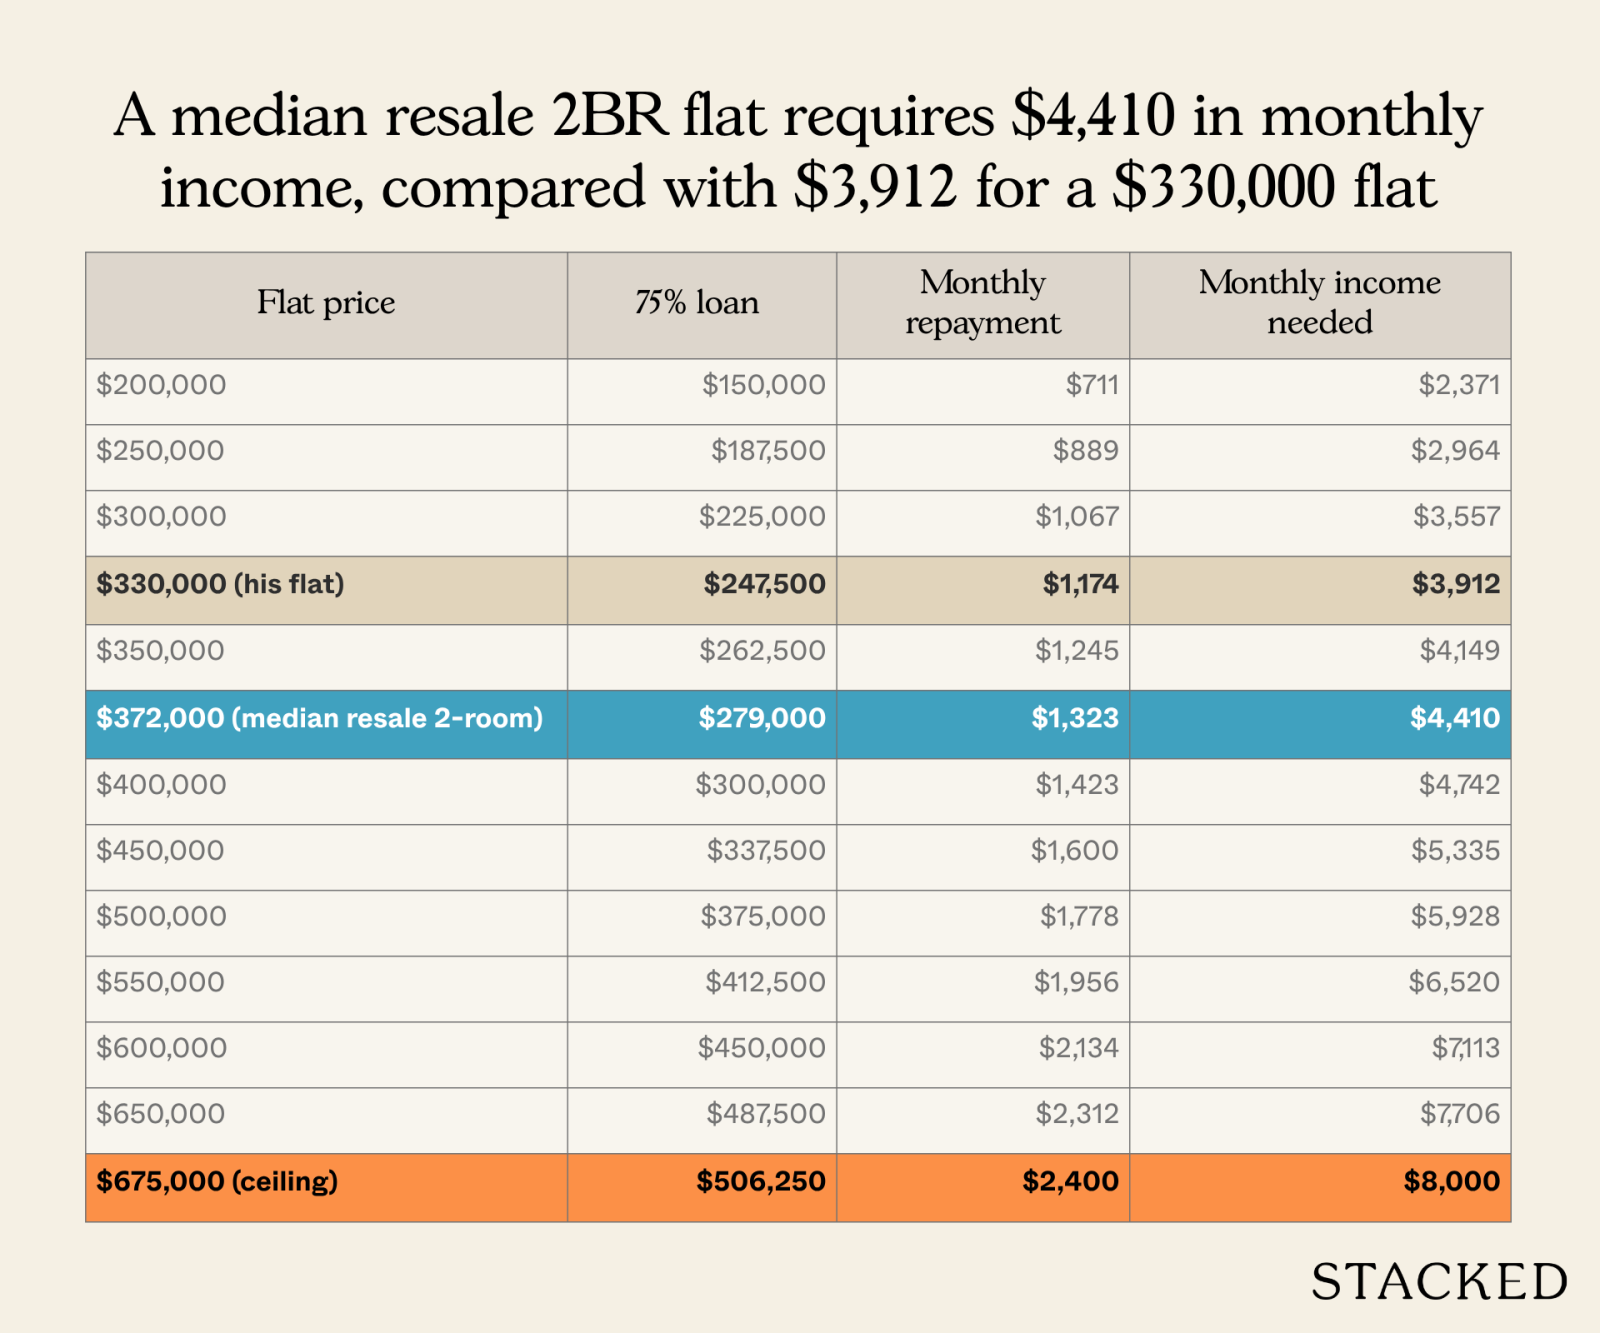
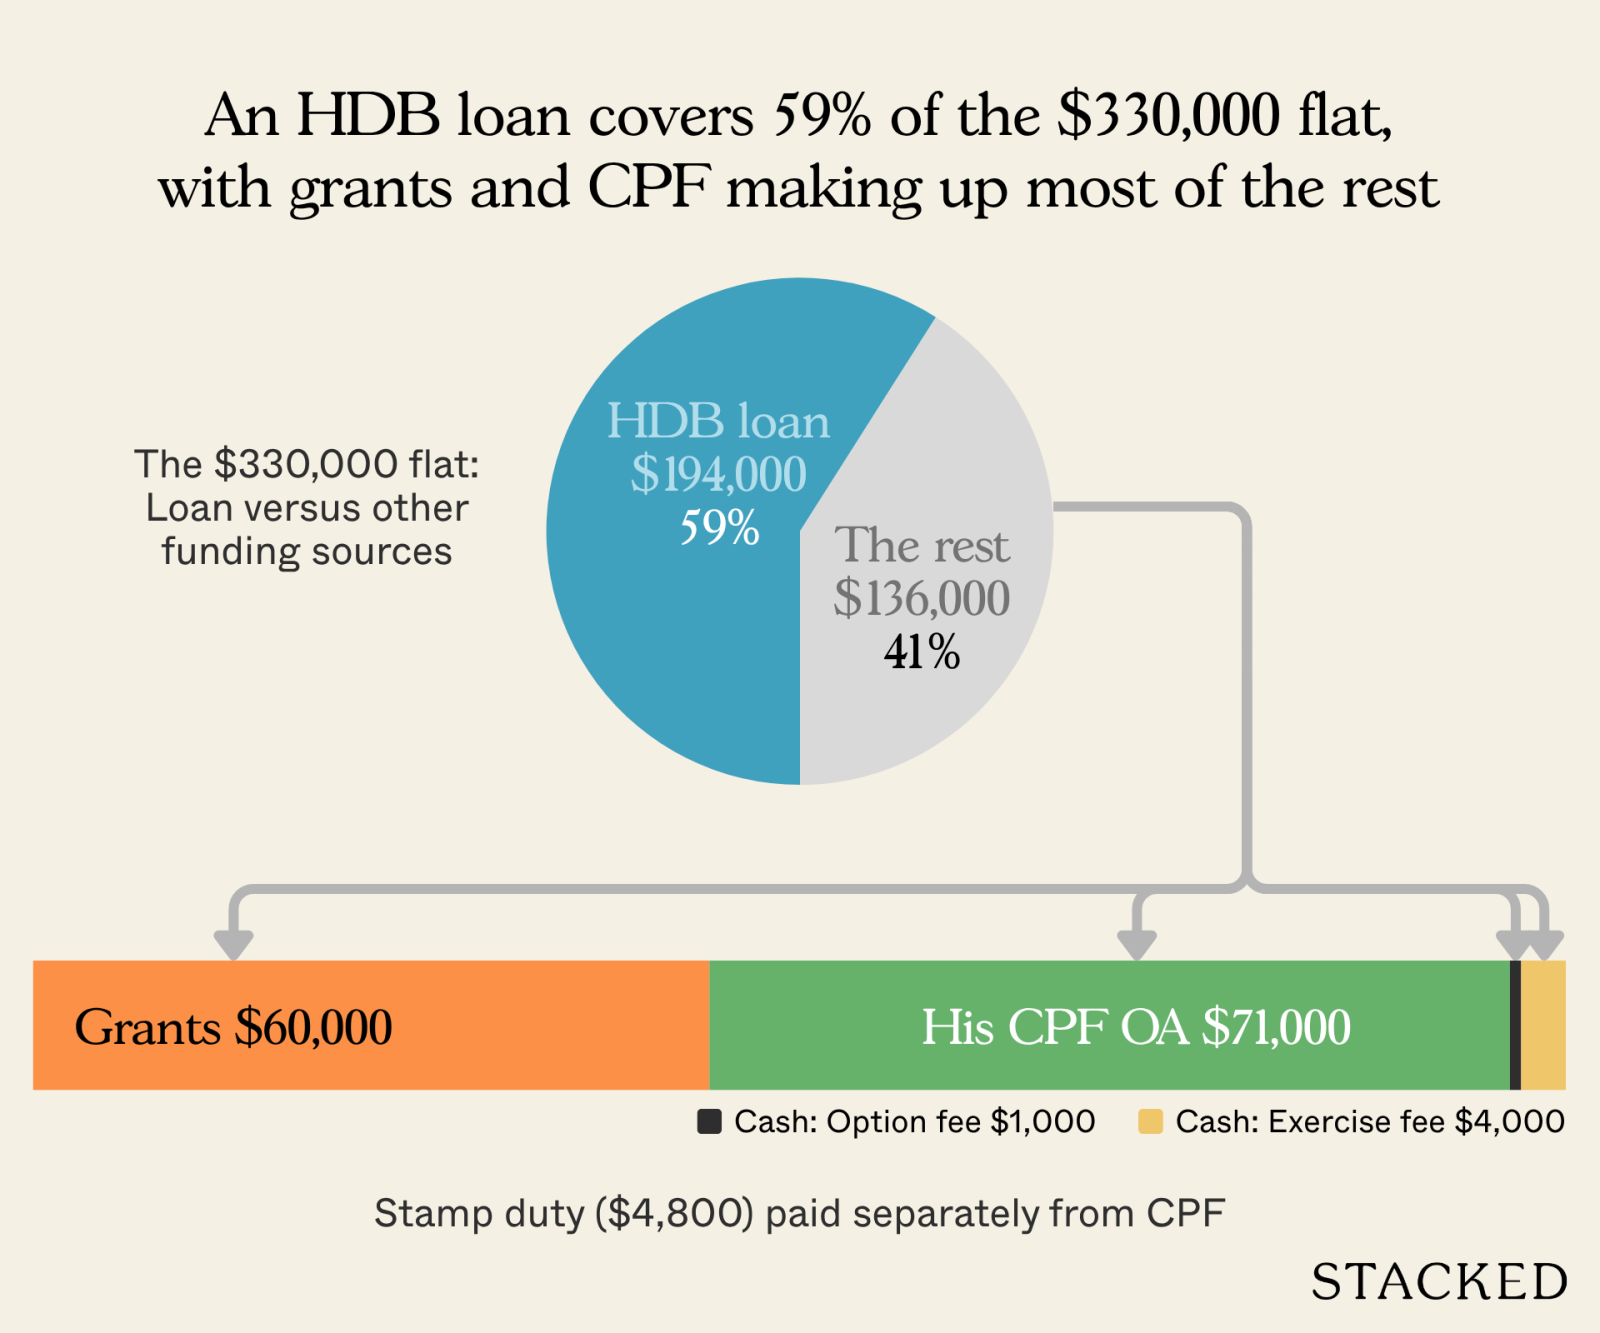
Based on the buyer's approximate monthly income, his maximum monthly loan repayments would be $900 a month, at a 3% interest rate over 25 years. In his HFE letter, HDB worked that out to be a total loan of about $194,000.
Combined with $60,000 in grants and $90,000 in his CPF Ordinary Account (OA), he had a purchasing budget of $344,000 to work with. After stamp duty and fees, that left about $330,000 for them to find a suitable resale flat.
At that price, a loan of $194,000 would make up only about 59% of the purchase price. According to Choy, the buyer had about $10,000 in cash savings, but wanted to leave that untouched for renovations and other needs.
First, they eliminated applying for a BTO flat
Since the buyer was eager to find his own place, the option of waiting to successfully ballot for a BTO flat and then the three- to four-year wait for it to be completed was simply unpalatable.
They also couldn't be sure that his first few ballot attempts would be successful, and there was a chance that he would only get the keys to his first home after he turned 40 years old.
Although a BTO flat would have been more affordable for a buyer on a tight budget, Choy and the buyer decided that this still wasn't worth the wait and the risk. In this case, the buyer's desire to find his own place outweighed a potentially cheaper flat.
So they looked to the resale market, but even there, available units were scarce
It was a daunting task trying to find a resale two-room flat that could be bought for about $330,000. "Ideally, this buyer hoped to secure a three-room flat, but realistically his budget meant that a two-room flat was the option within reach," says Choy.
The budgeted amount of $330,000 was also about $42,000 less than the median resale price of $372,000 for a two-room flat, based on resale transactions lodged between Sept 2025 and Sept 2026.
There are also relatively few resale two-room flats on the market compared to other unit types, making it more difficult for buyers looking to find the right home.
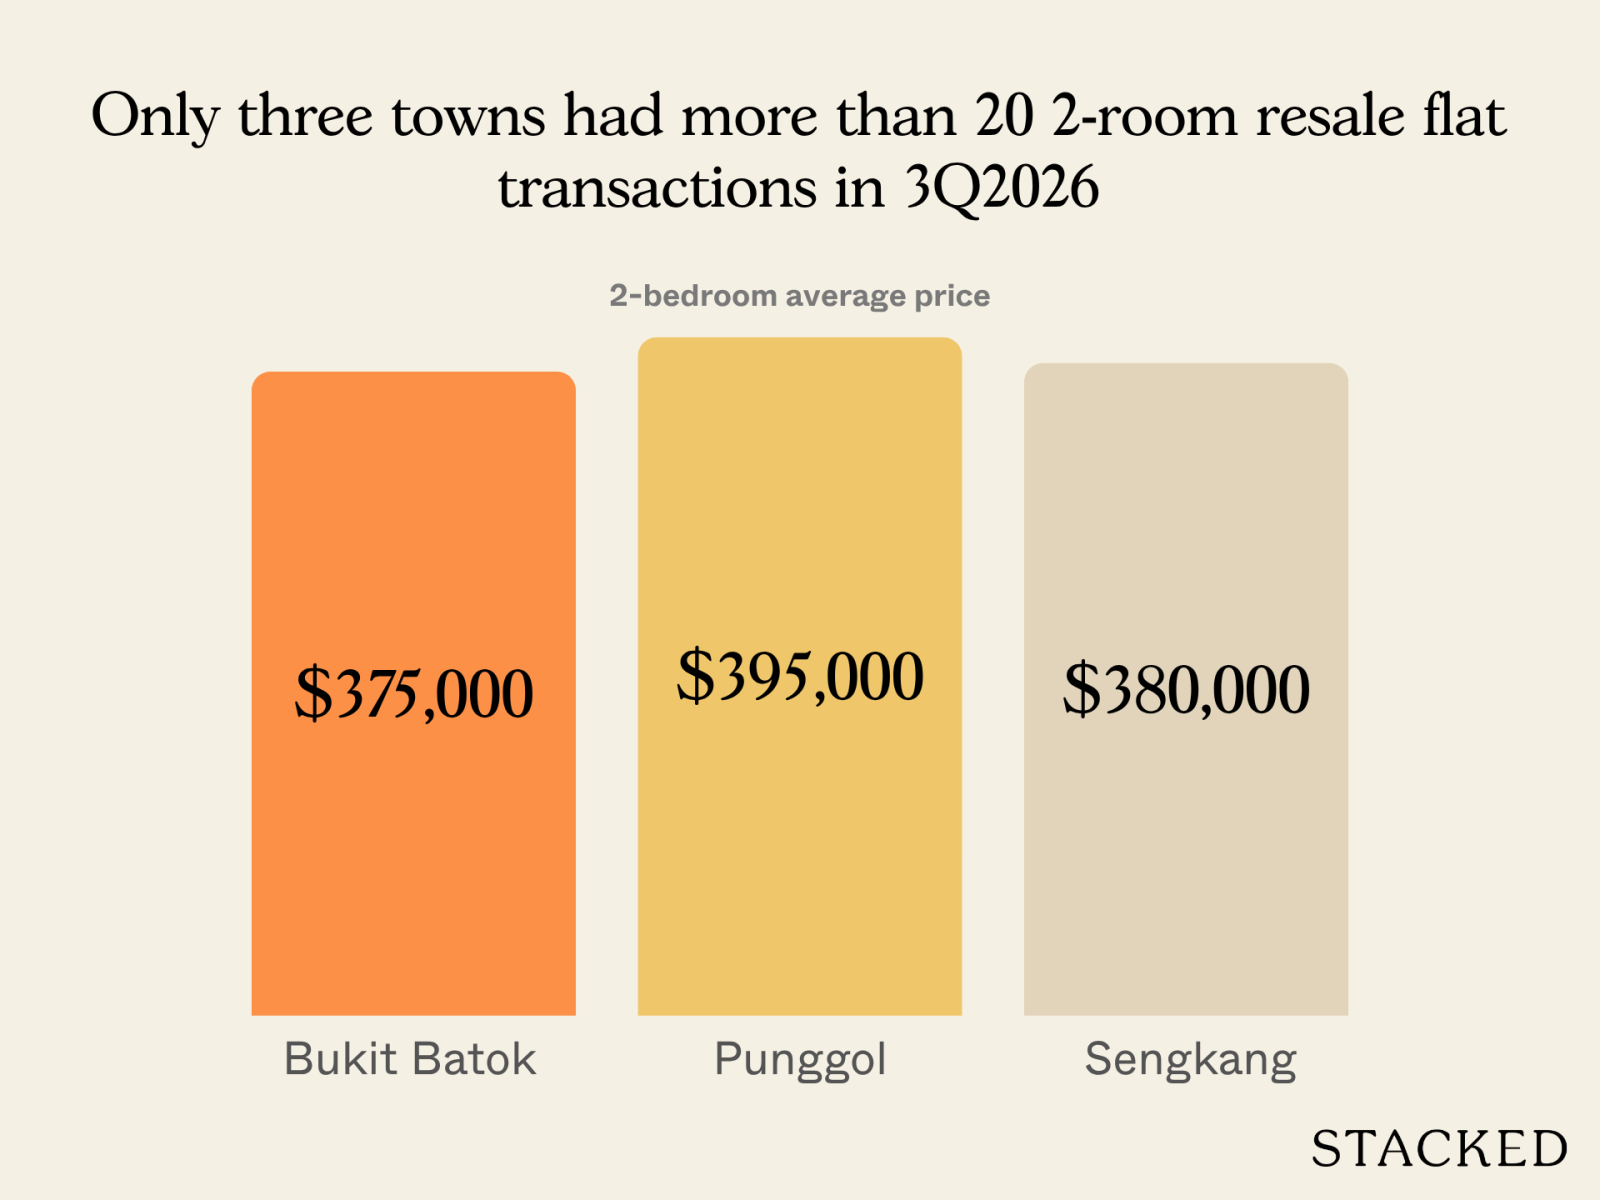
Based on 3Q2026 HDB resale data, the only towns which reported more than 20 two-room resale flat transactions last quarter were Bukit Batok, Punggol and Sengkang.
Even on listing platforms, very few listings for two-room flats turn up when the price is set at $330,000. A handful of listings appear when the asking price increases to $350,000 - but that meant negotiating with the seller, says Choy.
In cases like this, it is nearly impossible to search for a suitable listing based on the budgeted price, especially since most sellers will list an asking price that tends to be higher than market expectations, with the expectation that buyers will attempt to negotiate it down, he says.
This can be a very demoralising experience for the prospective buyer as well as the property agent.
In addition, Choy had calculated that the buyer could only afford an older resale flat in a less mature estate. But the buyer needed a flat with at least 60 years left on its lease in order to fully capitalise his available housing grants and CPF OA balance.
That meant crossing off any flat older than 1987.
For a single buyer who is 35 years old, flats with about 60 years left on their lease are often the sweet spot: the oldest, and usually cheapest, flats they can buy without HDB reducing their loan limit, grants and CPF use.
"Since he and his parents had been staying in Yew Tee for at least 30 years, this buyer resonated with some neighbourhoods in the West, such as Bukit Batok and Senja," says Choy.
However, there were no available resale listings for two-room flats in those areas going for $330,000. Increasing the budget to $360,000 garnered a handful more listings, but that exceeded the budget.
The buyer initially approached Choy two years ago
When the buyer was 33 years old, he and Choy had calculated that the budget was about $270,000 at that time. And it might have been easier to find a suitable flat for that price, since some were listed for $280,000.
Even then, there were signs that prices in the HDB resale market were on a relatively steep upward trajectory, and Choy was concerned that by the time this buyer turned 35 years old, he might not be able to afford a home on his own.
The resale HDB market did see a steady and consistent increase in prices over the next two years, and it became increasingly difficult to find any two-room flats going for less than $330,000.
Anecdotally, other aspiring single homebuyers have shared - in online forums and among casual conversations with friends - that they feel priced out of the public housing market due to rising home prices in previous years and moderate wage growth. Between 2020 and 2026, HDB resale prices rose about 54% while the median wage rose about 27% over the same period.
The search expanded to Fernvale and Hougang
Finally, Choy and the buyer decided to expand their search to other parts of Singapore, towards neighbourhoods in the Northeast area like Hougang and Fernvale.
They eventually came across a two-room flat in Buangkok that was listed for $350,000. After viewing the unit together, the buyer was pleased with the choice and gave the green light to Choy to start negotiating with the seller.
Choy was able to negotiate the price down to $330,000. "I was so thrilled and hurried to break the news to him," he recalls.
But at the very last minute, after the seller prepared the OTP and was waiting on the $1,000 deposit, the buyer backed out. It turned out that his mother had disapproved of the Buangkok location, which was too far from their family home in Yew Tee.
Although he was making a personal decision to find his own home, it appeared that several members of his family had reached out to him in an attempt to dissuade him from making this purchase, according to Choy. That became awkward when he had to break the news back to the sellers that the deal would not be going through.
They moved on to find homes in Sembawang and Yishun
As they continued their search for a more suitably located flat, Choy found another diamond in the rough: a two-room flat at 438 Yishun Ave 11 which was listed for $340,000. The property was about 17 years old with 82 years left on the lease.
Although Choy was unable to attend the first viewing with the buyer, he had a gut feeling that it could be just what he was looking for. To prepare the groundwork for a potential negotiation, he took it upon himself to do a bit of "soft negotiation" with the seller's agent over the phone before the viewing.
In the end, he was able to negotiate the Yishun flat down to $330,000 for the buyer, even before the first viewing. In this case, a discount was a necessity rather than a nice-to-have, because the buyer was just too tight on cash.
"All that was left was to get the green light from the buyer," says Choy.
The buyer did approve of the unit, and the OTP was filed in early 2026. The sale also did not result in any cash-over-valuation (COV). The buyer eventually got the keys to his first home and took over the flat in June 2026.
This was still a worthwhile experience for Choy, despite the hurdles
After all the back and forth, and the months-long process, Choy shares that his commission on this deal was only 1% of the purchase price, which works out to $3,300.
But he said that it wasn't about the money.
"There's a different type of satisfaction in this type of work. It is these first-time homeowners who are stuck between a rock and a hard place who need agents' support the most. These situations are also where an experienced negotiator, as well as industry connections, can make or break a deal," he says.
When he received the keys to his first home, the buyer sent a message to Choy thanking him for sticking with him and helping him to find his 'dream home'.
Key Takeaways
Price will always be the main constraint for buyers on a budget, but they should not lose sight of their non-negotiables.
In this case, the buyer might have been nervous about his options, agreeing to view flats in locations that his family might not support. But in the end, working with his property agent, he was able to find something that met those requirements and was still within his budget.
Being calm and clear-minded about those priorities from the start of the home buying journey could have saved a bit of trouble.
Choy also recommends that singles on a tight budget should apply for a HFE as soon as possible to find out their loan eligibility. In this case, the buyer’s loan came to $194,000, slightly more than the roughly $190,000 from working out 30% of his income.
HDB averages income and rounds in its own way, so the figure can differ. It's better to get clear on these numbers earlier than later, as for lower quantum purchases, a few thousand dollars can make a difference.
Finally, for some buyers, finding a resale option may be a better choice compared to a BTO option. A Standard two-room BTO flat can cost approximately $140,000 to $225,000, or about 30% to 60% less than some resale options.
But buyers have to account for the ballot process and relatively long construction times, which in some cases may see singles receiving their keys after they're 40 years old. This has a real impact on their future loan amount for their next property.
0 Comments