

Hi Stacked,
We’re a family of four with two children who are about 10 years old, and we’d like advice on buying our first home.
We currently live with my parents in a corner terrace in the East, which has about 70 years left on its lease. But we would like a place of our own that is close to the schools we hope to enroll our children into. We hope to register them at a school in the Dover Road area in about three years.
Which is why we are considering a 1,001 sq ft three-bedroom unit at Alessandrea. We have also looked at condos in District 15, but the three-bedders that we find the most appealing seem to be beyond our budget. Neither of us has bought a property before.
Here’s a summary of our financial position:
- Combined monthly household income: $20,000
- Combined CPF savings: $700,000
- Cash savings: $500,000
When it comes to the Alessandrea, we wonder if 1,001 sq ft will be sufficient for a family of four as our children grow older? Overall, the unit we have shortlisted has a good layout, but we are unsure whether we should prioritise a larger home.
Do freehold condos like Alessandrea offer better long-term appreciation compared to 99-year leasehold alternatives? The condo is also next to Alexandra Peaks, an upcoming BTO development, might this affect the condo’s future value?
How does the monthly maintenance fee of about $400 compare against comparable developments? We feel this amount is rather steep.
Alternatively, would it make sense to buy now and rent out the unit for the next three years, then move in when our children start attending school? Or, would we be better off buying a larger unit a little farther from the schools?
Thank you, and we would appreciate your recommendations.
Hi, and thanks for writing in!
District 15 is indeed a challenging housing market for many buyers, so we can understand why you have decided to look further afield for your first home as a family. You also shared that a priority is being close to the schools that you expect to register your children at in a few years' time, as well as a desire to have a more spacious home.
In light of that, we think that the unit at Alessandrea which you have shortlisted does appear to be a sensible move from your current residence, at least on the surface.
We’ll take a closer look at your situation, but in the meantime let’s kick things off by focusing on the price range. This will help us consider whether Alessandrea - or a larger family home elsewhere - will fit your family needs.
The challenge for many buyers today isn't access to information.
It's interpreting that information in a way that makes sense for their finances, goals, and stage of life.
Over time, that's also why we decided to work with agents who shared the same data-driven and advisory-led approach behind our editorial, consultants who could help readers think through decisions more objectively, rather than simply push transactions.
Today, the team has worked with more than 2,000 clients across over $5B in property transactions.
How Much Should You Comfortably Spend On Your Property Purchase?
| Maximum loan based on monthly combined income of $20K and 20-year tenure at 4% interest | $1,815,240 |
| CPF | $700,000 |
| Cash | $500,000 |
| Total funds | $3,015,240 |
| BSD based on $3,015,240 | $120,514 |
| Estimated affordability | $2,894,726 |
*Note: the actual home loan interest rate is likely to be lower than 4%, but we use 4% because this is the floor rate set by MAS. It’s also the rate used by the bank to calculate thresholds like the Total Debt Servicing Ratio (TDSR). In any case, there’s no harm in being conservative and simulating a higher rate, just in case interest rates rise in future!
Based on our estimations, the maximum loan you could get is approximately $1.815 million, assuming no other debt obligations. Together with your stated CPF and cash savings, this gives you a theoretical limit of around $2.9 million after accounting for Buyer’s Stamp Duty (BSD).
But this is your ceiling and not necessarily a comfortable spending target. It also implies monthly repayments of approximately $11,000, before maintenance fees, property tax and other household expenses - which you may find to be higher than you’d like.
Based on your age of 45 years old, a 20-year loan would take you to around retirement age. It’s therefore worth considering how much you can comfortably repay, while continuing to save for retirement and provide for your two growing children.
Unfortunately, we can only give you a general perspective on this, as our field is property and not personal finance. But we will say that, to set a purchase budget, we would first ring-fence an emergency reserve*, renovation and furnishing costs, and funds for your children’s needs.
*Usually - but not always - defined as being sufficient to service the mortgage for at least six months in a crisis.
From there, work out a monthly repayment you can sustain without putting your other savings plans on hold. This will give you a more useful budget for comparing the shortlisted unit at Alessandrea to larger-sized alternatives.
Next, we’ll assess how Alessandrea has performed over the years
As the saying goes, past performance doesn’t reliably reflect future performance, but it can frame your price and profitability expectations if you do buy that unit at Alessandrea.
| Year | Alessandrea | D3 non-landed private properties (resale) | All non-landed private properties (resale) |
| 2015 | $1,398 | $1,296 | $1,197 |
| 2016 | $1,287 | $1,255 | $1,248 |
| 2017 | $1,193 | $1,346 | $1,293 |
| 2018 | $1,392 | $1,669 | $1,323 |
| 2019 | $1,389 | $1,631 | $1,346 |
| 2020 | $1,494 | $1,627 | $1,280 |
| 2021 | $1,550 | $1,672 | $1,354 |
| 2022 | $1,624 | $1,920 | $1,473 |
| 2023 | $1,647 | $2,023 | $1,595 |
| 2024 | $1,885 | $2,125 | $1,681 |
| 2025 | $1,931 | $2,192 | $1,755 |
| 2026 (Up to June) | $2,025 | $2,254 | $1,799 |
| Annualised | 3.43% | 5.16% | 3.78% |
Based on the transaction data compiled by Stacked, taking into account caveats lodged between 2015 and June 2026, the average price growth at Alessandrea has kept pace with the islandwide average resale price trajectory. The difference is a bit lower but negligible in our view, at less than one percentage point.
On the other hand, the price growth at Alessandrea is much lower compared to the average price growth recorded in District 3 over the same period. But this is due to an odd quirk that took place between 2017 and 2018, when resale prices shot up from $1,346 psf to $1,669 psf within a single year.
We can’t definitively say why this happened in District 3, but one possible reason was a rush to beat the ABSD deadline, which took effect on 6 July 2018, and hit the new launch projects at the time.
In District 3, this impacted the sales launch of Stirling Residences, and could have set a new price benchmark that then had a knock-on effect on existing resale prices. In any case, this is likely to have been a one-off factor.
Meanwhile, resale private home prices in District 3 have strengthened in recent years, particularly from 2024 onwards. Alessandrea has gained from the market’s upswing despite its age, and doesn’t seem to have been left behind.
Does Alessandrea’s Freehold Status Support Its Price Appreciation?
In general, a condo’s freehold tenure should help its units to overcome some of the negative impacts as the development ages. So, let’s take a look:
| Year | All 99-year leasehold non-landed private properties (resale) | All 999-year/freehold non-landed private properties (resale) |
| 2015 | $1,051 | $1,366 |
| 2016 | $1,140 | $1,393 |
| 2017 | $1,123 | $1,461 |
| 2018 | $1,164 | $1,524 |
| 2019 | $1,189 | $1,572 |
| 2020 | $1,159 | $1,488 |
| 2021 | $1,227 | $1,586 |
| 2022 | $1,370 | $1,709 |
| 2023 | $1,516 | $1,799 |
| 2024 | $1,616 | $1,856 |
| 2025 | $1,683 | $1,938 |
| 2026 (Up to June) | $1,722 | $1,985 |
| Annualised | 4.59% | 3.46% |
| Year | D3 99-year leasehold non-landed private properties (resale) | D3 999-year/freehold non-landed private properties (resale) |
| 2015 | $1,263 | $1,407 |
| 2016 | $1,217 | $1,329 |
| 2017 | $1,346 | $1,368 |
| 2018 | $1,697 | $1,491 |
| 2019 | $1,653 | $1,517 |
| 2020 | $1,641 | $1,536 |
| 2021 | $1,697 | $1,513 |
| 2022 | $1,917 | $1,941 |
| 2023 | $2,050 | $1,784 |
| 2024 | $2,137 | $1,908 |
| 2025 | $2,206 | $1,984 |
| 2026 (Up to June) | $2,281 | $1,977 |
| Annualised | 5.52% | 3.14% |
According to what we can see from the data, it is not unusual - in terms of percentage change - that 99-year leasehold properties seem to have recorded a relatively higher price appreciation. We’ve argued that this is because these projects tend to start off at a relatively lower selling price compared to freehold counterparts in the area.
But at a rate of 3.43%, the price appreciation at Alessandrea is broadly on par with the Singapore-wide average. Thus, although its freehold status hasn’t made it an outperformer, it may have helped to ensure Alessandrea’s continued price resilience.
Could Upcoming BTO Projects in the vicinity affect the future price growth of Alessandrea?
Alessandrea is opposite the 498-unit Alexandra Peaks, a Prime-type BTO project that was launched during the July 2025 BTO sales exercise. When it is completed in 2029, the development will also feature a new eating house, shops, a minimart, and a preschool to serve families in the area.
These amenities could also benefit the residents of Alessandrea. But a crucial detail is that its completion time overlaps with your intended move-in date, which revolves around the time your children start primary school.
This is also where we need to point out a change in the perspective of some homeowners - regarding being near HDB enclaves - over the past decade. Previously, private home owners preferred to be away from public housing estates. But this perspective has shifted in recent years, and being near a HDB cluster is often seen as an advantage.
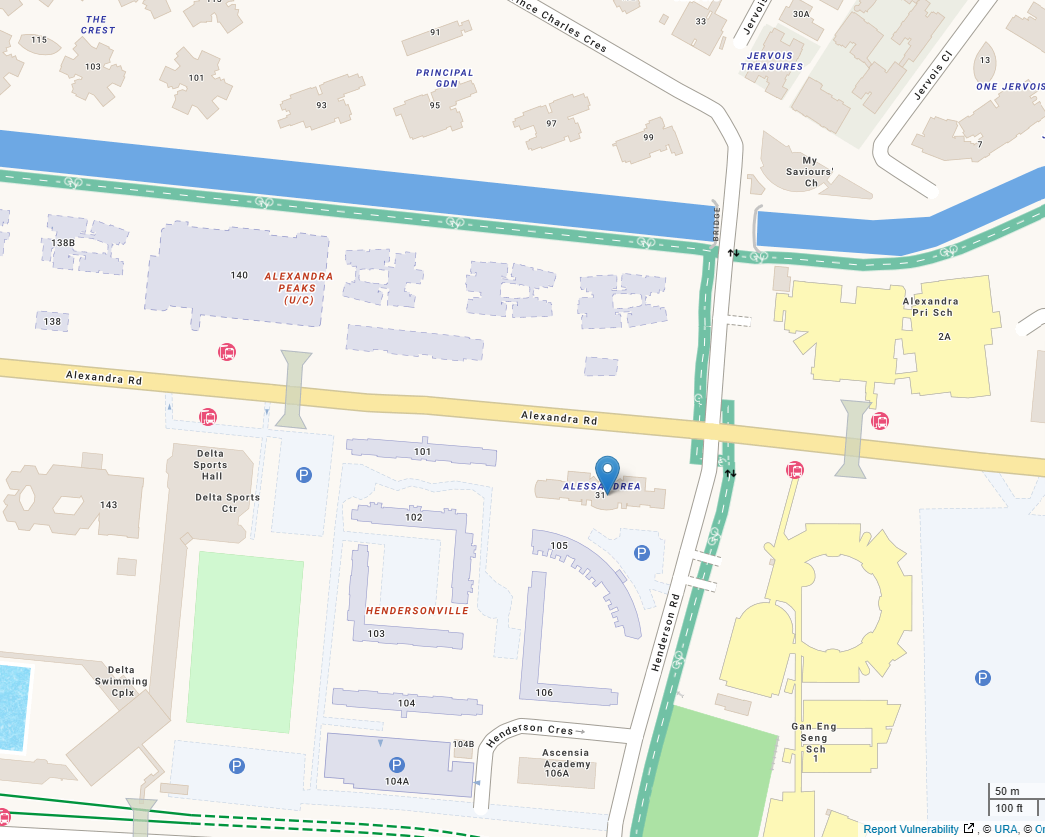
We reckon that this shift in preference is supported by the fact that a growing number of resale condo buyers are HDB upgraders, and most prefer to stay in familiar surroundings even after they upgrade.
Increasingly, we see that HDB estates tend to contribute significantly to the pool of prospective resale private home buyers. But that being said, we need to keep in mind Alexandra Peaks is a Prime HDB project with a 10-year MOP, so this only becomes relevant after around 2034.
In the meantime, construction noise and dust could affect the immediate surroundings.
If you remain at your parents’ home for the next three years, this won’t matter to you. But if you choose to rent out the unit, prospective tenants may be more sensitive to the disruption.
This brings us to your next question:
Should You Buy Now and Rent Out The Unit, Until You’re Ready To Move In?
On the face of it, this seems like it could be more financially beneficial, assuming the numbers work out after accounting for other expenses like maintenance fees, property tax, and agent fees.
As an aside, we’re not too surprised by a $400 per month maintenance fee for a three-bedder. You will likely find that the average fee is between $300 to $400 in many condos, for units of this size. Maintenance goes by share value, and it’s typically about $75 to $80 per share value.
Construction at Alexandra Peaks is the main bugbear here, particularly if your unit faces the site. This could affect the ease with which you’re able to secure tenants.
Then there’s the question of renovation.
When you renovate before renting out, you are exposing these new renovations to wear and tear. The degree varies based on how careful your tenant is, but it is a potential downside. As an alternative, you could also delay renovation till after you’re ready to move in yourself - but this requires that the existing state of the unit is good, and acceptable to tenants.
Alternatively, continuing to stay with your parents and purchasing a private home closer to the schools that you want to register your children at, would preserve flexibility. You would have a clearer picture of your children’s space requirements, and could assess the impact of Alexandra Peaks as it nears completion.
The trade-off is uncertainty over the future prices, and whether a suitable resale unit will be available.
In general, buying ahead could make sense if you find a home that already meets your long-term requirements. But we would be more cautious if the purchase depends on uninterrupted rental income, or if you remain unsure whether the size is right.
Let’s Take A Look At Some Projected Numbers for The Rental Option
Based on three-bedroom rental transactions lodged from January to June 2026, the average rent in Alessandrea is around $4,883 per month.
Let’s assume the purchase price of $2,210,000 (the average price for a 1,098 sq ft unit) and that you set aside $200,000 of cash for emergencies. Note that this is a working assumption, rather than a recommended purchase price for the exact unit you are considering.
| Purchase price | $2,210,000 |
| BSD | $80,100 |
| CPF | $700,000 |
| Cash | $300,000 |
| Loan required | $1,290,100 |
| Monthly mortgage repayment based on 20-year tenure and 4% interest | $7,817 |
| Monthly maintenance fee | $400 |
| Monthly rental income | $4,883 |
| Funds needed out of pocket | $3,334 |
Under these assumptions, the rent would cover around 59% of the mortgage repayment and maintenance fee. You would need to fund the remaining $3,334 each month, or approximately $120,000 over three years, assuming nothing changes.
Once you move in, the rental income would stop, so you would need to support the full mortgage instalment and maintenance fee which is approximately $8,217 a month under this example.
This excludes property tax, agent fees, and other expenses. Legal fees and any initial renovation or furnishing costs are also excluded from this calculation. Incidentally, this may also be a good time to remind anyone reading that the interest portion of the mortgage, as well as certain maintenance works, are tax deductible if the unit is rented out.
Is The Unit At Alessandrea Large Enough For This Family?
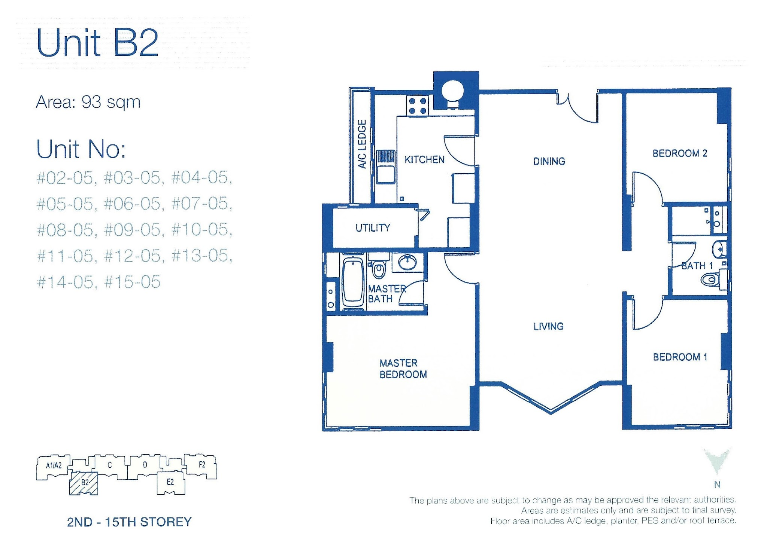
The 1,001 sq ft unit at Alessandrea has a dumbbell layout, which we’re surprised to see in an older unit. This is excellent, as the various rooms are connected via the living / dining area, which mitigates the need for wasteful corridors. The enclosed kitchen is also ideal, and the space appears generous by today’s standards.
Interestingly, this layout shares a common drawback with newer layouts too, with the main door opening directly into the living / dining area without an entrance foyer. But overall, this is quite an efficient and versatile layout.
Moving from your parents’ corner terrace may still take some adjustment, if it was much larger. We would suggest viewing the unit together, and checking how your intended furniture would fit.
Should Road Noise And Maintenance Costs Be A Concern?
Unlike the temporary construction noise from the development of Alexandra Peaks, traffic noise from the main road is an ongoing concern. This will come down to the unit’s facing and floor height, as well as sensitivity to noise.
With regards to floor height, do note that it’s not simply a case of “higher = quieter.” You really have to visit the unit at different times to get a sense of the noise level. This is partly due to the nature of sound barriers around the project. For example, it’s possible that nearby trees absorb and block sound up to the fifth or sixth floor, and the floors immediately above that are actually noisier.
As we mentioned earlier in this article, we wouldn’t consider $400 to be a particularly high maintenance amount for a unit of this size. If you’ve never paid condo maintenance before, it might help to know that it’s a norm to pay maintenance fees quarterly - so you’d be paying around $1,200 every three months, rather than $400 per month. It would be good to plan your cashflow accordingly.
Our main concern over maintenance is that Alessandrea has just 105 units. This means the overall condo expenses for the common areas are spread across a smaller number of owners, as opposed to bigger projects with over 600 units. This means that any substantive costs, particularly as the condo ages, may translate to bigger jumps in maintenance fees; but this is not guaranteed.
Would A Larger Home Elsewhere Better Suit Your Family?
This is a broad question that we can’t answer as well without specifics; namely, which other projects you may be considering. We would suggest making a shortlist of what’s available and within your budget, so that you can analyse the specific pros and cons of projects that - while larger - may be further from your children’s school.
The key thing to keep in mind is that family dynamics will change. Once your children grow older and move out, for instance, the additional space may no longer be required. Conversely, if your children end up staying with you for a prolonged period, or you want to accommodate grandchildren, then the larger unit sizes may pay off.
As a very general guideline - which does not apply equally to everyone - most people can adapt to less space better than they can extreme lifestyle disruptions. A smaller living and dining room, for instance, may not compensate for the children losing out on a whole hour of rest every day, due to a longer trip from school.
Our Thoughts
Alessandrea is worth considering not because it’s freehold, but because its location and size appear to suit the needs of your family. Being a freehold development has mitigated some of the effects of its age, but it has not made it an outperformer. We’d also say that, if you do decide to keep shortlisting other projects, suitable 99-year leasehold alternatives should be considered.
For your own stay needs, the key questions are whether the unit comfortably accommodates your family, especially in the years to come. The efficient 1,001 sq ft layout does generally work for a family of four, but assess it with your children’s teenage years in mind, including study space, privacy and storage.
The upcoming amenities at Alexandra Peaks could improve the overall convenience of the area, while the $400 monthly maintenance fee at Alessandrea is not likely to be substantially lower elsewhere - not for a unit of the same size.
Your savings give you flexibility, but buying now and renting out the unit would still require a substantial commitment. Our illustration puts the monthly shortfall at around $3,334 before property tax, agency fees, and vacancies. You should be able to fund this while keeping your emergency reserve intact. Once you move in, ensure you can sustain the full mortgage instalment and maintenance fee, even without rental income.
If you wait until your children are just about to enter primary school, you have more time to compare homes. But since you retain the same repayment horizon (ending at age 65), buying at 48 would shorten the loan tenure from 20 to 17 years. This could have consequences such as lowering your maximum loan quantum, and higher monthly repayments. If you do opt for this, we would suggest you save more aggressively over the three-year wait if possible since this could offset the additional costs.
While there’s no crystal ball for certainty, you also have to consider that - over those three years - home prices may rise unexpectedly. Ultimately, buy the unit when the price and financial commitment fit your personal financial situation. Don’t base your decisions on timing the market, as prices may rise or fall even in the near future.
At Stacked, we like to look beyond the headlines and surface-level numbers, and focus on how things play out in the real world.
If you'd like to discuss how this applies to your own circumstances, you can reach out for a one-to-one consultation here.
And if you simply have a question or want to share a thought, feel free to write to us at stories@stackedhomes.com. We read every message.





0 Comments