


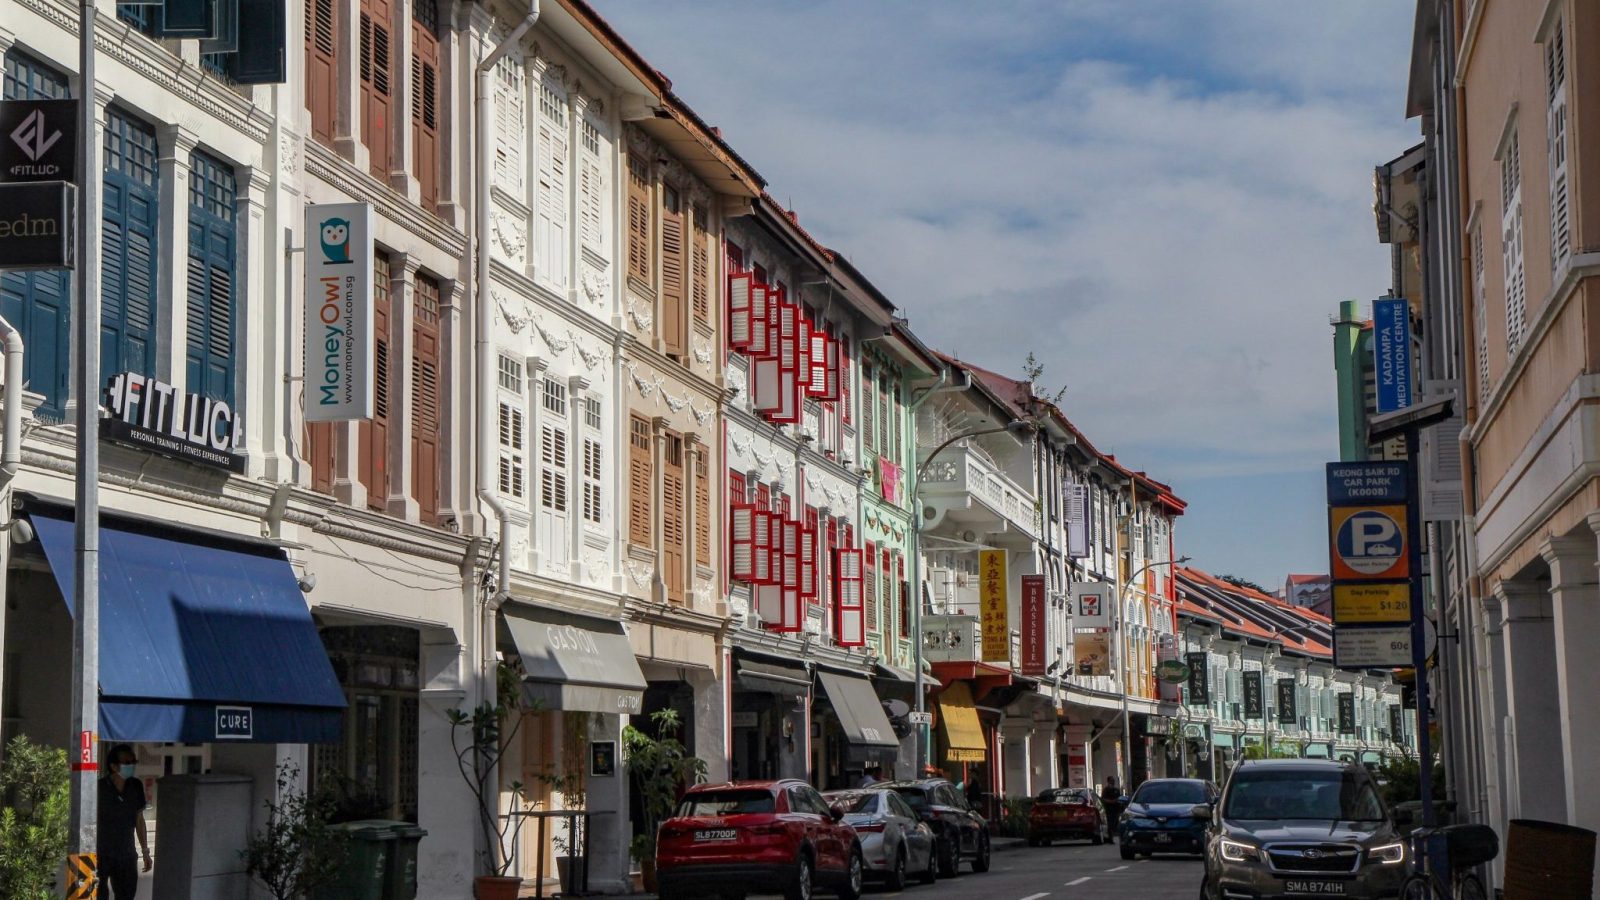
Although the underlying demand for shophouses in Singapore has remained robust, high prices and the lack of available properties on the market have caused this segment of the market to moderate.
Only 21 shophouse transactions were officially recorded in the third quarter of this year, and the total quarterly transaction value amounted to $157.7 million, according to research published by Huttons Asia.
Although an impressive-sounding figure, this is an 18.6% q-o-q decline. Huttons points out that the market is coming off a relatively higher base, after a standout $70 million transaction involving the sale of three adjoining shophouses at Lorong Liput in 2Q2026.
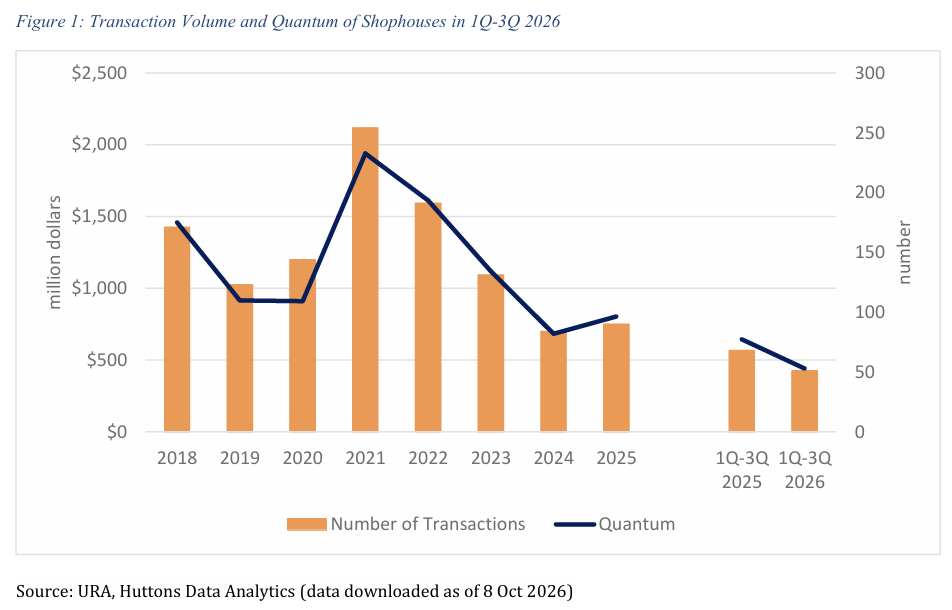
But the report also reflects a downward trajectory in the shophouse market over the past five years. In 2021, total sales volume amounted to nearly $2 billion, but declined to around $1.6 billion in 2022, and then fell again to just over $1 billion in 2023.
Over the first nine months of this year, there were 51 shophouse transactions that raked in a total of $441.3 million, down from the 68 deals that amounted to $644.5 million that closed over the same period in 2025. This is a yearly contraction of 31.5%.
In addition, the recent lifting of restrictions on new hotels, hostels, and serviced apartments in Upper Circular Road and Beach Road did not significantly contribute to a stronger market performance. No caveats were lodged in either area last quarter.
This doesn't mean that investment interest hasn't materialised. Shophouse deals take a long time to finalise, and with the added complexity of submitting approvals for a change of use, the purchase timeline has likely lengthened.
Nevertheless, Huttons Asia expects interest in shophouses to continue to attract high net-worth individuals, underpinned by favourable interest rates, constrained supply, and foreign ownership regulations in other segments of the property market.
(This refers to the high prevailing additional buyer's stamp duty imposed on foreign buyers purchasing residential property in Singapore.)
Top four shophouse transactions (by quantum) in 3Q2026
| Address | Land Area | Price ($) | Tenure |
|---|---|---|---|
| 261 South Bridge Road | 1,352 sq ft | $16.8 million | 999-LH |
| 85 Circular Road | 1,075 sq ft | $16.2 million | 999-LH |
| 406, 406A, 406B Joo Chiat Road | 1,886 sq ft | $10.1 million | FH |
| 164 Serangoon Road | 1,228 sq ft | $9.8 million | FH |
Caveated shophouse transactions also reveal that 70% of transactions were worth $5 million or more, as higher-value deals continue to dominate the market.
It is also clear that most shophouse buyers preferred freehold or 999-year leasehold assets, with 81% of all shophouse deals last quarter involving properties of those two tenures. Huttons says that freehold and 999-year leasehold shophouses are still the preferred property investment asset when it comes to wealth preservation.
The agency also says that shophouse deals were largely concentrated in District 8 - Little India, Farrer Park, and Jalan Besar - as well as East Coast neighbourhoods in District 15 like Joo Chiat.
In terms of leasing activities, shophouse rents were broadly unchanged at 6.47 psf per month (pm) in 3Q2026, unchanged from the previous quarter, according to data compiled by Huttons. Rental demand held up reasonably well due to new restaurant openings like Árō Singapore, Assaggi, Casa Lola, and KIN-NOMI.
Median shophouse rents
| District | 2Q2026 | 3Q2026 | Q-o-Q change |
|---|---|---|---|
| 1 | $7.50 psf pm | $7.35 psf pm | -2.0% |
| 2 | $7.27 psf pm | $7.92 psf pm | 8.9% |
| 8 | $5.78 psf pm | $6.17 psf pm | 6.7% |
| 14 | $4.77 psf pm | $4.94 psf pm | 3.6% |
| 15 | $6.11 psf pm | 6.04 psf pm | -1.1% |
| Islandwide | $6.43 psf pm | 6.47 psf pm | 0.6% |
Looking ahead, Huttons expects shophouse prices to remain steady, which is supported by tightly held ownership - owners face little pressure to sell unless a premium price is offered.
0 Comments