


The latest quarterly statistics show that quarterly private residential prices increased at their fastest pace in nearly two years in 3Q2026, even as fewer private homes changed hands compared to any other quarter this year.
Based on the final property statistics by URA released on October 23, the private residential Property Price Index (PPI) rose 1.4% q-o-q in 3Q2026, following a quarterly price increase of 0.5% in 2Q2026.
The last time that private home prices increased at this rate was back in 4Q2024, when prices jumped 2.3% q-o-q. In addition, this is the eighth consecutive quarter of price increases in the private residential market.
This means that private residential prices have risen 2.8% over the first nine months of this year, and we are close to matching or exceeding the 3.3% yearly increase that was registered in 2025.
Meanwhile, the number of private home transactions, excluding Executive Condominiums (ECs), fell 16.3% q-o-q to 5,146 units, the lowest quarterly count since 2Q2025, when 5,128 units were sold. The decline in transaction volume was a result of fewer new projects launching over the quarter.
"With sellers holding firm on asking prices, transaction volumes may stay tempered even as prices continue to edge up," says Wong Xian Yang, head of research for Singapore and Southeast Asia at Cushman & Wakefield (C&W).
Landed homes and the OCR carried most of the price gains
Landed home prices rose 2.9% q-o-q in 3Q2026, building on the 2.5% quarterly increase that was clocked in the previous quarter.
According to market data from PropNex, 588 landed homes were sold in 3Q2026, including 52 landed properties that were sold for $10 million or more. The most expensive landed sale was a freehold detached house on Dalvey Road, which sold for $56 million on September 30.
"Landed homes continue to attract buyers for their long-term value and established appeal," says Marcus Chu, CEO of ERA Singapore.
With landed homes making up just 11.4% of private home transactions, a cluster of large deals can move the landed index more than it would the non-landed one.
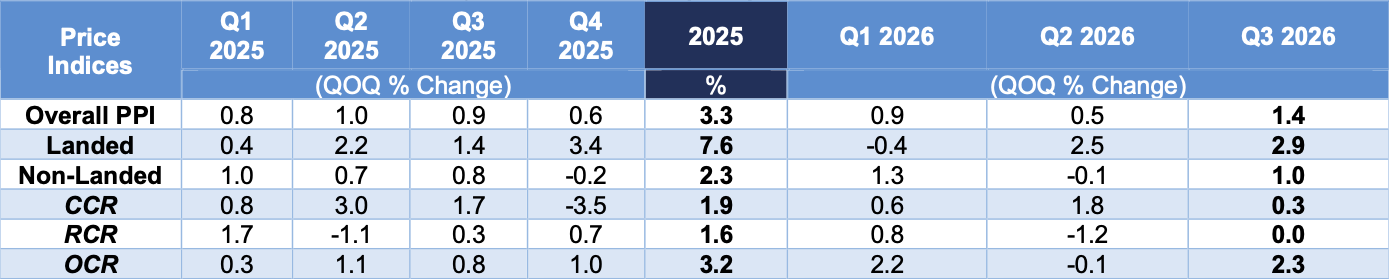
On the other hand, non-landed private residential prices rose a more modest 1% q-o-q, recovering from the 0.1% q-o-q decline that was registered in 2Q2026.
Most of the price gains in the non-landed segment stem from transactions in the Outside Central Region (OCR), where prices climbed 2.3% q-o-q, while prices in the Core Central Region (CCR) edged up 0.3%, and the Rest of Central Region (RCR) saw flat price growth.
Over the first nine months of this year, OCR prices have risen 4.4%. This is a significant improvement compared to the 3.2% price growth that the region clocked across the entirety of 2025. The RCR was the only region where price growth in 3Q2026 is lower compared to the start of this year.
Lentor Gardens Residences accounted for most of the new sales in the OCR
Most market analysts point to the sales momentum at Lentor Gardens Residences as the main driver behind the strong price growth in the OCR - which increased 2.3% q-o-q in 3Q2026.
The 499-unit development is the seventh new project in the Lentor precinct, and it was launched for sale in July this year. The 99-year leasehold development by Kingsford Group sold 304 units at a median price of $2,357 psf.
This psf price is 6.5% higher than the median price of $2,214 psf across units sold at the last new launch in Lentor, namely Lentor Central Residences, which hit the market in March 2025 and set a new benchmark price in Lentor back then.
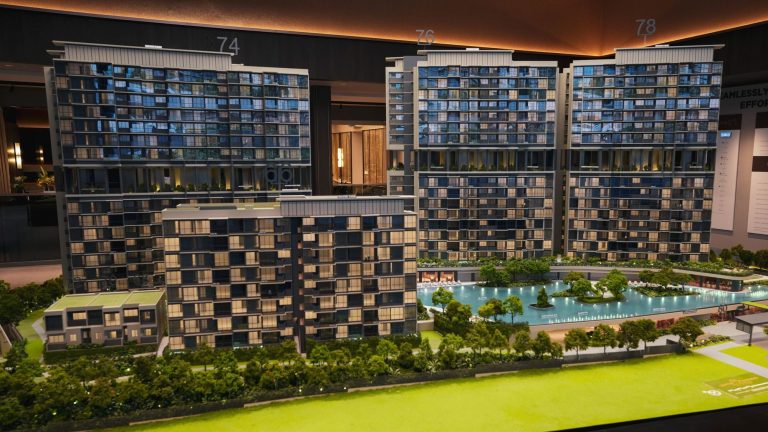
The 304 units sold by Lentor Gardens Residences made up close to two-thirds of the 477 new non-landed homes sold in the OCR over the quarter.
The median price of the development ($2,357 psf) is also 11.8% higher than the $2,108 psf achieved at Lentor Modern in 2022, which was the first new condo to break ground in Lentor. This reflects a price growth of 2.8% per year over four years.
Separately, resale private residential prices in the OCR slipped in 3Q2026, with the median resale price hitting $1,564 psf based on caveats lodged, down from the median price of $1,591 psf in 2Q2026.
Higher new launch prices may also have thinned out buyers in the region, and the 27.2% q-o-q drop in OCR transactions (2,595 units sold) could be attributed to persistent affordability concerns after stronger price gains and a slight increase in interest rates, says Lee Sze Teck, senior director of data analytics at Huttons Asia.
Buyers forked out higher $PSF prices, and most kept to a $2.5 million budget
Two of the new launch projects that entered the market last quarter were located in the CCR.
Dunearn House, the first project in Bukit Timah Turf City, sold 237 of its 380 units at a median of $3,107 psf when it launched for sale in July. Meanwhile, Amberwood at Holland launched for sale at the tail-end of the quarter (over the 26-27 Sept weekend) and sold 24 of its 212 units at an average selling price of $3,021 psf.
The latest quarterly statistics indicate that CCR prices rose just 0.3% despite these two launches. The moderate price growth is attributed to the relatively high base price in that region. Prices in the region climbed 1.8% in 2Q2026 on the back of the sales launch of River Modern, which launched for sale in March and saw over 90% of its units sold at a median price of $3,231 psf.
Proportion of new home sales by price range among new launch projects in 3Q2026
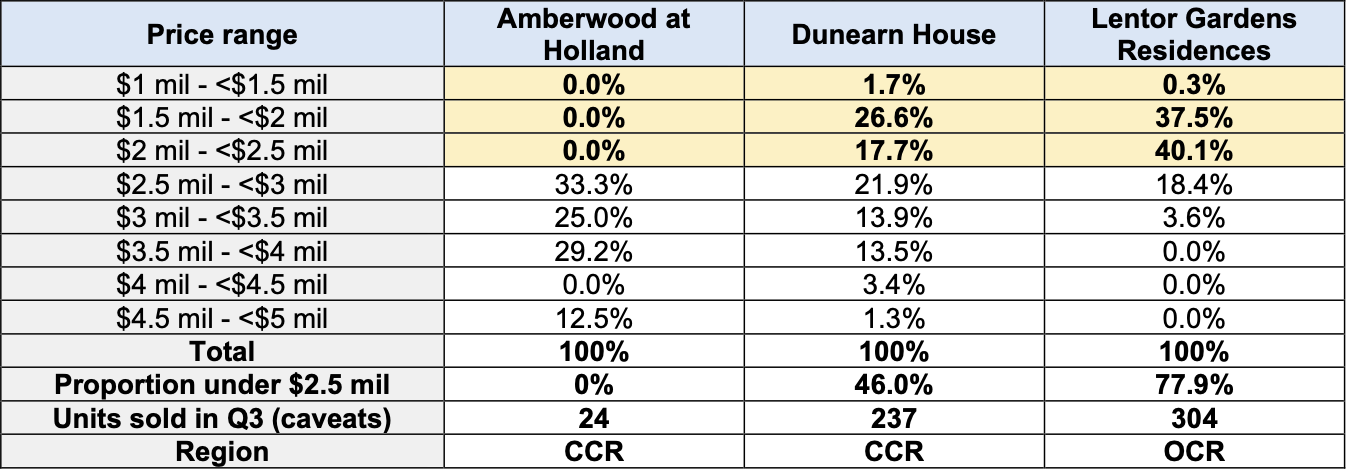
With two of the three new launch projects in 3Q2026 located in the CCR, the share of new non-landed homes sold below $2.5 million fell to 54.4% last quarter, compared to 69.4% in 2Q2026.
Market research from PropNex found that roughly 83% of over 3,000 prospective buyers who filled in expression-of-interest forms for seven new launches between January and July 2026 stated a budget of under $2.5 million.
"Developers launched fewer units in 3Q2026 amid the Lunar Seventh Month, but market absorption has been fairly steady, although buyers remain sensitive to absolute price quantum," says Kelvin Fong, CEO of PropNex.
New home sales fell to a two-year low as fewer projects hit the market
Overall, property developers sold 1,183 new private homes in 3Q2026, down 44.75% q-o-q and the lowest quarterly sales figure since 3Q2024.
The number of new launch units fell to 1,140 units from 1,783 in 2Q2026 during the Lunar Seventh Month.
Christine Sun, chief researcher and strategist at Realion (OrangeTee & ETC) Group, suggests that some buyers may be holding out for the projects lined up for the fourth quarter.
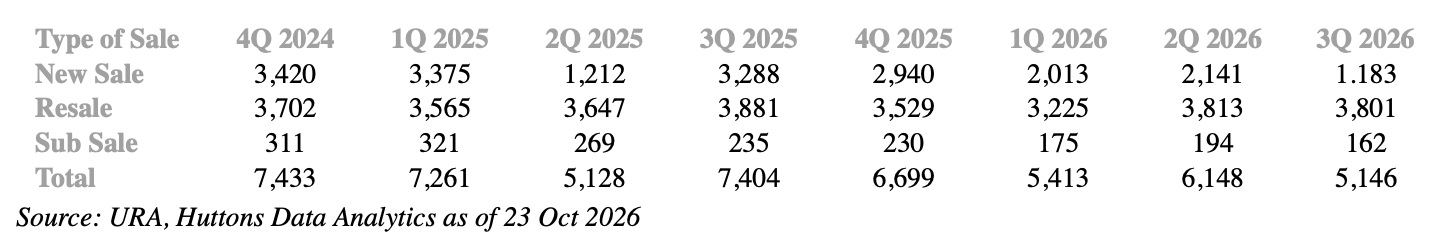
On the other hand, resale private home sales volumes held steady at 3,801 transactions over the three-month period, and resale transactions made up 73.9% of all private home transactions in 3Q2026.
But this is a higher figure compared to the 62% registered in 2Q2026.
Meanwhile, 16,707 private homes were transacted across the first nine months of this year. This is 15.6% fewer than in the same period last year. New sales account for most of that gap, with developers selling 5,337 new homes, 32.2% fewer than the 7,875 sold in the first nine months of 2025.
The number of unsold stock rose, but mostly from projects yet to launch
Unsold private homes, including completed units, jumped 26.7% q-o-q to 19,076 units.
Developers launched 1,140 units and sold 1,183 over the quarter, so the pool of launched yet unsold homes, which stood at 3,495 units at the end of 2Q2026, would have barely moved.
This count includes every project with planning approval, launched or not, so the increase comes from new projects that were approved during the quarter.
Even so, the total remains below the 10-year average of 21,498 units, according to Wong of C&W.
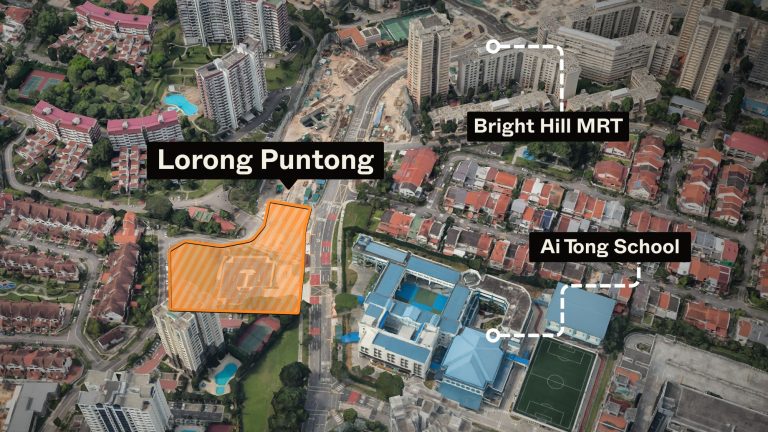
There were four Government Land Sales (GLS) tenders that closed in 3Q2026, and the winning land bids averaged $1,497 psf per plot ratio (ppr). They include the Lorong Puntong / Sin Ming Avenue site, awarded at a record RCR land rate of $1,612 psf ppr in September.
Wong Shanting, director and head of research at Newmark, attributes the quarter's stronger price growth to higher land costs being passed on to new home prices.
Collectively, the unsold stock and firmer land prices suggest that there is limited room for new home prices to ease meaningfully in the near-term, says Fong of PropNex.
Rents rose at their fastest pace in over three years
A total of 3,559 private homes were completed in 3Q2026, the most since 4Q2023, including Grand Dunman (1,008 units) and Lentor Mansion (533 units). As a result, the overall vacancy rate rose to 7.2% from 6.4% in 2Q2026, with the sharpest increase in the RCR, from 6.1% to 7.4%.
Rents still rose, with URA's rental index up 1.3% q-o-q, the fastest since 2Q2023. OCR rents grew the most at 3.1%, even though vacancy there rose to 6.5% from 5.6% in the previous quarter.
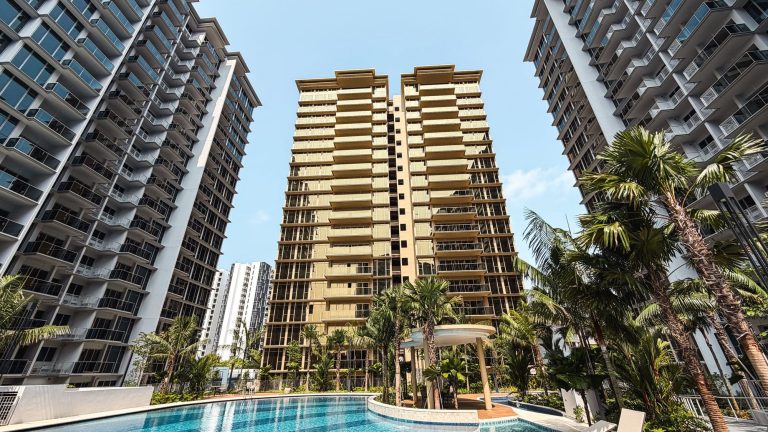
A total of 28,423 private home rental contracts were signed in 3Q2026, the highest quarterly number since records began in 1995. This likely reflects higher rents at newly completed projects, says Tricia Song, Head of Research, Singapore and Southeast Asia, at CBRE.
She adds that occupied private homes fell by 305 units, so more lease contracts did not mean more homes were being lived in. "Newly TOP-ed projects will broaden tenant choices, and leasing may take longer as tenants become more selective and landlords compete for quality occupants, especially amid slower hiring conditions," says Song.
Even with another 2,613 homes due to be completed in 4Q2026, CBRE has raised its full-year rent forecast to 2% to 3%, while Realion (OrangeTee & ETC) Group expects rents to rise 2.5% to 3%.
Most forecasts point to a smaller price increase in the final quarter of 2026
The last quarter of this year is already off to a strong start, as Lucerne Grand in Jurong West sold 61% of its 570 units over its initial sales launch over the October 3-4 weekend. According to caveated transactions up to October 18, 78.8% of the units were priced below $2.5 million.
The market is also anticipating the sales launch of Thomson Reserve, a 1,268-unit project on Bright Hill Drive with prices from $1.544 million ($2,608 psf).
"With 1,268 units and an average launch price above S$2,600 psf, Thomson Reserve could uplift the overall private property price index in Q4 2026, given its location in the RCR," says Sun of Realion.
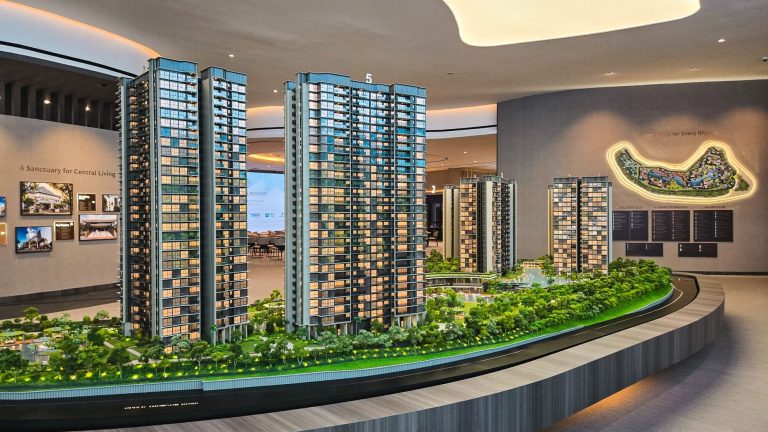
Far East Organization's The Serra Residences, a 133-unit freehold project in Novena, also launched in October after opening for preview earlier that month. Huttons notes it is one of only two major freehold developments in the CCR this year.
Analysts broadly expect private residential prices to rise 3% to 4% across the whole of 2026. With prices already up 2.8% over the first nine months, a 3% to 4% gain implies a fourth-quarter increase of only 0.2% to 1.2%.
New home sales forecasts for 2026 range from about 7,000 units (Huttons) to 8,000 to 8,500 (PropNex), which would imply roughly 1,660 to 3,160 sales in the fourth quarter on top of the 5,337 sold so far.
Interest rates are the main risk that has most analysts concerned, after the US Federal Reserve raised rates in September 2026 for the first time since July 2023.
Newmark has cut its new homes sales forecast to 7,000 to 7,800 units from its original 8,500 to 9,500, citing higher new homes prices, mortgage rates that have risen since late September, and the end of the 15-month waitout period, which could steer some private homeowners towards HDB resale flats instead.
It has also raised its resale and sub-sale forecast to 14,000 to 15,000 units as more completed homes come onto the market and the price gap between new and resale homes widens.
0 Comments