


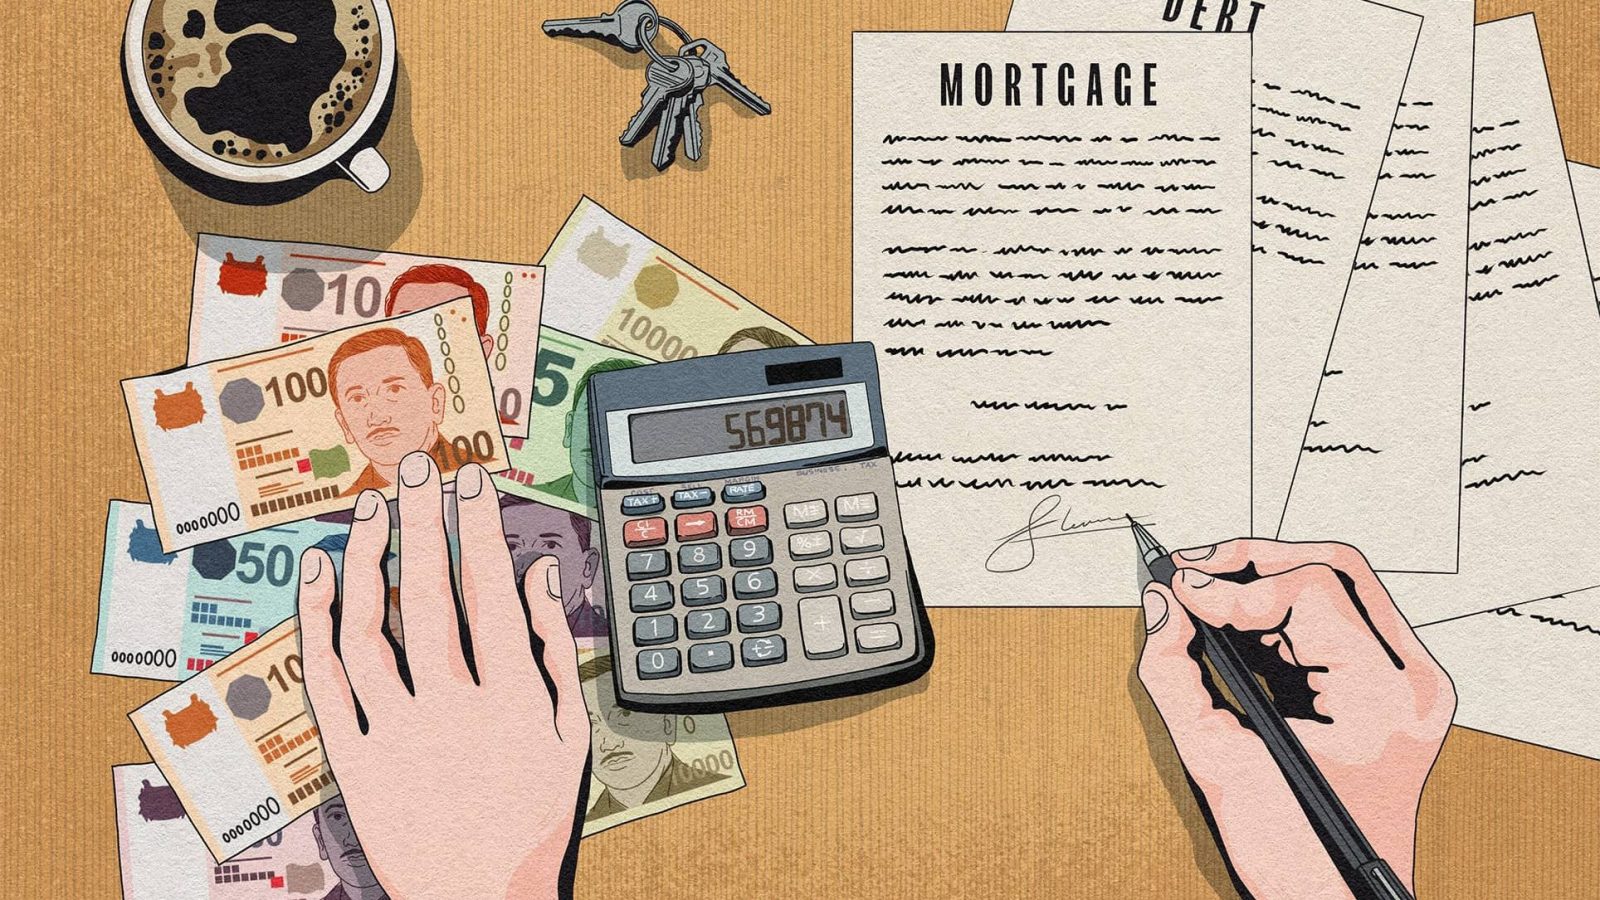
Singaporean home buyers are taking smaller loans, according to a recent media report - but is that necessarily a sign of safety?
The linked report includes statements by OCBC, who observe that Singaporeans are using more cash and CPF to cover the down payments for their property purchases. This is despite rising private home prices, which have been steadily climbing since the end of the Covid-19 pandemic. It was also mentioned that, when most property buyers reach 38 years old, most have accumulated sufficient amounts in their CPF to allow for a smaller loan.
As a quick explainer: the maximum loan quantum when you purchase a home is 75% of the price or valuation, whichever is higher. This leaves a minimum down payment of 25%. The first 5% of the down payment has to be in cash, while the next 20% can be in any combination of cash or CPF (it can be all CPF if you prefer). Hence, higher cash and CPF usage can mean buyers are taking less than the full loan amount.
In some cases, this isn’t because the homebuyers are gripped by a sudden bout of financial conservatism. It’s sometimes a matter of debt servicing ratios, like the Total Debt Servicing Ratio (TDSR), or the Mortgage Servicing Ratio (MSR) if an HDB property is involved.
The TDSR, for instance, caps monthly loan repayments to 55% of the borrowers’ combined income, inclusive of other debts. If they exceed this limit, they usually need a bigger down payment to reduce the monthly repayments. The MSR is even more restrictive, at 30% (although this excludes other loan obligations besides the home loan).
Whatever the reason, a bigger cash outlay does mean lower monthly repayments. It also means less exposure to interest rate risks*, or possibly a shorter loan tenure in some cases.
*This is especially relevant to those using bank loans, which fluctuate much more often than HDB loans. This is also important for buyers of Executive Condominiums (ECs), as there are no HDB loans for ECs.
Does This Mean Homebuyers Are In A Safer Place?
I wouldn’t be too quick to jump to that conclusion.
A chief concern is where the money for the bigger down payment comes from. A common source is the bank of mum-and-dad - and that’s fine when it comes from genuine surplus wealth like a trust or family office.
But there is - to my knowledge - no in-depth study or data on these parent-supported loans, and whether the parents who give them are financially capable of doing so. If parents are compromising their own retirement needs, then the bigger cash outlays we’re seeing aren’t necessarily a positive - especially not when Singapore is a super-aged society.
A particular concern is parents who sell their own home to help their children fund the purchase of a larger one, often with the assumption that they’ll live together as a multi-generational household. This is a move that provides very little room for reversal - if someone can’t get along with their in-laws, or there’s arguments over whether to sell, relationships can sour rapidly.
By coincidence, I ran into precisely this situation last week. A parent who supported their child by contributing to the down payment of a condo unit - as well as the first few years of loan repayments - was asked to sell the unit because his child wanted to move abroad. He was of the opinion that they should retain the unit, and the situation was about to devolve into a civil case.
This isn’t even the most unfortunate outcome by the way. Consider that some parents may not have the funds to leave and buy their own home again, thus leaving the dissenting family members stuck under the same roof.
There’s Also The Question Of Whether It’s Prudent To Make Such A Large Down Payment
Without going into personal finance - which is not our area of coverage - I daresay most financial advisors would frown at the notion of paying more than 25% of, say, a $2 million condo unit. Circumstances do differ between individuals; but most would agree this isn’t ideal, especially given Singapore’s very low interest rates. Even with recent interest rate hikes, private mortgages are mostly at 2% interest or below - this is even lower than the HDB loan’s 2.6%.
So, a buyer putting 40% down on a $2 million condo has committed an additional $300,000, compared to someone who puts down the minimum 25%. That may reduce the loan and monthly repayments, but it also means $300,000 less available for emergencies, career breaks, medical costs, children, and ageing parents.
Even if CPF is being used (here we have the familiar argument of “I can’t touch that money anyway”), it’s worth bearing in mind that excessive Ordinary Account (OA) funds can be transferred to your Special Account (SA) - that ensures an interest rate upward of 4%, higher than most mortgage rates.
Simply put, there are other things you can do with the money besides locking it up in the property; and we shouldn’t assume that reduced opportunities - or worse, reduced savings for emergencies - translates to a safer fiscal position.
Ultimately, Smaller Loans Look Reassuring On Paper, But I Wouldn’t Assume It Reflects Safety
To me, a better reflection of financial safety would be a study on income redundancy, particularly with regard to dual or single-income home owners. Ideally - and this isn’t possible for everybody - the mortgage should be structured so that, in a crisis, it can be fully paid by a sole breadwinner.
This was a far more common scenario when I was growing up, but increasingly I meet Singaporeans who can’t imagine taking on the entire mortgage themselves, while still also raising children and helping their parents. A dual income household has become the norm.
For those who can’t be in this scenario, perhaps it helps to remember that mortgage insurance is out there*. This can provide significantly more protection than just lowering your loan quantum, or the monthly repayment.
*Mortgage insurance is like HDB’s Home Protection Scheme - it pays the outstanding mortgage when claimed. But it’s not mandatory for private properties, so there’s a chance no one bothered to tell you about this when you bought a condo unit.
Meanwhile in other property news…
- This week, we helped a reader with her journey to sell a 674 sq ft two-bedder at AMO Residence. Check out our response which can help with tough sales.
- What happens when two brothers battle over a $5.7 million home? Here’s the background on the case and some important lessons.
- Waiting for an HDB flat? Here’s the rundown on the three most anticipated BTO launch sites to watch.
- Thanks to new Primary 1 registration rules, homes within 2km of Tao Nan School are now in priority enrolment range too. Check out the options here on Stacked Pro.
Unsure what your next property move should be?
Weekly Sales Roundup (12 October - 18 October)
Top 5 Most Expensive New Sales (By Project)
| Project name | Price S$ | Area (sqft) | $PSF | Tenure |
|---|---|---|---|---|
| RIVER MODERN | $7,045,000 | 1,830 | $3,850 | 99 yrs (2025) |
| UNION SQUARE RESIDENCES | $4,527,000 | 1,518 | $2,983 | 99 yrs |
| ELTA | $4,404,000 | 1,776 | $2,480 | 99 yrs (2024) |
| ONE MARINA GARDENS | $3,618,300 | 1,173 | $3,084 | 99 yrs (2023) |
| PARKTOWN RESIDENCE | $3,572,000 | 1,496 | $2,387 | 99 yrs |
Top 5 Cheapest New Sales (By Project)
| Project name | Price S$ | Area (sqft) | $PSF | Tenure |
|---|---|---|---|---|
| UNION SQUARE RESIDENCES | $1,463,000 | 506 | $2,892 | 99 yrs |
| NARRA RESIDENCES | $1,503,000 | 721 | $2,084 | 99 yrs |
| LUCERNE GRAND | $1,521,000 | 624 | $2,436 | 99 yrs |
| RIVER GREEN | $1,549,000 | 452 | $3,426 | 99 yrs (2024) |
| LENTOR GARDENS RESIDENCES | $1,595,800 | 678 | $2,353 | 99 yrs (2025) |
Top 5 Most Expensive Resale
| Project name | Price S$ | Area (sqft) | $PSF | Tenure |
|---|---|---|---|---|
| TOMLINSON HEIGHTS | $14,800,000 | 4,047 | $3,657 | FH |
| GRANGE RESIDENCES | $10,200,000 | 2,852 | $3,576 | FH |
| GALLOP GREEN | $9,400,000 | 3,574 | $2,630 | FH |
| THE DRAYCOTT | $7,388,000 | 2,637 | $2,801 | FH |
| 8 NAPIER | $6,780,000 | 2,013 | $3,368 | FH |
Top 5 Cheapest Resale
| Project name | Price S$ | Area (sqft) | $PSF | Tenure |
|---|---|---|---|---|
| HEDGES PARK CONDOMINIUM | $645,000 | 484 | $1,332 | 99 yrs (2010) |
| LOFT @ RANGOON | $658,000 | 420 | $1,567 | FH |
| KINGSFORD WATERBAY | $700,000 | 484 | $1,445 | 99 yrs (2014) |
| THE SANTORINI | $720,788 | 463 | $1,557 | 99 yrs (2013) |
| JOOL SUITES | $740,000 | 409 | $1,809 | FH |
Top 5 Biggest Winners
| Project name | Price S$ | Area (sqft) | $PSF | Returns | Holding period |
|---|---|---|---|---|---|
| TOMLINSON HEIGHTS | $14,800,000 | 4,047 | $3,657 | $3,575,000 | 15.4y |
| CARIBBEAN AT KEPPEL BAY | $5,588,888 | 2,390 | $2,339 | $3,339,788 | 26.0y |
| GRANGE RESIDENCES | $10,200,000 | 2,852 | $3,576 | $2,900,000 | 11.4y |
| REGENCY PARK | $5,400,000 | 2,250 | $2,400 | $2,880,000 | 20.3y |
| GALLOP GREEN | $9,400,000 | 3,574 | $2,630 | $2,609,400 | 14.1y |
Top 5 Biggest Losers
| Project name | Price S$ | Area (sqft) | $PSF | Returns | Holding period |
|---|---|---|---|---|---|
| REFLECTIONS AT KEPPEL BAY | $5,025,000 | 2,928 | $1,716 | -$2,018,000 | 19.1y |
| CLIVEDEN AT GRANGE | $6,340,000 | 2,153 | $2,945 | -$1,194,160 | 18.9y |
| SCOTTS SQUARE | $3,100,000 | 893 | $3,470 | -$311,260 | 19.2y |
| THE REEF AT KING'S DOCK | $1,850,000 | 743 | $2,491 | -$135,000 | 2.0y |
| DUO RESIDENCES | $2,970,000 | 1,432 | $2,075 | -$63,000 | 12.8y |
Top 5 Biggest Winners (ROI%)
| Project name | Price S$ | Area (sqft) | $PSF | % Return | Holding period |
|---|---|---|---|---|---|
| LAGUNA PARK | $1,870,000 | 1,453 | $1,287 | 240.0% | 25.8y |
| COTE D'AZUR | $2,138,000 | 1,109 | $1,928 | 231.6% | 24.2y |
| SIMS RESIDENCES | $1,790,000 | 1,432 | $1,250 | 166.0% | 25.3y |
| COMPASS HEIGHTS | $1,750,000 | 1,324 | $1,322 | 162.6% | 25.5y |
| MANDARIN GARDENS | $1,780,000 | 1,528 | $1,165 | 161.8% | 26.0y |
Top 5 Biggest Losers (ROI%)
| Project name | Price S$ | Area (sqft) | $PSF | % Return | Holding period |
|---|---|---|---|---|---|
| REFLECTIONS AT KEPPEL BAY | $5,025,000 | 2,928 | $1,716 | -28.7% | 19.1y |
| CLIVEDEN AT GRANGE | $6,340,000 | 2,153 | $2,945 | -15.8% | 18.9y |
| SCOTTS SQUARE | $3,100,000 | 893 | $3,470 | -9.1% | 19.2y |
| THE REEF AT KING'S DOCK | $1,850,000 | 743 | $2,491 | -6.8% | 2.0y |
| LOFT @ RANGOON | $658,000 | 420 | $1,567 | -4.6% | 5.7y |
Transaction Breakdown
| Type Of Sale (Proportion) | |||||||||||||||||||||
| |||||||||||||||||||||
| 191 private home sales: 38 new, 8 sub-sale, 145 resale | |||||||||||||||||||||
 |
Follow us on Stacked for news and updates on the Singapore property market.
0 Comments