


What do you expect to see in a prime district? Chances are, it’s not just a lot of construction like this.
This may be part of the reason why Amberwood at Holland moved only 23 units over its launch weekend. To be clear, the developer says that only 70 units were released during this first sales phase, so it sold 33% of its rleased units. But still this means that it moved 10% of its total number of units.
But as polite as most industry watchers have been, the fact remains: this is an oddity in the current market where we’re used to seeing new launches sell out 70% or more over the opening sales weekend.
When I saw the sales results of Amberwood at Holland, I was reminded of a close parallel: the sales launch of One Marina Gardens. Like Amberwood at Holland, that Marina South project also had a slower take up rate when it first hit the market, moving 38% of its units back in 2025 (and it still wasn’t fully sold as of June this year, when about 68% of the total units were sold).
These two projects share a key similarity, despite both being in traditionally high-quantum, high prestige districts: a prime district is not automatically a prime neighbourhood.
The challenge for many buyers today isn't access to information.
It's interpreting that information in a way that makes sense for their finances, goals, and stage of life.
Over time, that's also why we decided to work with agents who shared the same data-driven and advisory-led approach behind our editorial, consultants who could help readers think through decisions more objectively, rather than simply push transactions.
Today, the team has worked with more than 2,000 clients across over $5B in property transactions.
Connectivity And Amenities Go Beyond The District Number
To be clear, I’m not saying Amberwood at Holland and One Marina Gardens are direct comparables. The Holland Plain project has a larger, family-oriented unit mix and a much higher entry quantum, while One Marina Gardens has its own pricing and (mainly timing-related) issues. But they share one important quality:
Both are in nascent residential areas, despite the postal code.
One Marina Gardens is the first residential project in Marina South. Despite being in direct sight of Marina Bay, buyers are still being asked to look past the lack of nearby shops and F&B outlets, beyond what the project itself has. The Marina South MRT station (TEL) still isn’t open to the public, and will be only once there’s enough resident population to justify its operation.
Amberwood at Holland is, similarly, the first private residential project in the new Holland Plain precinct. It has District 10 on the brochure, but go down to the actual site and what you’ll see is mainly construction. For the first residents here, there isn’t much in the way of accessibility or amenities.
Factors like pricing do play a part - but I think beyond that, it reveals an important market perspective: a developer can’t just bank on the district number. Buyers have become more discerning, and fewer are interested in the trophy win of saying they live in District 1 or District 10.
We also see signs of this at the launch of River Green, which sold exceptionally well (88% sold on launch day) in District 9. This is despite criticisms about the small unit sizes, and the project being a 99-year leasehold project in a predominantly freehold area.
From conversations on the ground, with buyers and agents, it was revealed that location cut through these other concerns. It wasn’t simply that the project is in District 9, it was because Great World is one of the most family-oriented areas in the CCR, and River Green was close to River Valley Primary and a major mall.
This Is Also Where “First Mover Advantage” Takes On A Different Meaning
When it’s in the Outside of Central Region (OCR), buyers can be more receptive toward first mover advantage. This is partly due to past experiences in areas such as Jurong or Punggol, where transformative effects are highly visible.
But traditionally, first-mover advantage means getting in at the metaphorical ground floor. You’re getting a lower price that compensates you for patience. It means needing feeder buses, not having a school or mall nearby, and a decade of jokes about needing a passport to get to your place.
That proposition becomes harder in the CCR and prime districts.
For starters, buyers are already paying a premium price. Even in Holland Plain, for instance, Amberwood at Holland had units that are priced from around $2.5 million. One Marina Gardens did work hard to keep its sale prices low, with one-bedders at $1.16 million and two-bedders at $1.79 million. In the context of district price averages, it can be argued that these are reasonable entry prices.
But buyer psychology doesn’t work that way. To many average buyers, those prices are perceived as being high, and that means those quantums are not typically associated with a 10- to 15-year wait for conveniences.
There’s also the nature of the buyer demographic to consider.
To someone who shops in more prestigious districts, the aim may be a trophy home, or a homeowner’s indulgence. That is, a home with all the desired amenities or spaciousness, with less regard for rental yield or price appreciation.
That’s why the first-mover story is harder to sell at a high quantum. A buyer may accept a “room for growth” argument if the entry price feels like compensation, and if they’re already actively shopping on a budget. But for buyers paying for a prime address, the expectation is the full lifestyle package - they’re paying so much because they want the convenience and comfort now.
What Does This Mean For These Slower Moving Projects?
I don’t think either project is “doomed.” Marina South and Holland Plain will become more complete residential precincts over time, and their first buyers will likely benefit the most. But it does tell us something interesting about launch locations.
Because of common buyer expectations, an “ulu” location in the OCR might be easier to sell than an ulu pocket in a prime district.
Developers in such an unusual position may need a different pitch than the usual “first mover advantage” story. Rather than asking buyers to pay today for the transformation, they need to show why the project works independently of that. This may have to manifest in some immediate form, be it more generous layouts, better finishing, or more extensive facilities.
And if none of those arguments are strong enough, then the price has to do more work. A slightly lower $PSF than the district average may not be enough, if the current area seems to be just grass or construction.
https://media0.giphy.com/media/v1.Y2lkPTc5MGI3NjExcnNrOW16aWVxZTdkMXp6d2tmNzIzam82NTVzNHBwd3UzbjJieWZjciZlcD12MV9pbnRlcm5hbF9naWZfYnlfaWQmY3Q9Zw/P4p6JFiaSHoyTdYLZn/giphy.gif
Meanwhile in other property news…
- The Serra Residences has launched, and check out the preview to see what you can expect from this new District 11 project.
- Are Singapore REITs struggling in the 2026 market, and how do changing interest rates impact them? Find out here before you invest.
- How do you pick between multiple condos, that are all within one-kilometre of that desirable Primary school? Here’s a methodology that we’ll be applying over the coming weeks.
- Freehold landed versus strata titled landed homes, how wide has the price gap become? Find out the details and key insights with Stacked Pro.
Weekly Sales Roundup (21 - 27 September)
Top 5 Most Expensive New Sales (By Project)
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | TENURE |
| UPPERHOUSE AT ORCHARD BOULEVARD | $7,769,000 | 2056 | $3,779 | 99 yrs (2024) |
| AMBERWOOD AT HOLLAND | $4,834,000 | 1561 | $3,097 | 99 yrs |
| THE CONTINUUM | $4,565,000 | 1690 | $2,701 | FH |
| TERRA HILL | $4,017,000 | 1851 | $2,170 | FH |
| BAGNALL HAUS | $3,861,000 | 1528 | $2,526 | FH |
Top 5 Cheapest New Sales (By Project)
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | TENURE |
| UNION SQUARE RESIDENCES | $1,291,000.00 | 463 | $2,789.00 | 99 yrs (2024) |
| NARRA RESIDENCES | $1,506,000.00 | 721 | $2,088.00 | 99 yrs (2025) |
| THE SEN | $1,547,000.00 | 678 | $2,281.00 | 99 yrs (2025) |
| COASTAL CABANA | $1,706,000.00 | 915 | $1,865.00 | 99 yrs (2024) |
| BLOOMSBURY RESIDENCES | $1,772,000.00 | 678 | $2,613.00 | 99 yrs (2024) |
Top 5 Most Expensive Resale
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | TENURE |
| SCULPTURA ARDMORE | $20,000,000 | 3272 | $6,112 | FH |
| SKY@ELEVEN | $9,380,000 | 5490 | $1,709 | FH |
| GRANGE RESIDENCES | $9,250,000 | 2583 | $3,581 | FH |
| CLUNY PARK RESIDENCE | $8,280,000 | 2842 | $2,914 | FH |
| ARDMORE II | $7,320,000 | 2024 | $3,617 | FH |
Top 5 Cheapest Resale
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | TENURE |
| THE INFLORA | $665,000 | 463 | $1,437 | 99 yrs (2012) |
| 448@EAST COAST | $712,000 | 431 | $1,654 | FH |
| THE ALPS RESIDENCES | $725,000 | 463 | $1,566 | 99 yrs (2015) |
| URBAN VISTA | $725,000 | 441 | $1,643 | 99 yrs (2012) |
| DOUBLE BAY RESIDENCES | $735,000 | 538 | $1,366 | 99 yrs (2008) |
Top 5 Biggest Winners
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | RETURNS | HOLDING PERIOD |
| GRANGE RESIDENCES | $9,250,000 | 2583 | $3,581 | $3,150,000 | 15 Years |
| LEEDON RESIDENCE | $7,200,000 | 2669 | $2,697 | $2,300,000 | 11 Years |
| AALTO | $5,280,000 | 1959 | $2,695 | $2,030,000 | 15 Years |
| SUNGLADE | $2,000,000 | 1173 | $1,705 | $1,383,500 | 25 Years |
| ASTRID MEADOWS | $5,250,000 | 2433 | $2,158 | $1,300,000 | 13 Years |
Top 5 Biggest Losers
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | RETURNS | HOLDING PERIOD |
| 19 NASSIM | $2,435,000 | 829 | $2,938 | -$303,636 | 3 Years |
| DEVONSHIRE RESIDENCES | $1,030,000 | 495 | $2,080 | -$205,600 | 15 Years |
| DAISY SUITES | $1,038,000 | 764 | $1,358 | -$156,190 | 12 Years |
| VELA BAY | $2,501,000 | 883 | $2,834 | $0 | 4 Months |
| COASTAL CABANA | $1,733,000 | 990 | $1,750 | $0 | 1 Year |
Top 5 Biggest Winners (ROI%)
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | ROI (%) | HOLDING PERIOD |
| SUNGLADE | $2,000,000 | 1173 | $1,705 | 224% | 25 Years |
| THE QUARTZ | $1,800,000 | 1130 | $1,593 | 171% | 18 Years |
| THE FLORIDA | $1,593,000 | 1389 | $1,147 | 169% | 28 Years |
| SIMS GREEN | $1,470,000 | 1238 | $1,188 | 160% | 25 Years |
| HUNDRED PALMS RESIDENCES | $2,050,000 | 958 | $2,140 | 152% | 9 Years |
Top 5 Biggest Losers (ROI%)
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | ROI (%) | HOLDING PERIOD |
| DEVONSHIRE RESIDENCES | $1,030,000 | 495 | $2,080 | -17% | 15 Years |
| DAISY SUITES | $1,038,000 | 764 | $1,358 | -13% | 12 Years |
| 19 NASSIM | $2,435,000 | 829 | $2,938 | -11% | 3 Years |
| VELA BAY | $2,501,000 | 883 | $2,834 | 0% | 4 Months |
| COASTAL CABANA | $1,733,000 | 990 | $1,750 | 0% | 1 Years |
Transaction Breakdown
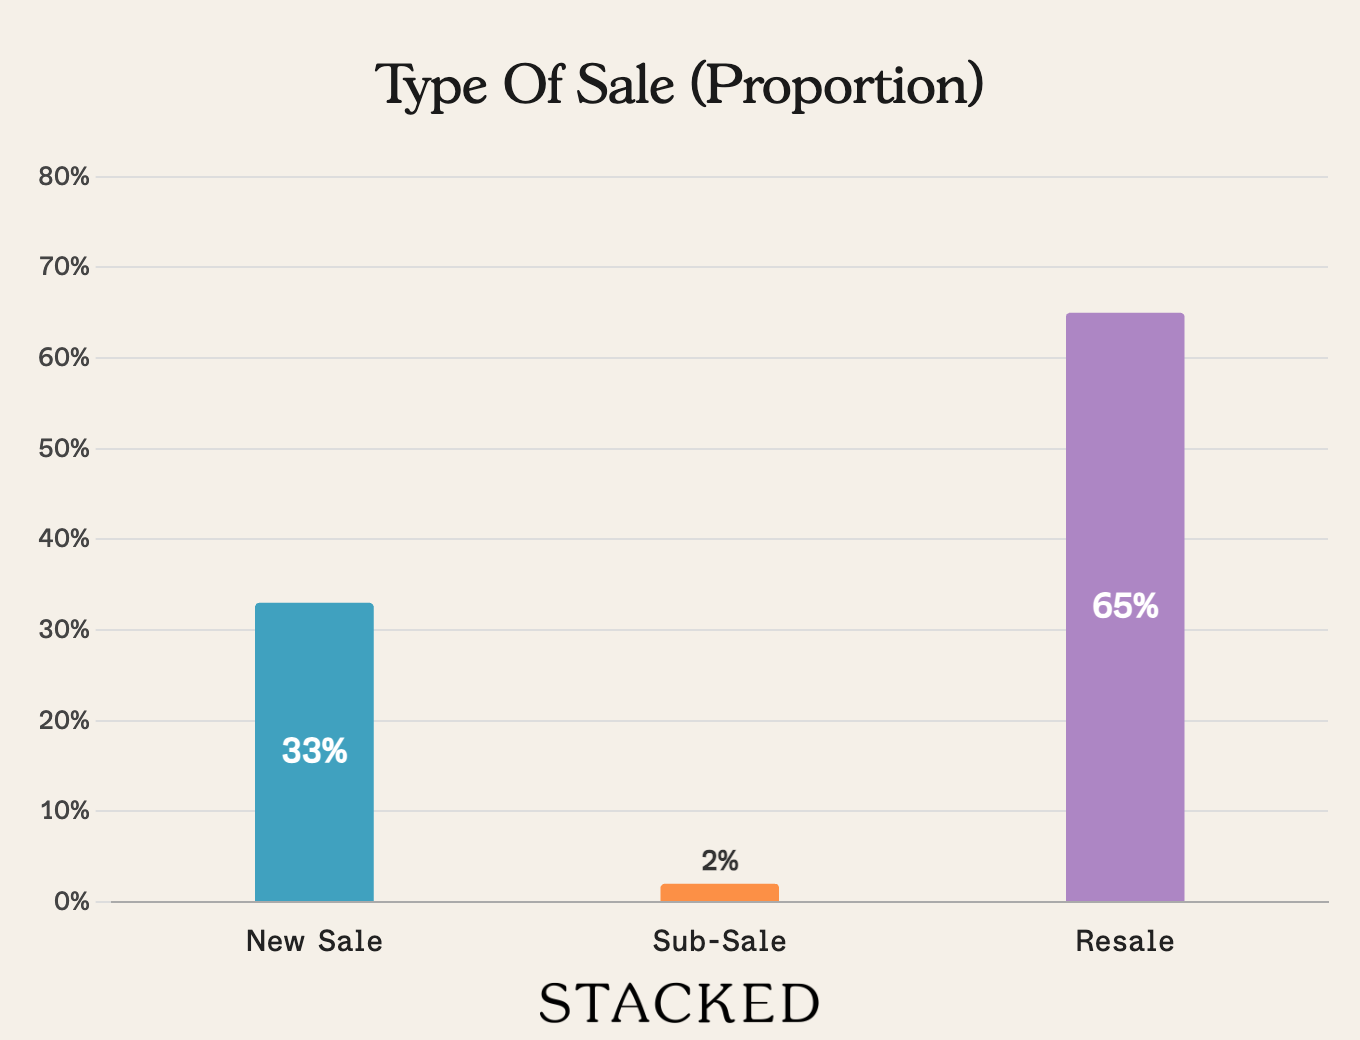
Follow us on Stacked for news and updates on the Singapore property market.
At Stacked, we like to look beyond the headlines and surface-level numbers, and focus on how things play out in the real world.
If you'd like to discuss how this applies to your own circumstances, you can reach out for a one-to-one consultation here.
And if you simply have a question or want to share a thought, feel free to write to us at stories@stackedhomes.com. We read every message.
0 Comments