


Well, there goes the seaview.
For decades, the residents in the Bayshore Road cluster (three condos: Costa Del Sol, Bayshore Road, and Bayshore Park) have tolerated poor public transport access, and limited amenities, in exchange for one of Singapore’s best sea views. But with the Long Island Plan underway, these residents are going to lose their beloved seafront views, with all the ships lining up along the coast.
To make it even worse, the Long Island project will likely close large swathes of East Coast Beach; so one of the main selling points of condos like Costa Del Sol (underground beach access) will be diminished; at least for a number of years. This is the loss of a major amenity, if it means that the BBQ pits, biking trails, fishing piers, and the nearby food village are all shut down.
But there’s some compensation: Bayshore is going to house a new HDB enclave, with MRT stations, shopping, and so forth. And the new MRT station, which should be running by next year, is already visible. These flats are even Plus model flats; and these developments will fix long standing issues of inaccessibility, and sparse amenities.
This has resulted in two conflicting views:
The first is that condos around Bayshore are going to fare badly: they’re losing their view, and the former peace and quiet will be shattered by dense housing blocks and bus malls.
The second is that condos around Bayshore should be celebrating, because the emergence of the MRT station - along with new amenities - will cause values to skyrocket.
Which is correct? I have to admit, it has me stumped. This is like downing sleeping pills with Red Bull; I don’t know which of the two forces are going to win out. But one thing’s for sure: the vibe of the entire Bayshore area is going to change. We may see a transition from the current “quiet resort” environment, to an emergent hub - perhaps comparable to Paya Lebar or Tampines, in the earlier stages of their upgrading.
Incidentally, if you’re wondering why I don’t just call up the price data and check, it’s because that’s of no real use right now. Practically every project saw good appreciation in the post-Covid period, especially older condos with bigger units; so while prices have gone up for all three Bayshore Road condos, there’s no way to tell how much of it is due (or not due) to the new enclave.
It also goes to show that, in the long run, even knowing the Master Plan has limited benefits
There were no large residential plots near the Bayshore condos at the time they were built; everything in the area was low-density, all the way up to the Bedok South area. The nearby Lucky Heights estate was - and still is - all landed housing.
Costa Del Sol and Bayshore Park were pushed right up against the coast; building anything else would require it to be underwater. So who could foresee that, at some point during the 99-year lease, Singapore would build an entire island to block the seaview? Or that an HDB enclave would literally spring up out of nowhere?
And as an interesting aside, some residents of Bayshore and Bayshore Park have gone through this before: when Costa Del Sol became the newest condo on the block, many decades back, some units at these two older properties also had their seaview impeded And in these cases, the owners also wouldn’t have seen it coming, as Costa Del Sol’s land parcel wasn’t visible on the Master Plan to them - at least not at the time.
In the end, we can study the Master Plan as much as we like; but over periods of five or more years, it’s still a case of “anything goes.”
Meanwhile, in other property news…
- The RTS link is bringing Johor properties back into the spotlight. Check out what’s going on.
- Three upcoming resale ECs to consider in 2024. Remember, there’s no upfront ABSD if you’re upgrading, and no more MOP.
- Leasehold condos on freehold land: a sneaky issue that will absolutely get you, when it comes to en-bloc prospects.
- Check out Lentor Green and Lentor Grove, one of the few landed enclaves where homes at $3.6 million or below are still possible.
Weekly Sales Roundup (20 November - 26 November)
The challenge for many buyers today isn't access to information.
It's interpreting that information in a way that makes sense for their finances, goals, and stage of life.
Over time, that's also why we decided to work with agents who shared the same data-driven and advisory-led approach behind our editorial, consultants who could help readers think through decisions more objectively, rather than simply push transactions.
Today, the team has worked with more than 2,000 clients across over $5B in property transactions.
Top 5 Most Expensive New Sales (By Project)
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | TENURE |
| WATTEN HOUSE | $14,496,000 | 4080 | $3,545 | FH |
| MIDTOWN MODERN | $6,537,000 | 1808 | $3,615 | 99 yrs (2019) |
| THE CONTINUUM | $5,746,000 | 1905 | $3,016 | FH |
| 19 NASSIM | $4,939,050 | 1410 | $3,503 | 99 yrs (2019) |
| THE RESERVE RESIDENCES | $3,762,586 | 1625 | $2,315 | 99 yrs (2021) |
Top 5 Cheapest New Sales (By Project)
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | TENURE |
| THE ARDEN | $1,220,000 | 657 | $1,858 | 99 yrs (2023) |
| ORCHARD SOPHIA | $1,285,000 | 463 | $2,776 | FH |
| PINETREE HILL | $1,316,700 | 538 | $2,446 | 99 yrs (2022) |
| THE LAKEGARDEN RESIDENCES | $1,328,000 | 592 | $2,243 | 99 yrs (2023) |
| GRAND DUNMAN | $1,385,000 | 549 | $2,523 | 99 yrs (2022) |
Top 5 Most Expensive Resale
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | TENURE |
| 8 NAPIER | $6,700,000 | 2013 | $3,329 | FH |
| THE SOVEREIGN | $6,500,000 | 2637 | $2,465 | FH |
| PEBBLE BAY | $5,100,000 | 2626 | $1,942 | 99 yrs (1994) |
| AALTO | $3,820,000 | 1528 | $2,499 | FH |
| DUET | $3,680,000 | 1744 | $2,110 | FH |
Top 5 Cheapest Resale
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | TENURE |
| SUITES@BRADDELL | $650,000 | 398 | $1,632 | FH |
| SUITES @ SIMS | $655,000 | 355 | $1,844 | FH |
| PARC ROSEWOOD | $662,672 | 431 | $1,539 | 99 yrs (2011) |
| JOOL SUITES | $725,000 | 409 | $1,772 | FH |
| LAVERNE'S LOFT | $740,000 | 474 | $1,562 | FH |
Top 5 Biggest Winners
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | RETURNS | HOLDING PERIOD |
| THE SOVEREIGN | $6,500,000 | 2637 | $2,465 | $3,000,000 | 13 Years |
| DUET | $3,680,000 | 1744 | $2,110 | $2,319,000 | 19 Years |
| AMARANDA GARDENS | $2,508,000 | 1259 | $1,991 | $1,676,000 | 22 Years |
| ROBERTSON 100 | $2,638,888 | 1152 | $2,291 | $1,569,688 | 19 Years |
| HUME PARK II | $2,450,000 | 1475 | $1,661 | $1,560,000 | 25 Years |
Top 5 Biggest Losers
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | RETURNS | HOLDING PERIOD |
| THE VERMONT ON CAIRNHILL | $2,300,000 | 915 | $2,514 | -$200,000 | 11 Years |
| LUMIERE | $985,000 | 635 | $1,551 | -$175,000 | 13 Years |
| THE ROCHESTER RESIDENCES | $1,300,000 | 1023 | $1,271 | -$50,360 | 15 Years |
| D'LEEDON | $1,308,000 | 635 | $2,060 | $6,600 | 11 Years |
| SIXTEEN35 RESIDENCES | $1,000,000 | 667 | $1,498 | $12,000 | 5 Years |
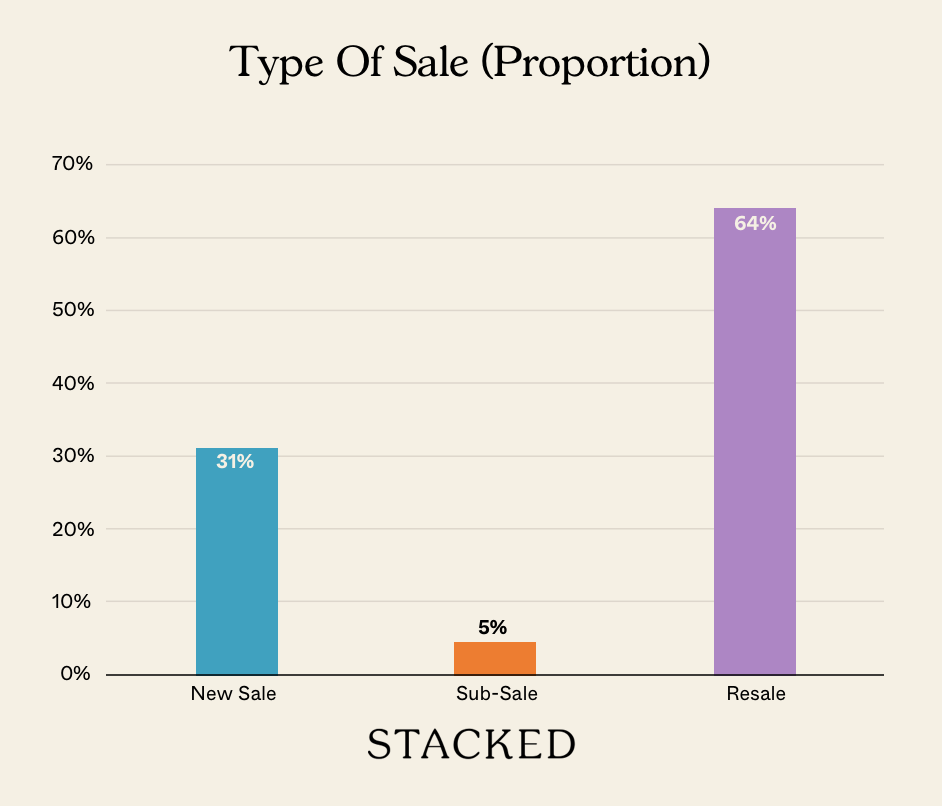
Transaction Breakdown
Follow us on Stacked for updates on the Singapore property market, as well as reviws of new and resale properties alike.
At Stacked, we like to look beyond the headlines and surface-level numbers, and focus on how things play out in the real world.
If you'd like to discuss how this applies to your own circumstances, you can reach out for a one-to-one consultation here.
And if you simply have a question or want to share a thought, feel free to write to us at stories@stackedhomes.com. We read every message.





0 Comments