

Dear Stacked Homes, Happy new year!
We are a couple with combined income of $23k (41yo $16k, 29yo $7k), currently live in a 29yr old 4br hdb resale (mkt value abt $580k) under joint ownership, and has fulfilled the MOP.
We have a toddler who is going to primary school in a few years time. We wish to move to a new home in the near term preferably near a good primary school but also see how we can get into a 2nd property as investment for rental income. We have about $450k in cash, cpf & liquid investments.
We are looking at a few options:
1) Sell our resale, and buy a resale 3br condo. We prefer a condo that is relatively new and does not look dated;
2) Decouple our current hdb, and buy a 2br condo for investment, and buy a new younger resale hdb (min. 4br);
3) Decouple our current hdb, and buy a new launch condo. If this is not possible, maybe buy a new launch without decoupling and sell our hdb for ABSD remission within 6mths of getting the keys; or
4) Simply hold out, save up, and wait for a better time to sell and move.
Looking forward to your advice!
Thank you
Regards,
Hi there,
Thanks for writing in with your question.
This is a common scenario that I’ve advised my clients on before, where the need to move is brought about because of a child’s primary school. Such a move often prompts a discussion on restructuring property needs as well as having an investment angle to it as well.
Based on my experience with former clients, relocating closer to a primary school typically yields long-term benefits. It's important to note that the advantage isn't primarily financial. Rather, the convenience of having a reputable school nearby for your child, coupled with the reduction in time and stress associated with school commutes, often outweighs any potential shortcomings in the property's investment value.
Let’s start by looking at your affordability before going into the various options you’re considering.
The challenge for many buyers today isn't access to information.
It's interpreting that information in a way that makes sense for their finances, goals, and stage of life.
Over time, that's also why we decided to work with agents who shared the same data-driven and advisory-led approach behind our editorial, consultants who could help readers think through decisions more objectively, rather than simply push transactions.
Today, the team has worked with more than 2,000 clients across over $5B in property transactions.
Affordability
Selling
| Description | Amount |
| Selling price | $580,000 |
| CPF funds to be refunded into OA | $349,666 |
| Cash proceeds | $230,334 |
Buying
Combined affordability (Buying a private property)
| Description | Amount |
| Maximum loan based on ages of 29 and 41 with a combined monthly income of $23K, at 4.8% interest | $2,294,924 (27-year tenure) |
| CPF funds | $380,666 |
| Cash and liquid assets* | $649,334 |
| Total loan + CPF + cash | $3,324,924 |
| BSD based on $3,324,924 | $139,095 |
| Estimated affordability | $3,185,829 |
*Cash and liquid assets include the sales proceeds but I have deducted the CPF funds in your OA currently ($230,334 + $450,000 - $31,000)
Individual affordability
Husband (Buying a private property)
| Description | Amount |
| Maximum loan based on the age of 41 with a monthly income of $16K, at 4.8% interest | $1,503,192 (24-year tenure) |
| CPF funds | $284,775 |
| Cash and liquid assets* | $324,667 |
| Total loan + CPF + cash | $2,112,634 |
| BSD based on $2,112,634 | $75,231 |
| Estimated affordability | $2,037,403 |
*I have split the total cash and liquid assets equally
Wife (Buying a private property)
| Description | Amount |
| Maximum loan based on the age of 29 with a monthly income of $7K, at 4.8% interest | $733,801 (30-year tenure) |
| CPF funds | $95,891 |
| Cash and liquid assets* | $324,667 |
| Total loan + CPF + cash | $1,154,359 |
| BSD based on $1,154,359 | $30,774 |
| Estimated affordability | $1,123,585 |
*I have split the total cash and liquid assets equally
Seeing as your husband will be eligible for a higher loan quantum, I will assume that in the event of an HDB purchase, you will be listed as the owner.
Wife (Buying an HDB)
| Description | Amount |
| Maximum loan based on the age of 29 with a monthly income of $7K, at 4.8% interest* | $366,494 (25-year tenure) |
| CPF funds | $95,891 |
| Cash and liquid assets | $324,667 |
| Total loan + CPF + cash | $787,052 |
| BSD based on $787,052 | $18,211 |
| Estimated affordability | $768,841 |
*As your combined household income is above the $14K ceiling, you will not be eligible for an HDB loan and will have to take up a bank loan
Given that you do have a substantial amount of cash and liquid assets, your individual budgets can be easily altered by adjusting the cash portion. For the sake of a simpler calculation, I have split it equally.
Now that you have a clearer idea of your affordability, let’s run through the options you’re considering.
Option 1. Sell HDB, buy a resale 3-bedroom condo
With a combined affordability of $3.1M, acquiring a 3-bedroom condo in most locations is certainly within your reach.
However, since you are looking to purchase a second property for investment, it would make sense to acquire the 3-bedroom unit under your husband's name to leave your name available for another property purchase.
In this scenario, with a $2M budget, you would likely need to explore projects situated in the Rest of Central Region (RCR) or Outside Central Region (OCR), further refining the selection of schools to consider.
An advantage of this approach is the possibility of purchasing both properties simultaneously, minimising the wait time and ensuring you capitalise on potential profits from the investment property.
Let's look at the potential costs and rental income associated with this pathway. For calculation purposes, I will assume a simultaneous purchase of both properties with a 10-year holding period.
Own residence under Husband’s name purchased at $2M
| Description | Amount |
| Purchase price | $2,000,000 |
| BSD | $69,600 |
| CPF + cash | $609,442 |
| Loan required | $1,460,158 |
Costs incurred
| Description | Amount |
| Interest expense (Assuming 4% interest and 24 year tenure) | $501,558 |
| BSD | $69,600 |
| Property tax | $36,800 |
| Maintenance fees (Assuming $350/month) | $42,000 |
| Total costs | $649,958 |
Investment property under Wife’s name purchased at $1.1M, with a 3% rental yield
| Description | Amount |
| Purchase price | $1,100,000 |
| BSD | $28,600 |
| CPF + cash | $420,558 |
| Loan required | $708,042 |
Costs incurred
| Description | Amount |
| Interest expense (Assuming 4% interest and 30 year tenure) | $255,418 |
| BSD | $28,600 |
| Property tax | $42,000 |
| Maintenance fees (Assuming $250/month) | $30,000 |
| Rental income | $330,000 |
| Agency fee (Payable once every 2 years) | $14,850 |
| Total costs | $40,868 |
Total costs if you were to take this route: $649,958 + $40,868 = $690,826
Option 2. Sell HDB, buy another HDB under the owner-occupier arrangement, buy a private property after MOP
This isn't the first time a client has presented this proposal to me, and it likely won't be the last. Unfortunately, unlike private properties, decoupling is not an option for HDB flats. As such, changing ownership must fall under special situations.
Otherwise, the only method to release an owner's name is to sell the flat and acquire another one under the owner-occupier scheme. Consequently, the occupant must wait until the flat fulfils its Minimum Occupation Period (MOP) before being eligible to purchase the second property.
With that out of the way, here’s an overview of the average 5-room and Executive flat prices recorded in Q4 2023.
| Towns | 5-Room | Executive |
| Ang Mo Kio | $788,000 | * |
| Bedok | $695,000 | * |
| Bishan | $918,000 | * |
| Bukit Batok | $767,500 | $835,000 |
| Bukit Merah | $959,000 | - |
| Bukit Panjang | $620,000 | * |
| Bukit Timah | * | * |
| Central | * | - |
| Choa Chu Kang | $603,000 | * |
| Clementi | * | * |
| Geylang | * | * |
| Hougang | $655,000 | $895,000 |
| Jurong East | $628,000 | * |
| Jurong West | $588,000 | $698,000 |
| Kallang/Whampoa | $880,400 | * |
| Marine Parade | * | - |
| Pasir Ris | $663,000 | $816,000 |
| Punggol | $670,000 | * |
| Queenstown | * | * |
| Sembawang | $602,900 | * |
| Sengkang | $610,000 | $730,000 |
| Serangoon | * | * |
| Tampines | $685,000 | $877,400 |
| Toa Payoh | $881,900 | * |
| Woodlands | $598,500 | $800,000 |
| Yishun | $660,000 | * |
With a budget of $768K, it might be a challenge getting an Executive unit. However, certain 5-room flats do come with 4 bedrooms so that could be a feasible alternative.
As before, let’s look at the potential costs and rental income over 10 years.
Own residence under Wife’s name purchased at $768K
| Description | Amount |
| Purchase price | $768,000 |
| BSD | $17,640 |
| CPF + cash | $420,558 |
| Loan required | $365,082 |
Costs incurred
| Description | Amount |
| Interest expense (Assuming 4% interest and 25 year tenure) | $126,683 |
| BSD | $17,640 |
| Property tax | $6,020 |
| Town council service & conservancy fees (Assuming $85/month) | $10,200 |
| Total costs | $160,543 |
Since your husband will only be able to purchase the investment property 5 years later, his loan quantum will differ so let’s look at his revised affordability.
| Description | Amount |
| Maximum loan based on the age of 46 with a monthly income of $16K, at 4.8% interest | $1,314,607 (19 year tenure) |
| CPF funds* | $322,197 |
| Cash and liquid assets | $324,667 |
| Total loan + CPF + cash | $1,961,471 |
| BSD based on $1,961,471 | $67,673 |
| Estimated affordability | $1,893,798 |
*I have included the accrued CPF interest over 5 years
Assuming his income remains the same, buying the second property 5 years later will reduce his affordability by $143,605, which is a rather considerable amount. However, seeing as you’re planning to buy a 2-bedder, $1.8M should still offer a good range of options.
Investment property under Husband’s name purchased at $1.5M, with a 3% rental yield
| Description | Amount |
| Purchase price | $1,500,000 |
| BSD | $44,600 |
| CPF + cash | $646,864 |
| Loan required | $897,736 |
Costs incurred
| Description | Amount |
| Interest expense (Assuming 4% interest and 30 year tenure) | $162,948 |
| BSD | $44,600 |
| Property tax | $33,000 |
| Maintenance fees (Assuming $250/month) | $15,000 |
| Rental income | $225,000 |
| Agency fee (Payable once every 2 years) | $12,150 |
| Total costs | $42,698 |
Total costs if you were to take this route: $160,543 + $42,698 = $203,241
Option 3. Buy a new launch condo
As previously mentioned, decoupling an HDB flat is not feasible, which means you will have to sell your flat to restructure your portfolio.
To qualify for the Additional Buyer's Stamp Duty (ABSD) remission, the property must serve as a matrimonial home, implying that the new launch condo must be purchased jointly. Consequently, you may only possess one property, or decoupling may be required later to free up one name to purchase a second property. However, it's essential to note that during decoupling, the party acquiring the shares must be eligible to undertake the revised loan independently.
There are various constraints associated with this approach. Firstly, your choices will be constrained by the locations of the new launches, which may or may not align with your preferred school proximity. Additionally, the Buyer's Stamp Duty (BSD) and ABSD must be settled within 14 days of exercising the Option To Purchase (OTP). With $450K in CPF, cash, and liquid assets, this sum would only cover the BSD and ABSD for a $1.9M property, excluding the down payment. Therefore, purchasing the new launch before selling your flat is not a feasible option.
Option 4. Remain status quo
Without your address, it's difficult to provide specific advice on whether you should retain ownership of the flat. While current prices are still high, this also means potential high costs for your next property purchase. Moreover, elevated interest rates will contribute to increased expenses.
Considering your child is still a toddler and some distance away from attending primary school, you do have the time to wait and observe the market for a while. In the short term, HDB prices are unlikely to experience significant fluctuations. Additionally, since you have fully repaid your loan, the expenses associated with maintaining your current flat are relatively low.
What should you do?

| Year | HDB Resale Price Index | Non-landed Private Property Price Index |
| 2013-Q4 | 145.8 | 147.6 |
| 2014-Q4 | 137 | 142.5 |
| 2015-Q4 | 134.8 | 137.4 |
| 2016-Q4 | 134.6 | 133.8 |
| 2017-Q4 | 132.6 | 135.6 |
| 2018-Q4 | 131.4 | 146.8 |
| 2019-Q4 | 131.5 | 149.6 |
| 2020-Q4 | 138.1 | 153.3 |
| 2021-Q4 | 155.7 | 168.4 |
| 2022-Q4 | 171.9 | 182.1 |
| 2023-Q4 | 180.4 | 194.2 |
| Average | 2.30% | 2.90% |
Upon comparing the average growth rates of HDBs and non-landed private properties over the past decade, it becomes apparent that since 2017, non-landed private property prices have exhibited a more rapid appreciation rate than HDBs. This trend is commonly observed during upmarkets, as depicted in the graph below.
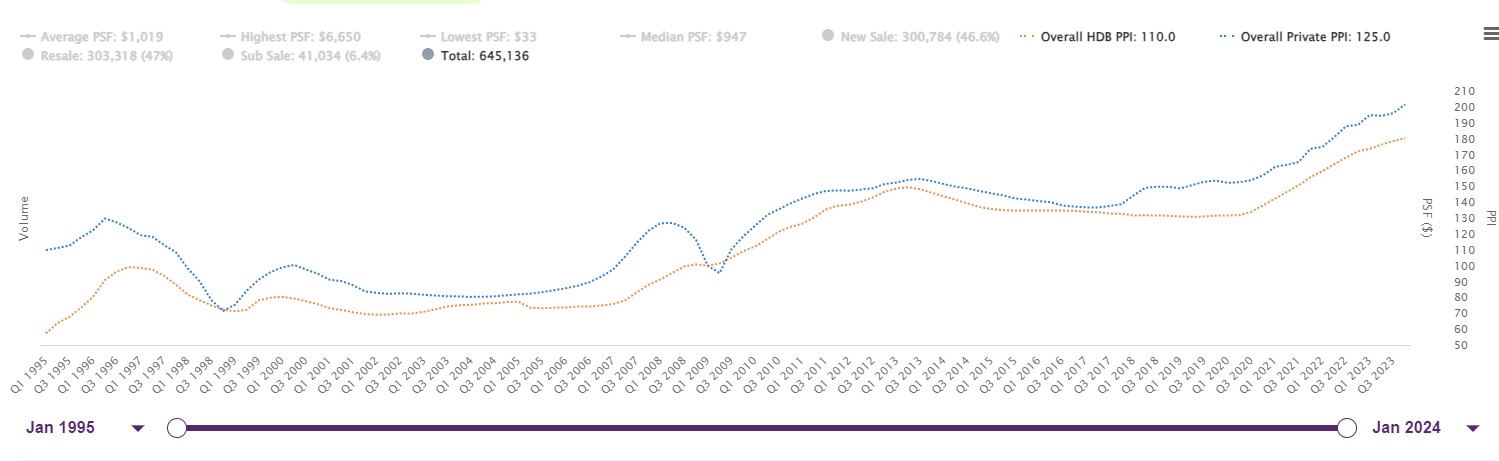
When comparing Option 1 (buying two private properties) and Option 2 (buying one HDB property and one private property), it's possible that Option 1 could provide higher returns. However, the actual performance depends significantly on the particular properties you choose to invest in.
| Options | Costs incurred (after deducted rental gains) | Rental gains |
| 1. Sell HDB, buy a resale 3-bedroom condo (and a second property for investment) | $690,826 | $330,000 |
| 2. Sell HDB, buy another HDB under the owner-occupier arrangement, and buy a private property after MOP | $203,241 | $225,000 |
Examining the table above, the discrepancy in costs between the two options is notably larger than the disparity in rental gains, despite the fact that Option 1 entails holding the investment property for an additional 5 years compared to Option 2.
Of the two alternatives, Option 2 emerges as more prudent, considering its significantly lower costs associated with purchasing an HDB and the possibility of evaluating market conditions during the Minimum Occupation Period (MOP). Especially given your aim of acquiring the second property for rental income, it appears that extending the investment property's holding period by 5 years may not necessarily result in substantially higher rental earnings. However, this assumes that the rental yields for both properties are equivalent.
To conclude, you do seem like you are still in a very early stage of exploring what to do in terms of your next move. The good news is that financially you are in a healthy position that even if you were to make a move now with the high-interest rates - you would still be able to do so without too much risk.
Here’s how I would approach this decision. If you do have a very high need to get your child to a certain primary school, then it may be worth concretely exploring if you can make the move right now. It’s hard to really predict where the property market will be in the next couple of years, but you wouldn’t want to stress about it either when you really have to move - but find yourself at another property high and be priced out. Remember, the supply of listings for resale condos is unpredictable too. You could find the right project but are unable to find the right listing when you need it.
However, if just being close to a good primary school is good enough (and again, the definitions of good here are very subjective), then you have a much wider range of options, and you would be able to still take a little more time to wait and see what comes up.
At Stacked, we like to look beyond the headlines and surface-level numbers, and focus on how things play out in the real world.
If you'd like to discuss how this applies to your own circumstances, you can reach out for a one-to-one consultation here.
And if you simply have a question or want to share a thought, feel free to write to us at stories@stackedhomes.com. We read every message.




0 Comments