


The Core Central Region is about to be a new frontier again.
This is where the spotlight will be for the next part of the year - heck, for most of the year, in fact. About 14 new launches of the roughly 22 remaining are going to be in the CCR, once considered the stomping ground of affluent foreign investors. That so many launches are concentrated there is, by itself, unusual - but there’s more.
First, we’re also in an environment with 60 per cent Additional Buyers Stamp Duty (ABSD) on foreigners. Case in point: we were the third-most popular country for luxury homes for Chinese buyers in 2023, and we’ve slipped a long way to ninth place. And from word on the ground, it’s not just about stamp duties: money laundering concerns have added more proverbial flaming hoops for foreign buyers (and their agents) to jump through.
So, without the rich-foreigner market, developers are going to have to sell to Singaporeans or PRs. We’re a much more price-sensitive bunch; a price tag of $1.8 million gives many of us the shakes, let alone an amount like $3 million (entirely plausible for a family-sized unit in our most pricey region).
For developers who are used to traditional CCR affluence (e.g., Ultra High Net Worth foreigners who think $3 million is a pretty cheap vacation), this is a massive shift. Like someone barging into the kitchen of a Michelin-star restaurant, and telling the head chef, “Eh, next week reduce to hawker centre price ah.”
Second, let’s look at the backdrop of when this is happening: we’re at the start of what looks to be a very long and chaotic four years. It would be volatile enough if this pivot to the CCR happened in “regular” times, but now it’s happening while fear is in the air.
And yes, I’ve heard the contrarian arguments about why that makes it a good time to buy; but the typical home buyer isn’t making purchases based on property price cycles. They make decisions based on questions like “Will I still have my job over the next four years? Will my raise disappear because the boss wants to hoard materials before tariffs bite?”
That’s the objection that property agents and developers will face in the coming few years. And it’s a very tough objection to handle, in a region associated with words like “prime,” “freehold,” “luxury,” and “who else hasn’t sold a kidney yet?”
The third problem is the rather slow transformation of the CCR. This dense, heavily built-up area has ossified over the years. Like kway teow sitting under the air-con for too long, it has turned rigid and firm. Its identity, amenities, and infrastructure serve the old-school idea of a dedicated shopping district or office district.
(Look, way back when policemen were still ironing their shorts, we thought it was a really cool idea to organise cities into neat and highly focused zones, okay? )
This results in a region with too little in the way of schools, green spaces, and all-around family vibes. There are planned changes to be sure; and perhaps in time it will become a more balanced live-work-play area. But this takes time and trust in the system; and for now, many home buyers don’t see family hubs in the CCR.
Everything old feels new again.
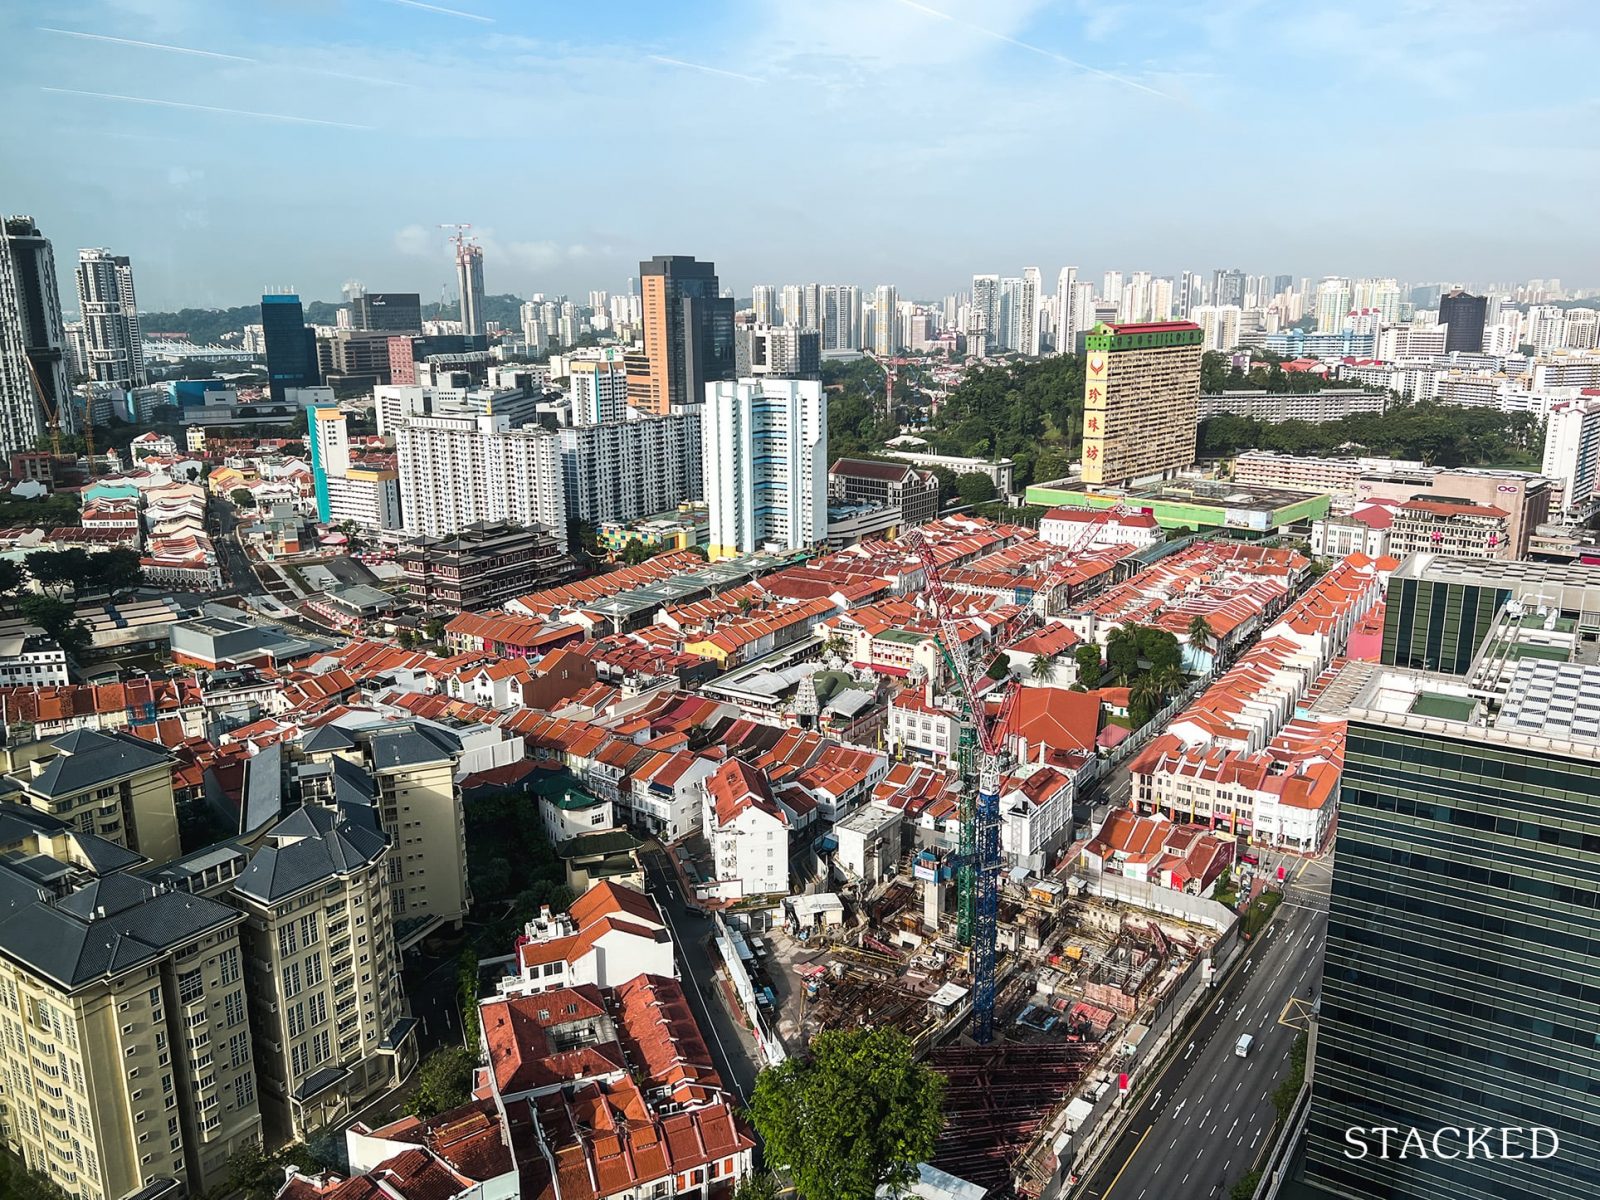
It’s strange because the very familiar central area has, in this sense, become like a new territory that buyers, developers, and agents are only just now probing. This is also why some of our recent content has been more focused on the CCR: not simply because there’s a lot of new launches there (although that’s one reason), but also because it’s time to rethink old assumptions.
Are two-bedders in the CCR really just a rental play, or can they, in fact, be family homes? How much does the freehold status of most units in the CCR matter? Is an old luxury CCR condo (and some of them are very old) still “luxurious” by today’s standards?
It’s time to take a fresh look; and a transformation of the CCR into a more family-oriented area may be a huge milestone in our attempts to decentralise.
In other property news this week…
- Despite the seller usually footing the bill, some condo buyers still opt to buy without a buyer’s agent. Fine, of course, but there are some drawbacks to consider.
- There’s an old saying that if you want to invest in a one-bedder (shoebox), the best place to do it is in the CCR. But how well do CCR one-bedders really perform? Here’s what it looks like after eight years' worth of data.
- If you’re looking at new launches, then odds are affordability = two-bedder. But what if I told you that, if you switch to resale, the same price can get you a three-bedder? Here’s where to look.
- I spoke to some homeowners who are way more hardcore than I am. As it turns out, some Singaporeans can move closer to work, but choose to stay far from it anyway.
Weekly Sales Roundup (14 April - 20 April)
The challenge for many buyers today isn't access to information.
It's interpreting that information in a way that makes sense for their finances, goals, and stage of life.
Over time, that's also why we decided to work with agents who shared the same data-driven and advisory-led approach behind our editorial, consultants who could help readers think through decisions more objectively, rather than simply push transactions.
Today, the team has worked with more than 2,000 clients across over $5B in property transactions.
Top 5 Most Expensive New Sales (By Project)
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | TENURE |
| 21 ANDERSON | $23,014,000 | 4489 | $5,127 | FH |
| ONE MARINA GARDENS | $4,976,908 | 1647 | $3,022 | 99 years |
| THE ORIE | $3,943,000 | 1453 | $2,713 | 99 yrs (2024) |
| THE CONTINUUM | $3,828,000 | 1270 | $3,014 | FH |
| GRAND DUNMAN | $3,789,000 | 1432 | $2,647 | 99 yrs (2022) |
Top 5 Cheapest New Sales (By Project)
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | TENURE |
| ONE MARINA GARDENS | $1,196,957 | 431 | $2,780 | 99 years |
| PARKTOWN RESIDENCE | $1,268,000 | 506 | $2,506 | 99 yrs (2023) |
| BLOOMSBURY RESIDENCES | $1,346,000 | 570 | $2,359 | 99 years |
| NOVO PLACE | $1,367,000 | 872 | $1,568 | 99 yrs (2023) |
| LUMINA GRAND | $1,382,000 | 936 | $1,476 | 99 yrs (2022) |
Top 5 Most Expensive Resale
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | TENURE |
| LEONIE GARDENS | $6,300,000 | 3617 | $1,742 | 99 yrs (1990) |
| ASTRID MEADOWS | $5,455,000 | 2433 | $2,242 | FH |
| THE ORCHARD RESIDENCES | $5,399,900 | 1808 | $2,986 | 99 yrs (2006) |
| THE GLYNDEBOURNE | $5,000,000 | 2174 | $2,300 | FH |
| THE WATERSIDE | $4,880,000 | 2142 | $2,278 | FH |
Top 5 Cheapest Resale
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | TENURE |
| THE HILLFORD | $550,000 | 398 | $1,381 | 60 yrs (2013) |
| STRATUM | $658,000 | 431 | $1,528 | 99 yrs (2012) |
| OPAL SUITES | $666,666 | 409 | $1,630 | FH |
| RIPPLE BAY | $708,000 | 484 | $1,462 | 99 yrs (2011) |
| CITY LOFT | $720,000 | 420 | $1,715 | FH |
Top 5 Biggest Winners
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | RETURNS | HOLDING PERIOD |
| 21 ANDERSON | $23,014,000 | 4489 | $5,127 | $20,462,000 | 18 Years |
| THE WATERSIDE | $4,880,000 | 2142 | $2,278 | $3,130,000 | 19 Years |
| THE HORIZON | $3,860,000 | 1722 | $2,241 | $2,560,000 | 21 Years |
| ASTRID MEADOWS | $5,455,000 | 2433 | $2,242 | $1,830,000 | 8 Years |
| THE SIXTH AVENUE RESIDENCES | $3,250,000 | 1518 | $2,141 | $1,824,360 | 18 Years |
Top 5 Biggest Losers
| PROJECT NAME | PRICE S$ | AREA (SQFT) | $PSF | RETURNS | HOLDING PERIOD |
| THE ORCHARD RESIDENCES | $5,399,900 | 1808 | $2,986 | -$1,199,300 | 15 Years |
| MARINA ONE RESIDENCES | $2,608,000 | 1281 | $2,036 | -$176,000 | 17 Years |
| ICON | $1,158,000 | 700 | $1,655 | -$130,000 | 13 Years |
| 76 SHENTON | $1,320,000 | 624 | $2,114 | -$91,700 | 15 Years |
| LA VIDA @ 130 | $1,200,000 | 936 | $1,281 | -$83,000 | 13 Years |
Transaction Breakdown

Follow us on Stacked for updates about the Singapore property market.
At Stacked, we like to look beyond the headlines and surface-level numbers, and focus on how things play out in the real world.
If you'd like to discuss how this applies to your own circumstances, you can reach out for a one-to-one consultation here.
And if you simply have a question or want to share a thought, feel free to write to us at stories@stackedhomes.com. We read every message.





0 Comments