


For younger Singaporeans, 2025 must seem like a strange year: many of the upcoming new launches are coming closer and closer to the city centre. And for those of us who grew up in the ‘80s and ‘90s, regions like the RCR and CCR were an untouchable luxury area where only the rich could stay*. Only the wealthy could claim to have the best amenities in easy reach. Today though, decentralisation means the “prime” areas may be shifting; and the prices of even non-central properties are closing the gap with some of the more prime regions. For this reason, I decided to take a quick look at what’s happening with today's new launches, and consider how the Singapore property scene is changing:
*Though for us born before the ‘70s, there were still big differences, such as when Katong was pricier than Orchard.
A look at the current new launches
Here’s the most updated look at current new launches, as of 25th May 2025. It’s not exactly the end of Q2 yet, but I think we are close enough. As you can see, there are quite a few in the CCR already, and for the latter part of the year, around 14 of the roughly 22 new launches will also be within the CCR:
West Projects
| Launched Date | District | Project | Total Units | Total Sold | Sold % | Balance Units |
| 25 Feb 2023 | 5 | Terra Hill | 270 | 139 | 51.48% | 131 |
| 29 Apr 2023 | 5 | Blossoms by the Park | 275 | 259 | 94.18% | 16 |
| 20 Apr 2024 | 5 | The Hill @ One North | 142 | 90 | 63.38% | 52 |
| 20 Apr 2024 | 5 | The Hillshore | 59 | 5 | 8.47% | 54 |
| 22 Feb 2025 | 5 | ELTA | 501 | 328 | 65.47% | 173 |
| 12 Apr 2025 | 5 | Bloomsbury Residences | 358 | 133 | 37.15% | 225 |
| 15 Jul 2023 | 21 | Pinetree Hill | 520 | 443 | 85.19% | 77 |
| 16 Nov 2024 | 21 | Nava Grove | 552 | 432 | 78.26% | 120 |
| 21 Sept 2024 | 21 | 8 @ BT | 158 | 88 | 55.70% | 70 |
| 5 Aug 2023 | 22 | The Lakegarden Residences | 306 | 229 | 74.84% | 77 |
| 11 Nov 2023 | 22 | J'den | 368 | 345 | 93.75% | 23 |
| 6 Jul 2024 | 22 | Sora | 440 | 190 | 43.18% | 250 |
| 8 Jul 2023 | 23 | The Myst | 408 | 340 | 83.33% | 68 |
| 12 Aug 2023 | 23 | The Arden | 105 | 104 | 99.05% | 1 |
| 20 Jan 2024 | 23 | Hillhaven | 341 | 314 | 92.08% | 27 |
Central Projects
| Launched Date | District | Project | Total Units | Total Sold | Sold % | Balance Units |
| 1 Jun 2016 | 1 | V on Shenton | 120 | 119 | 99.17% | 1 |
| 5 Nov 2022 | 9 | Hill House | 72 | 45 | 62.50% | 27 |
| 19 Nov 2022 | 9 | Sophia Regency | 38 | 0 | 0.00% | 38 |
| 12 Aug 2023 | 9 | Orchard Sophia | 78 | 49 | 62.82% | 29 |
| 6 Nov 2024 | 9 | The Collective @ One Sophia | 367 | 79 | 21.53% | 288 |
| 8 Mar 2022 | 11 | Ikigai | 16 | 14 | 87.50% | 2 |
| 20 Jan 2024 | 12 | The Arcady at Boon Keng | 172 | 74 | 43.02% | 98 |
| 18 Jan 2025 | 12 | The Orie | 777 | 706 | 90.86% | 71 |
North Projects
| Launched Date | District | Project | Total Units | Total Sold | Sold % | Balance Units |
| 4 May 2024 | 19 | Jansen House | 21 | 8 | 38.10% | 13 |
| 2 Nov 2024 | 19 | The Chuan Park | 916 | 762 | 83.19% | 154 |
| 19 Oct 2024 | 25 | Norwood Grand | 348 | 294 | 84.48% | 54 |
| 8 Jul 2023 | 26 | Lentor Hills Residences | 598 | 596 | 99.67% | 2 |
| 11 Nov 2023 | 26 | Hillock Green | 474 | 440 | 92.83% | 34 |
| 2 Mar 2024 | 26 | Lentoria | 267 | 205 | 76.78% | 62 |
| 16 Mar 2024 | 26 | Lentor Mansion | 533 | 533 | 100.00% | 0 |
| 8 Mar 2025 | 26 | Lentor Central Residences | 477 | 469 | 98.32% | 8 |
East Projects
| Launched Date | District | Project | Total Units | Total Sold | Sold % | Balance Units |
| 4 Feb 2023 | 14 | Gem ville | 24 | 9 | 37.50% | 15 |
| 23 Feb 2018 | 15 | The Line @ Tanjong Rhu | 54 | 45 | 83.33% | 9 |
| 21 May 2022 | 15 | 15 Atlassia | 39 | 35 | 89.74% | 4 |
| 8 Oct 2022 | 15 | K Suites | 19 | 9 | 47.37% | 10 |
| 26 Nov 2022 | 15 | 15 Claydence | 28 | 8 | 28.57% | 20 |
| 8 Apr 2023 | 15 | Tembusu Grand | 638 | 592 | 92.79% | 46 |
| 6 May 2023 | 15 | The Continuum | 816 | 590 | 72.30% | 226 |
| 15 Jul 2023 | 15 | Grand Dunman | 1008 | 785 | 77.88% | 223 |
| 2 Mar 2024 | 15 | Koon Seng House | 17 | 9 | 52.94% | 8 |
| 11 May 2024 | 16 | 15 Straits @ Joo Chiat | 16 | 13 | 81.25% | 3 |
| 16 Nov 2024 | 15 | Emerald of Katong | 846 | 845 | 99.88% | 1 |
| 14 Jan 2023 | 16 | Sceneca Residence | 268 | 265 | 98.88% | 3 |
| 18 Jan 2025 | 16 | Bagnall Haus | 115 | 92 | 80.00% | 23 |
| 23 Sept 2023 | 17 | The Shorefront | 23 | 9 | 39.13% | 14 |
| 20 Jul 2024 | 17 | Kassia | 276 | 203 | 73.55% | 73 |
| 22 Feb 2025 | 18 | Parktown Residence | 1193 | 1073 | 89.94% | 120 |
EC Project Balance
| Launched Date | District | Project | Total Units | Total Sold | Sold % | Balance Units |
| 5 Aug 2023 | 23 | Altura | 360 | 355 | 98.61% | 5 |
| 27 Jan 2024 | 23 | Lumina Grand | 512 | 503 | 98.24% | 9 |
| 16 Nov 2024 | 24 | Novo Place | 504 | 492 | 94.62% | 12 |
Some observations of the new launches above
I have noticed some changes happening so far at the following new launches, which is why their sales are going up:
- Bloomsbury Residences
- The Hill at One North
- Nava Grove
- Hillhaven
- Hillock Green
- One Marina Gardens
1. Bloomsbury Residences
Shortlists like this are a useful starting point, but the units that make the list aren't necessarily the ones that make the most sense for your budget, lifestyle or long-term plans.
The harder part comes afterwards: comparing the trade-offs, evaluating the numbers, and deciding which home is actually the best fit for your situation.
Over time, that's also why we decided to work with agents who shared the same data-driven and advisory-led approach behind our editorial, consultants who could help readers think through decisions more objectively, rather than simply push transactions.
Today, the team has worked with more than 2,000 clients across over $5B in property transactions.
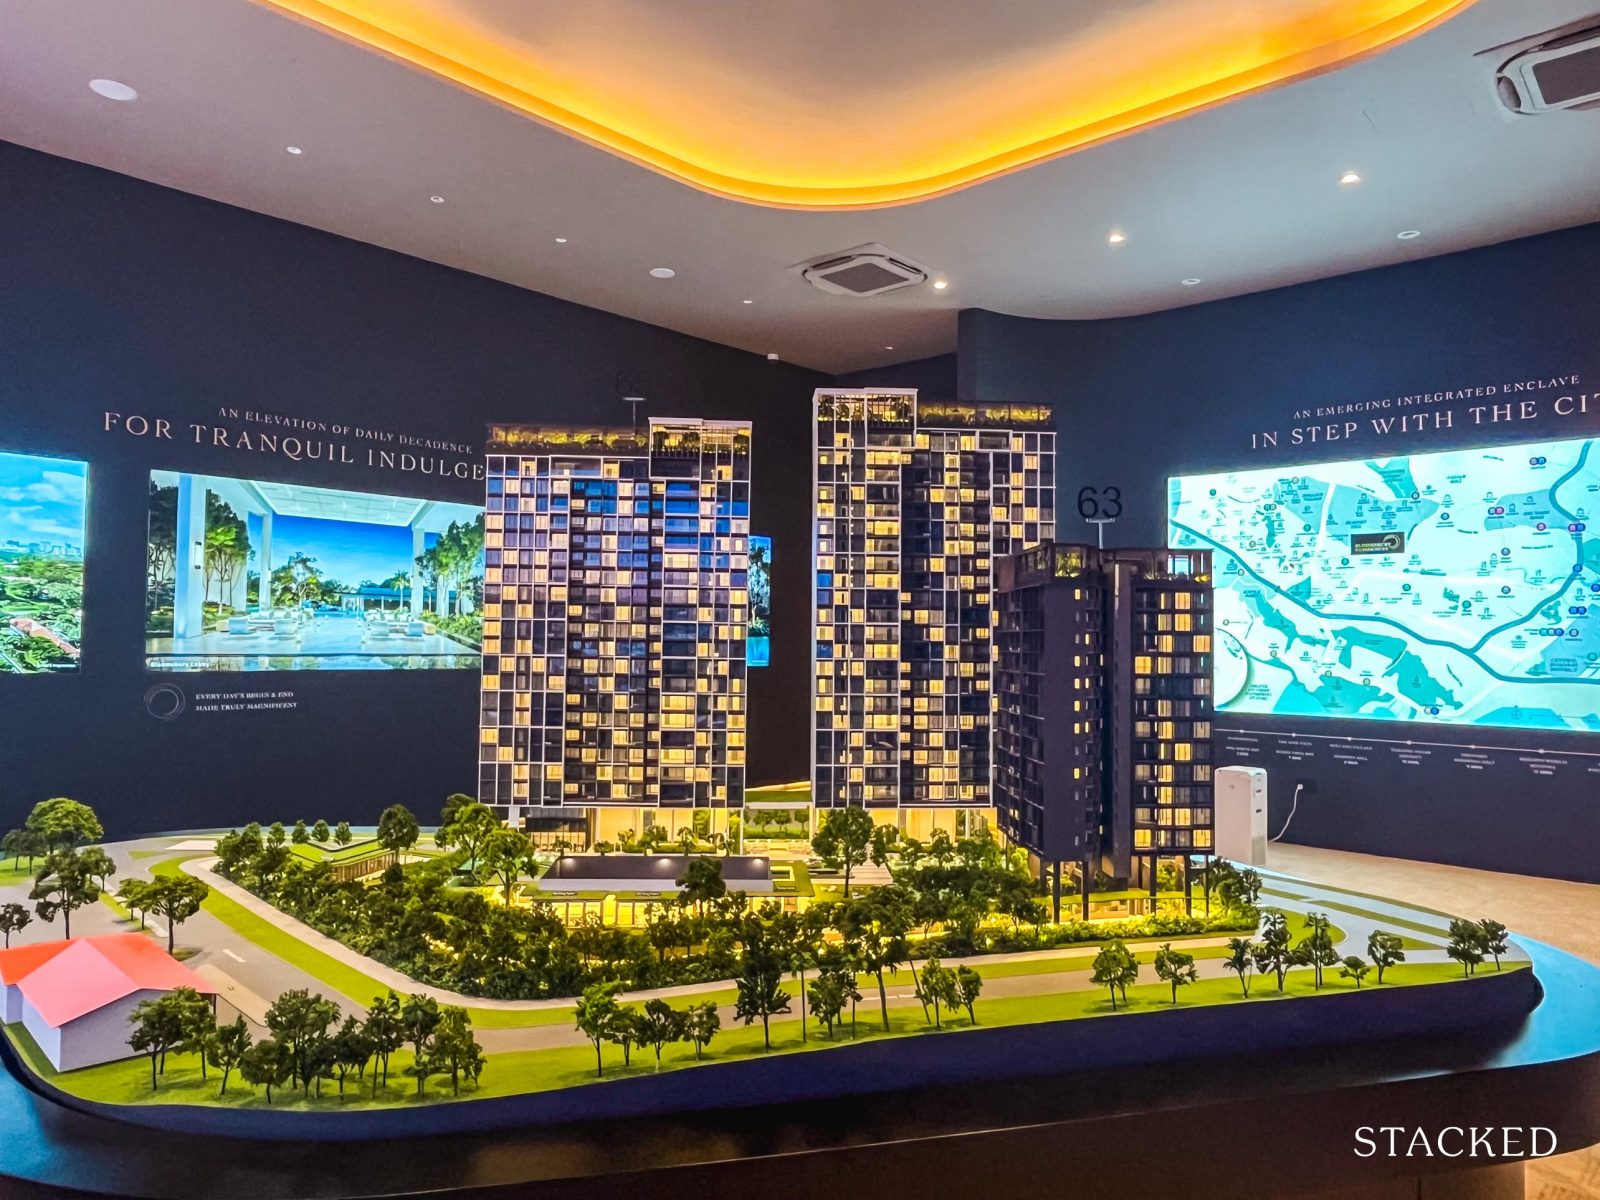
Bloomsbury Residences has just moved six more units, at the time I write this. According to agents, this is because there are unverified suggestions that the developer is about to raise the prices, but I also think the preview of the upcoming LyndenWoods is helping.
LyndenWoods is just a few streets away but nearer than it looks, so attention swings back to the Bloomsbury Residences; buyers are now taking a second look at the location and will surely compare LyndenWoods with Bloomsbury’s remaining units. LyndenWoods does seem bigger and flashier, and is closer to the Holland Road area; but this can help to reframe Bloomsbury as a more tranquil alternative
Anyway, the marketing for Bloomsbury Residences keeps emphasising the One-North area, which has places like Fusionopolis, and a lot of tech and media companies. There’s surely a lot of tenants for investors here today, even though in the past the area was famous for quiet stretches for cyclists.
(In the 1990s, the roads from Rochester Hill, where Bloomsbury is, down to Dover Rise and Portsdown were loved by cyclists. And also by snakes!)
If you buy a Bloomsbury condo, you can visit Wessex Estate, which is very nearby. This area has some old colonial black-and-white bungalows, although they don’t look very well preserved to me.
2. The Hill at One North
The Hill moved five more units, and I think buyer interest will pick up soon. It’s been a little bit slow going as I saw only 40 per cent of the 142 units are sold. Right now, I see a lot of co-working cafes, pixel-font signage for tech companies, etc, in this area, so maybe people still think of it as a work hub more than a family zone. Still an improvement though, as for most of my younger days, this place was nothing but transmission towers and NS jungle training.
Nonetheless, I think the rental potential is good, and maybe it will draw some interest from landlords. One of the reasons for the pick-up may be that the Temporary Occupancy Permit (TOP) is drawing close in 2026. While the price is higher if you buy later, there are also some buyers who prefer it anyway, because they don’t need to wait as long before they can move in. And if you’re a landlord, I suppose the sooner it’s built, the sooner you can start collecting your rent.
I think the location is underrated. At street level, the immediate area feels curated but not over-curated. You’re near One-North MRT, but far enough that the morning rush is not going to trouble you.
3. Nava Grove
Nava Grove just moved three more units in the week I wrote this, but I expect a whole lot more shortly (or maybe even by the time you read this). There are two big updates at this new launch, one good and one bad:
First, it is now confirmed that Nava Grove is within one-kilometre of Henry Park Primarytackedhomes.com/touring-jalan-jelita-freehold-landed-houses-behind-cold-storage-jelita-and-within-1-km-of-henry-park-primary-school/">Henry Park Primary School. This is based on its postal code and the official OneMap tool. As most Singaporeans will know, this is a big deal since it provides priority enrolment into the school. So now the residents can join the parade of expensive cars lining up at the school at 6.45 am :)
The second big piece of news, which is not so good for buyers, is that a price increase was instituted on 2nd June, which will be by the time you read this. The increase is between 0.5 to one per cent, which effectively came to about $10,000+ for smaller units like one and two-bedders, or about $30,000+ for larger units like four-bedders and above.
It’s not too big a jump though; and as developers always raise the prices in later sales phases anyway, it makes sense they would do it in tandem with confirmation of Henry Park Primary being in Home School Distance.
Another thing which may interest homebuyers: Nava Grove is a post-harmonisation project, which means “useless” square footage like air-con ledges are excluded.
Usually, a post-harmonisation project will have lower square footage on paper; but looking at the two-bedders, they are from 624 to 700 sq ft, the same size as pre-harmonisation projects. Likewise, the three-bedders are from 990 to 1,109 sq ft, a size that is normal for pre-harmonisation projects.
This means that Nava Grove is actually bigger and more spacious on average, as it has the same square footage of pre-harmonisation condos, but also excludes air-con ledges and other wasted space!
4. Hillhaven
I noticed three more units moved here over the week, and I am surprised no one has caught on yet. Hillhaven should ‘t be overlooked despite being smaller: it’s within walking distance to Hillview MRT (DTL), it’s near Hill V2 Mall, and the entry PSF and overall quantum are lower than many of the alternatives.
The entry PSF for Hillhaven was around $1,900 to $1,950 psf, and is now about $2,075 psf. But if you look at Midwood @ Dairy Farm or The Botany as nearby comparisons, these are around $2,100 to $2,300 psf.)
So, how come all 341 units didn’t go sooner? I think maybe it’s because Hillhaven is not in a more high-profile area, like the "transformation zone" of Lentor, or high prestige estates like Marina South, etc. So perhaps it’s not as attention-grabbing as many of the current new launches.
5. Hillock Green
Hillock Green moved five more units over the week, and this may be because of ongoing developments in Lentor. There are fewer options as the nearby Lentor condos like Lentoria, Lentor Modern, Lentor Central Residences, etc., get snapped up; and those unable to secure a unit at these projects will probably look towards Hillock Green.
I can definitely see the appeal of this area. Right up till the early ‘00s, the north region of Singapore wasn’t really as ripe for condo living. It was just rocky ridges, water catchments, and old rubber trees behind utility fences. So it was quite shocking how fast the area could change after the launch of Lentor MRT (TEL), which is within walking distance of Hillock Green by the way. It went from a quiet trickle of GLS sites to a large private condo enclave, almost overnight, to me.
It isn’t just a first-mover advantage, but a first-mover advantage that’s happening fast; Lentor Modern is even mixed-use and will add a mall to the area. I think this area will be rewarding for the initial batch of buyers because it’s starting from a low baseline.
6. One Marina Gardens
One Marina Gardens is a good sign of things to come, moving another 12 units(!) in the week I wrote this. While it’s not in the CCR per se, it is part of an upcoming pivot toward more “prime” areas, and acceptance of condos like One Marina Gardens may signify a needed change. To explain:
There are few places in Singapore where land feels this choreographed. One Marina Gardens is all glassy frontage and billion-dollar backdrops today, but before the Marina Bay development, this was a patch of land that took about 40 years to become Singapore’s calling card, and now Marina Bay is practically a national icon of sorts.
But that may also be the reason for the gradual rather than immediate pick-up. This is an area that’s still far from schools and what some would call “grassroots.” It’s not the kind of neighbourhood you grew up in with friends and families, and if you move here, they may be far away; so there has to be a perspective shift.
If the Marina Bay area can appear less “atas” and detached, and a true live-work-play area, then future projects here may move faster than One Marina Gardens. But still, we can see from the units being sold that it’s picking up steam. There’s also quite a lot of confidence in URA’s transformation attempts, thanks to past history in areas like Jurong, so buyers can trust the Marina area to become more balanced and developed over time.
A quick reflection on the previous CCR boom, and where we’re headed
It’s been a very long time, around a decade, since we last saw a CCR boom (by which I mean an unusually high presence of new launches in the region). The last time the CCR took the spotlight was from 2005 to 2011.
At the time, projects like The Marq on Paterson Hill, L’viv, Rivergate, and other high-end projects dominated news cycles. However, the situation then wasn’t the same as what we’re seeing now. In the 2005 to 2011 surge, we saw mainly investment-heavy, foreign-led demand. This was especially true after the 2008/9 Global Financial Crisis, when Singapore property became seen as a safe haven asset.
So while there was a CCR pivot back then, it was mainly for investors with deep pockets or rich foreigners. Today, the situation is different:
In Q1, the median PSF for CCR condos clocked in at S$2,554. This is a mere seven per cent premium over the Rest of Central Region (RCR), which registered S$2,386 psf. This is a historically small gap. We can see, right now, CCR condos at $2,800 to $3,300 psf, which is also below the 2024 CCR market average of $3,305 psf.
Part of this is definitely due to the 60 per cent Additional Buyers Stamp Duty (ABSD) on foreign buyers. You might also say the unstable global economy is to blame. But I think we need to look beyond surface issues:
With decentralisation, Areas like Lentor, Mountbatten, and one-north are no longer “outskirts.” They’re becoming mini-cores, shaped by new amenities and patterns of living. Decentralisation was never just about jobs closer to homes; I feel that’s just the textbook answer from URA.
Nodes like Paya Lebar, Jurong, Tampines, maybe even Punggol with its digital district or Pasir Ris with North Shore, may one day be seen as a closer equal to CCR towns (even if they don’t actually match it in price!) And with lower CCR prices today, 2025 may be the inflection point that we don’t yet recognise.
Maybe 15 to 20 years in the future, this will be the year that historians or market watchers point to as the one where the idea of our CCR truly changed.
Round-ups like this are a good place to start a shortlist, but the real work begins when you start comparing the final few options, looking beyond the headline criteria to decide which property is the best fit for your own situation.
That's where many readers ask us to help.
If you'd like a second view on any of the units above (or others we haven't listed), you can reach out for a one-to-one consultation here.
And if you simply have a question or want to share a thought, feel free to write to us at stories@stackedhomes.com. We read every message.




0 Comments